Acorns: Invest For Your Future
- Rating
- 4.7
- Downloads
- 10,000,000+
- Age
- Everyone
Additional Info
- App Name
- Acorns: Invest For Your Future
- Category
- Finance
- Package Name
- com.acorns.android
- Developer
- Acorns
- Rating
- 4.7
- Version
- 4.172.0
 Analysis by Appcrazy
I found Acorns most useful as a gentle starting point for people who want to build an investing habit without turning every spare minute into a research session. It is a finance app from Acorns that focuses on making long-term money habits feel more manageable. My overall view is positive, but with an important qualification: it is better suited to gradual, automated investing than to people who want detailed control over every security, trade, or portfolio decision.
The app is free to download and is rated for Everyone, which makes its presentation approachable rather than intimidating. It has been available since October 7, 2014, and its reach is substantial, with over ten million installs. That level of adoption does not prove that it will fit every financial situation, but it does suggest that the basic idea has connected with a large audience.
How Acorns turns small decisions into a regular investing routine
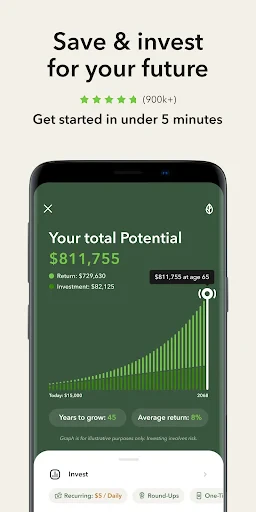
The central appeal is the way Acorns frames investing as part of ordinary spending and saving behavior. Instead of requiring me to begin with a large, carefully planned deposit, the experience is designed around making progress in smaller steps. That is a meaningful difference for someone who keeps postponing investing because the subject feels complicated or because a traditional brokerage account seems too hands-on.
In practice, I would treat the app as a habit-building tool first and an investment research tool second. The strongest use case is a person who understands that investing matters but struggles to make it consistent. A recurring routine can be more valuable than an ambitious plan that never gets started, and this is where the app’s design makes sense.
A realistic example is a user who checks their bank balance after everyday purchases and wants those transactions to contribute to a longer-term goal rather than disappearing unnoticed. With Acorns, that person can make investing feel connected to normal financial activity. The benefit is psychological as much as practical: the process can seem less like a major event and more like a background habit.
That convenience also creates the first trade-off. Small amounts can be easier to commit to, but they do not remove the need to understand where money is going, how long it should remain invested, or what level of market movement is acceptable. Automation can reduce hesitation, yet it can also make a user less attentive if they never review the broader plan.
The strongest part is lowering the barrier to entry
I think Acorns works best when the main obstacle is uncertainty. New investors often ask themselves how much they need, when to begin, and whether they must understand every market term before taking action. The app’s approachable structure helps answer those emotional questions. It encourages a first step instead of demanding that a beginner become an expert in advance.
That is especially useful for people who prefer a guided experience. Someone who feels comfortable with simple prompts and broad choices may appreciate the reduced decision load. Rather than spending an evening comparing individual companies, the user can focus on establishing a repeatable pattern and learning gradually along the way.
Take a Look at Our Blog

My Talking Tom 2 and the New Rhythm of Casual Play
Why Children's doctor : dentist Makes Dental Care Feel Like Play
Should You Switch to Android Auto? What the Change Really Involves
Where Wordscapes Holds Up and Where It Breaks
LinkedIn: Streamline Your Career with Powerful Networking Tools
Why Baby Panda Care Captivates Young Minds
The app’s public reception is also notable. It holds a 4.7 average from roughly 375,000 ratings, alongside around 77,000 written reviews. I would not use those figures as a substitute for personal research, because financial needs differ widely, but they do indicate that many users have found the overall experience accessible enough to rate positively.
Another strength is that the app can make financial conversations more concrete. It is easier to discuss a savings or investing habit when the user can see an ongoing routine rather than an abstract promise to “start someday.” For a friend who has never opened an investment account, I would consider Acorns a less intimidating introduction than a platform built primarily for active trading.
Useful habits that are easy to overlook
One practical approach is to use the app as a review point rather than simply leaving it to run unattended. I would set a regular calendar reminder to look at contributions, confirm that the chosen approach still matches my time horizon, and check whether daily spending has changed. This keeps automation useful without pretending that “automatic” means “set it and forget it forever.”
A second insight is to separate the app’s convenience from an emergency fund. Investing money that might be needed next week can create unnecessary stress if markets move at the wrong time. I would first make sure short-term bills and essential cash needs are handled elsewhere, then use Acorns for money intended to stay invested for longer. That distinction is easy for beginners to miss because the app makes adding money feel so simple.
A third useful workflow is to begin with a modest routine and observe whether it fits the real household budget. The right amount is not the amount that looks impressive on the first day; it is the amount that remains comfortable after rent, food, transport, debt payments, and unexpected expenses. If an automated contribution repeatedly causes a user to move money back out, the habit is too aggressive and should be adjusted.
Only Want to Download? Acorns: Invest For Your Future
I also see value in using the app as a learning bridge. A beginner can start with the guided experience, then gradually compare it with broader financial tools and decide whether more control is needed later. In that sense, Acorns does not have to be a permanent home for every investor. It can be a low-friction first stage for someone who wants to become more confident before considering a traditional brokerage platform.
Where the simplicity becomes a limitation
The same simplicity that makes Acorns friendly can feel restrictive to an experienced investor. If I want to choose individual companies, build a very specific allocation, or make frequent tactical decisions, I would look elsewhere. This app is not the natural choice for someone whose main interest is hands-on portfolio construction or active trading.
There is also a risk that the polished, low-effort experience makes investing appear more predictable than it really is. No interface can remove market risk, and a smooth setup does not guarantee a smooth result. Users still need to accept that investment values can rise and fall, especially when money is intended for a distant goal. Anyone uncomfortable with that basic reality should deal with the underlying concern before relying on an investing app.
Another point of friction is attention. A user may assume that small contributions automatically equal a complete financial plan. They do not. Retirement needs, debt strategy, insurance, taxes, emergency savings, and near-term goals can all matter more than simply opening an account. Acorns can support one part of a financial routine, but I would not treat it as a replacement for budgeting or personalized professional advice.
The free price is attractive for trying the experience, but “free” should not be interpreted as meaning that every possible financial consideration disappears. Before committing money, I would read the current account terms carefully and understand any applicable charges or conditions. That is normal good practice for a finance service, and it matters even more when the app’s main appeal is convenience.
The current version is 4.172.0 and the minimum operating system requirement is iOS 9 or later. Those details make the app relevant to a broad range of Apple devices, although I would still keep the operating system updated when possible. A financial app deserves the same basic care as a banking app: use a device you trust, protect the account, and avoid treating a familiar interface as a reason to skip security habits.
Who will get the most from it
I would recommend Acorns to a beginner who wants a simple path into long-term investing and who values consistency more than customization. It makes particular sense for someone who has already tried to save manually but keeps forgetting, delaying, or overthinking the first step. The app’s approachable tone can help turn a vague intention into a repeatable action.
It may also suit a busy worker who wants a low-maintenance routine and is willing to review it occasionally. In that situation, the important question is not whether the app offers every advanced tool, but whether its structure helps the person invest in a way they can maintain. A modest, sustainable pattern is often more realistic than an elaborate strategy that requires constant attention.
I would be more cautious about recommending it to someone carrying expensive debt, lacking accessible emergency savings, or needing the money for a near-term purchase. Those users may benefit more from stabilizing cash flow before investing. I would also point experienced investors toward a conventional brokerage service if they need detailed research, precise order control, or a wider range of portfolio decisions.
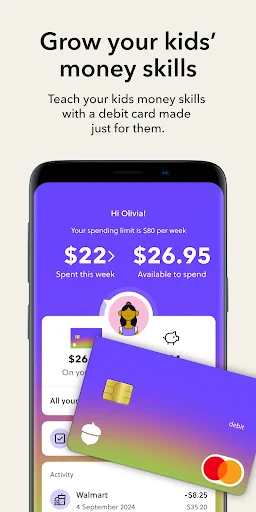
Parents and educators may find the app’s approachable presentation useful when introducing basic financial ideas, but I would still explain the difference between saving and investing. A child or complete beginner can understand the routine without automatically understanding volatility, time horizons, or the possibility of losses. The app can support the conversation; it cannot replace it.
How it compares with familiar alternatives
Compared with a standard bank savings account, Acorns offers a different purpose. A savings account is generally easier to understand for money that must remain available, while an investing app is aimed at longer-term growth and carries market exposure. I would not choose between them as if they were interchangeable. For me, the practical comparison is about the job each account is meant to perform.
Compared with a traditional brokerage platform, Acorns wins on approachability and loses on depth. A brokerage account is usually the better fit for someone who wants to select investments directly, study markets, and control the details. Acorns is more appealing when too many decisions would prevent the user from beginning at all.
Compared with doing nothing, the app’s biggest advantage is behavioral. It gives a hesitant person a structure to follow. However, that advantage only matters if the user chooses an amount that fits their budget and understands that investing is not a guaranteed shortcut to wealth. The app can make action easier, but it cannot make financial outcomes certain.
My final view after using the app
Acorns succeeds because it treats investing as a habit that can be built gradually rather than as a test of financial expertise. The developer, Acorns, has created an experience that feels especially well matched to beginners who want guidance and automation. Its strong 4.7 average and broad audience reinforce the impression that the basic approach is easy for many people to understand.
My recommendation is specific: use it if your main problem is getting started and staying consistent, not if your main goal is maximum control. Keep emergency money separate, choose a contribution that will not strain your monthly budget, and schedule occasional reviews so automation does not replace judgment. Those steps make the app’s simplicity work in your favor.
I would gladly suggest it to a friend who keeps saying they will invest later but needs a manageable first move. I would not suggest it as the only financial tool for someone with complex goals or a strong interest in active portfolio management. For the right user, the free app is a friendly doorway into investing; for the wrong user, its limited control may become frustrating. That balance is the key to deciding whether it belongs on your phone.
Pros
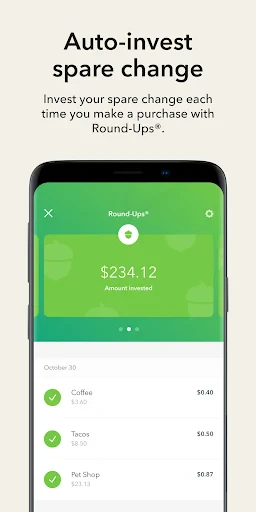
- Automated saving through round-ups.
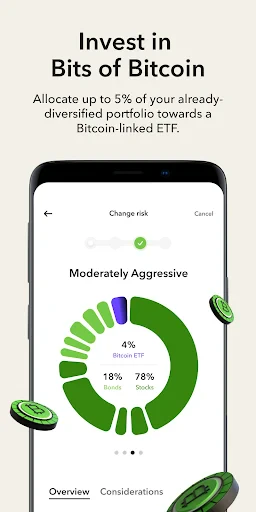
- Diverse portfolio options available.
- User-friendly interface design.
- Educational resources for beginners.
- No account minimums required.
Cons
- Monthly fees for accounts below $5
- 000.
- Limited customer support options.
- No tax-loss harvesting features.
- International users not supported.
- Not suitable for day trading.
Frequently Asked Questions
What is Acorns: Invest For Your Future?
Acorns: Invest For Your Future is a mobile app designed to help users save and invest money effortlessly. By rounding up your everyday purchases to the nearest dollar and investing the spare change into diversified portfolios, Acorns makes investing accessible and automatic. It's ideal for beginners who want to start investing without the complexities of traditional investment platforms.
How does the Round-Up feature work in Acorns?
The Round-Up feature in Acorns connects to your bank account and tracks your spending. Whenever you make a purchase, Acorns rounds up the transaction to the nearest dollar and invests the difference into your chosen portfolio. For instance, if you spend $3.25 on a coffee, Acorns will round it up to $4.00 and invest the 75 cents. This feature helps you invest small amounts automatically, building up your portfolio over time.
Is Acorns safe to use for investing?
Yes, Acorns is a secure platform for investing. It employs bank-level security measures, including 256-bit encryption and secure servers, to protect user data. Additionally, Acorns accounts are SIPC insured up to $500,000, which includes a $250,000 limit for cash claims. This ensures that your investments are protected in case of any unforeseen circumstances, giving you peace of mind while using the app.
What are the fees associated with using Acorns?
Acorns charges a monthly subscription fee, which varies depending on the plan you choose. The Personal plan costs $3 per month and includes investment, retirement, and checking accounts. The Family plan costs $5 per month and includes everything in the Personal plan along with investment accounts for kids. There are no additional fees for trades or hidden charges, making it a straightforward and transparent pricing model.
Can I withdraw my money from Acorns at any time?
Yes, you can withdraw your money from Acorns at any time. The process is simple and can be done directly through the app. Once you initiate a withdrawal, it typically takes 3-6 business days for the funds to be transferred to your linked bank account. However, it's important to note that market volatility can affect the value of your investments, which may impact the amount you receive upon withdrawal.