Affirm: Buy now, pay over time
- Rating
- 4.8
- Downloads
- 10,000,000+
- Age
- Everyone
Additional Info
- App Name
- Affirm: Buy now, pay over time
- Category
- Shopping
- Package Name
- com.affirm.central
- Developer
- Affirm, Inc
- Rating
- 4.8
- Version
- 3.402.1
 Analysis by Appcrazy
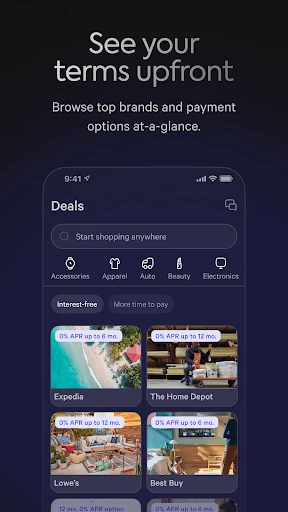
I found Affirm most useful when I treated it as a planning tool rather than a shopping shortcut. The app, developed by Affirm, Inc, lets me look for flexible ways to pay for purchases over time, while also surfacing opportunities to save. That combination makes it more practical than a simple checkout button, but it also means I have to pay attention to the terms attached to each purchase instead of assuming every plan works the same way.
My overall view is positive: Affirm is a convenient companion for a planned purchase when I already understand my budget. It is less convincing as a way to make an expensive item feel affordable merely because the first payment looks manageable. That distinction is the key to using it responsibly, and it is also the main reason I would recommend it to some shoppers but not to everyone.
What using Affirm feels like in everyday shopping
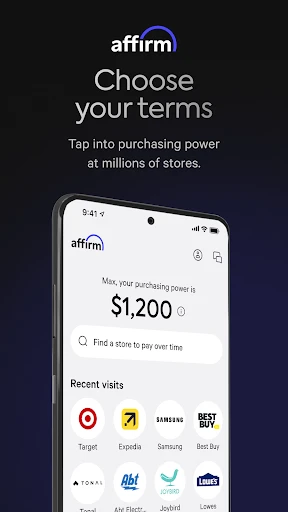
Affirm sits in the shopping category, but I do not experience it as a traditional marketplace in the same way I would experience a general retail app. Its value comes from helping me consider payment options around a purchase. I can use it when I am comparing a larger planned expense, checking whether spreading payments fits my monthly cash flow, or looking for a saving opportunity before completing an order.
The app is free to download, and its age rating is Everyone, which makes the basic experience approachable for a broad audience. It has also built a substantial user base, with over 10 million installs and a 4.8 average from around 532 thousand ratings. Those figures suggest that the service is familiar to many shoppers, although popularity alone does not remove the need to inspect the details of an individual payment plan.
In my experience, the most useful habit is to open the app before I am emotionally committed to a product. If I wait until I am already at checkout, I am more likely to focus on whether I can get the item immediately. Looking earlier gives me time to compare the total cost, consider the timing of payments, and decide whether the purchase is genuinely necessary.
A realistic example would be replacing a broken household item when the replacement costs more than I want to take from one paycheck. I would first work out the amount I can comfortably set aside each month, then use Affirm to examine the available payment arrangement. If the full commitment fits alongside rent, utilities, food, and existing bills, the flexibility may be worthwhile. If it only works by leaving no room for an unexpected expense, I would postpone the purchase or choose a less expensive alternative.
The strongest part is purchase planning, not impulse buying
The app’s strongest quality is that it puts financing information close to the shopping decision. Instead of thinking only about the sticker price, I can consider how the purchase affects several future paydays. That shift is valuable because a low recurring payment can be easier to understand when I view it beside my wider budget rather than in isolation.
Catch Up on the Latest Stories
Microsoft Teams on Mobile Keeps Work Moving, If You Keep It Tidy
Groupon Turns Local Discounts Into a Marketplace, With a Catch
App of the Week: Yandex Go Makes City Errands Easier
Make Xiaomi Weather Work Harder with Smarter Settings and Daily Routines
Boomplay Turns Music Streaming Into a Daily Discovery Habit
Google Docs on Mobile Keeps the Page in Focus, Until Formatting Gets in the Way
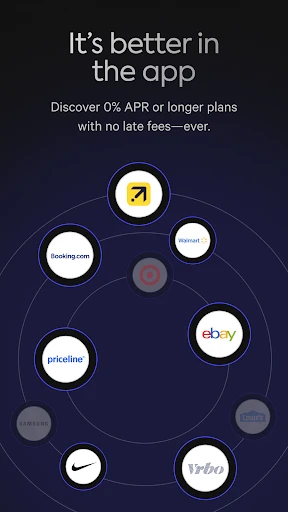
I also appreciate the possibility of using the app as a comparison checkpoint. Before choosing a retailer’s usual payment option, I can check whether Affirm presents a clearer or more suitable route. This does not automatically make Affirm cheaper, and I would never assume that a split payment is the best deal without reading the complete terms. Still, having another option can make the decision less one-sided.
One practical workflow I recommend is creating a short purchase note before opening the app. I write down the item, the maximum total I am willing to spend, and the date by which I need it. Then I compare the available arrangement against that limit. This prevents the app from turning a fixed need into an excuse to browse unrelated products or stretch the budget for a nicer version.
Another useful approach is to separate essential purchases from convenience purchases. For an essential replacement, flexible payments may help smooth a temporary cash-flow problem. For an upgrade, seasonal item, or entertainment purchase, I am much more cautious. If I can wait and save, that option usually gives me more freedom and avoids adding another future obligation.
Affirm is also more helpful when I think in terms of total commitment rather than the first scheduled amount. I check how many payments are involved, when they are due, and whether the complete cost still makes sense compared with paying immediately. This is not a glamorous feature, but it is the habit that determines whether the app supports good shopping decisions or encourages overextension.
Where the flexibility becomes less comfortable
The main weakness is psychological: dividing a purchase into smaller payments can make an expensive decision feel less serious. The app can present flexibility clearly, but it cannot know whether I already have several other commitments outside it. I have to do that accounting myself, and a shopper who focuses only on the amount due today may underestimate the effect of multiple plans running together.
I would therefore avoid opening a new plan simply because the monthly figure appears comfortable. I first total every existing installment, subscription, and recurring bill. Then I leave room for ordinary surprises, such as transport problems, repairs, or a higher grocery bill. If the new purchase only works under perfect conditions, it is not truly affordable for me.
There is also friction in comparing Affirm with ordinary payment methods. Paying in full is simpler: the transaction ends immediately, and I do not need to remember future dates. A standard credit card may offer its own protections or rewards, depending on the card and the purchase, while a retailer’s payment plan may have different terms. Affirm is not a universal replacement for either option. Its advantage is flexibility, not automatic superiority.
I would especially avoid treating the app like a source of free money. A payment plan is still a financial commitment, even when it feels tidy inside a shopping interface. Before confirming anything, I look for the total amount, the schedule, and any conditions that affect the plan. If I cannot explain the arrangement in plain language, I do not use it.
That caution matters for returns as well. When I buy something through a payment arrangement, I keep the order information and watch the transaction until the return or cancellation is fully resolved. Returning an item to a retailer and seeing the related payment commitment update are connected events, but I would not assume they happen instantly. Keeping records makes it easier to spot a problem early.
How it compares with paying in full, cards, and retailer plans
Compared with paying in full from a bank account, Affirm offers more breathing room but less simplicity. Paying immediately is usually my preferred choice when I already have the money set aside. There is no future schedule to track, and the purchase does not compete with later expenses. Affirm becomes more interesting when timing matters and the plan is genuinely manageable.
Compared with a credit card, the decision is more personal. A card may be more convenient for frequent spending, while Affirm can make a single larger purchase easier to isolate and review. On the other hand, a card may fit better for someone who already manages a balance carefully and values its established features. I would compare the complete cost and practical protections rather than choosing based on the smallest displayed payment.
Compared with a retailer’s own installment option, Affirm can be appealing when I want a separate place to review the purchase commitment. That separation may help me keep track of what I owe for a particular item. Yet the retailer’s option could be more convenient in a specific checkout flow, so I would still compare both before deciding. The best choice depends on the actual terms and my ability to manage another scheduled obligation.
The app’s savings angle is useful when it leads me to a better purchase decision, not when it simply encourages more browsing. I use savings information as a reason to compare, not as permission to spend. A discount on an item I do not need is still an expense, and spreading that expense out does not change the underlying decision.
Small habits that make the app safer to use
I would begin by checking the plan before placing the order, not after. That gives me a chance to compare the total with the cash price and to decide whether the purchase belongs in this month’s budget. I also avoid opening several plans in quick succession, because separate small commitments can become difficult to see as one combined obligation.
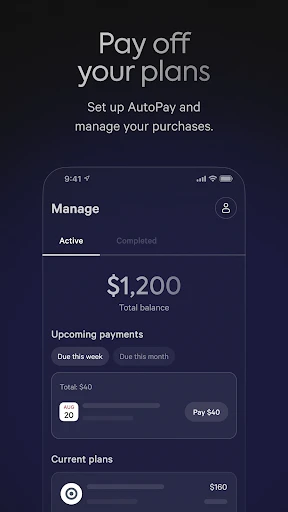
My second habit is to keep a simple personal list of active purchases. I record the item, the remaining balance, and the upcoming payment dates in whatever budgeting method I already use. I do not rely on memory, especially when purchases happen across different retailers. This turns Affirm from a passive checkout option into something I actively monitor.
Third, I ask whether the item will still be useful after the final payment. That question sounds obvious, but it is a good test for clothing, electronics, and seasonal purchases. If the answer is uncertain, waiting is usually better than borrowing flexibility for something that may quickly lose its appeal.
Finally, I read the details each time. I do not assume that a plan available for one purchase will have identical conditions for another. The product, retailer, order amount, and timing can all affect the decision. A familiar app can make me feel comfortable, but familiarity is not a substitute for reviewing the specific arrangement in front of me.
Who should use it, and who should skip it
Affirm is a good fit for a shopper who has a clear purchase in mind, understands their monthly budget, and wants to compare a structured payment option with paying immediately. It can be particularly useful for an essential expense that arrives before the shopper’s cash flow catches up, provided the future payments remain comfortable even after ordinary bills are counted.
It may also suit someone who prefers to keep a larger purchase separate from everyday card spending. Reviewing that commitment on its own can make the expense easier to evaluate, especially when the shopper keeps personal records and checks the schedule regularly.
I would advise skipping it if the purchase is mainly driven by urgency, social pressure, or a limited-time feeling. I would also avoid it if I am already juggling several installment commitments, regularly miss due dates, or need a new plan to cover basic living costs. In those situations, the flexibility can hide the real problem rather than solve it.
Someone who wants the simplest possible transaction should probably pay in full when possible. A person who is primarily seeking card rewards, a particular purchase protection, or one familiar account may also prefer their existing card after comparing the terms. Affirm is not better merely because it is modern or convenient; it is better only when its structure matches the purchase and the budget.
Device support and the current app experience
Affirm was released on June 20, 2016, and the current version is 3.402.1. It supports Android 7.0 and later, so people using older devices should check compatibility before planning around it. The free price makes trying the app straightforward, although the real financial question is always the cost and conditions of the purchase rather than the cost of installing the app.
I like that the app presents itself as a shopping aid instead of pretending that every purchase should be financed. The experience works best when I use it briefly and deliberately: identify the item, inspect the payment details, compare alternatives, and either proceed or walk away. Browsing without a specific purpose makes it easier to confuse a saving opportunity with a reason to buy.
The large number of ratings and the strong average rating indicate that many people find the experience useful, but I would treat that as a sign of broad appeal rather than a guarantee that every plan will suit me. Financial products are personal. The same payment schedule can be manageable for one household and stressful for another, so my own budget remains more important than the app’s popularity.
My final recommendation
After using Affirm as a shopping and payment-planning tool, I see a clear strength and a clear boundary. Its strength is giving me another way to think about a planned purchase, especially when I want to spread the impact across future paydays and compare the arrangement carefully. Its boundary is that flexibility can encourage spending beyond what I would choose if I looked at the full cost first.
I recommend it to disciplined shoppers who check the complete commitment, track their active plans, and use it for a defined purpose. I would not recommend it as a rescue button for an unaffordable lifestyle or as a way to make impulse purchases feel harmless. For me, the best experience comes from deciding the budget first and opening the app second.
My verdict is favorable, with a firm condition: use Affirm to organize a purchase you can already afford, not to convince yourself that you can afford one. If that mindset fits you, the app can be a useful addition to your shopping routine. If you want maximum simplicity or already feel stretched by existing bills, paying in full, waiting, or choosing a less expensive option is the wiser path.
Pros
- Flexible payment plans.
- No hidden fees or surprises.
- Quick and easy approval process.
- Transparent terms and conditions.
- Boosts purchasing power.
Cons
- Limited to partner merchants.
- May affect credit score.
- Interest rates can be high.
- Not available outside the US.
- Requires credit check.
Frequently Asked Questions
What is Affirm and how does it work?
Affirm is a financial service that allows users to make purchases and pay for them over time through installment plans. When you choose Affirm at checkout, you can opt for a payment plan that suits your budget, often with no hidden fees. Affirm pre-qualifies you for the amount you can spend, and once approved, you can complete your purchase and manage payments through their app.
Are there any interest or fees associated with Affirm?
Affirm offers transparent payment plans, and in many cases, you can qualify for 0% interest financing. However, interest rates can vary between 0% and 30% depending on your creditworthiness and the retailer. Affirm does not charge late fees, service fees, or prepayment penalties, making it a straightforward option for financing purchases.
How does Affirm affect my credit score?
Affirm performs a soft credit check when you apply, which does not impact your credit score. However, the company may report your payment history to credit bureaus, so timely payments can positively affect your credit score while missed payments might have a negative impact. It's essential to stay up-to-date with payments to maintain a good credit standing.
What are the eligibility requirements to use Affirm?
To use Affirm, you must be at least 18 years old (or 19 in Alabama or if you're a ward of the state in Nebraska), have a valid U.S. or APO/FPO/DPO home address, a social security number, and an active phone number. Eligibility also depends on your credit history and the retailer's terms. Affirm's pre-qualification doesn't guarantee approval for a purchase.
Is Affirm available for all types of purchases?
Affirm is available with a wide range of participating retailers, including those in fashion, electronics, home goods, travel, and more. However, not every retailer partners with Affirm, so it's important to check if the option is available at the point of checkout. Affirm continuously expands its network, making it easier for consumers to use their service for various purchases.