Afterpay: Pay over time
- Rating
- 4.0
- Downloads
- 10,000,000+
- Age
- Everyone
Additional Info
- App Name
- Afterpay: Pay over time
- Category
- Shopping
- Package Name
- com.afterpaymobile.us
- Developer
- Afterpay
- Rating
- 4.0
- Version
- 1.128.0
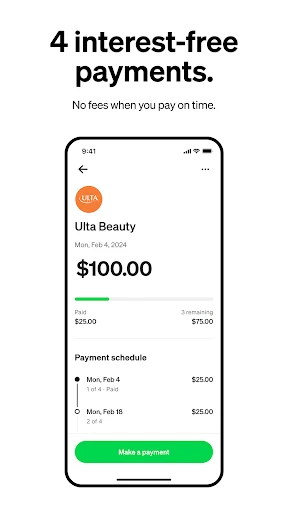
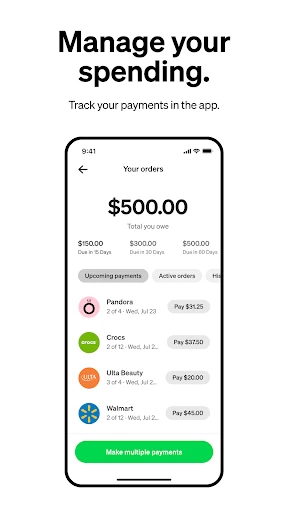
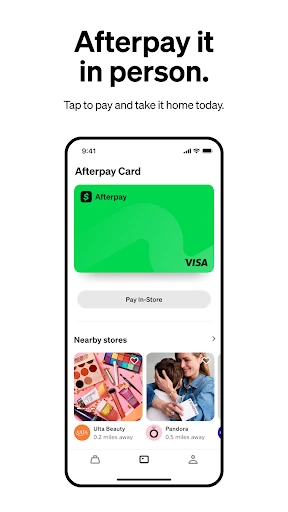
 Analysis by Appcrazy
Buy-now-pay-later apps can look simple until a payment does not go through, an order does not appear, or the amount available for a purchase changes unexpectedly. After using Afterpay: Pay over time, I found that its value is less about browsing and more about keeping a planned purchase organized across scheduled payments. It is a free shopping app from Afterpay, aimed at people who want to divide eligible purchases into manageable payments instead of paying the full amount immediately.
My overall impression is positive, but not carefree. The app can make a planned purchase easier to budget, especially when I already know what I need and have enough money reserved for the upcoming payments. It becomes a poor fit when the payment schedule is treated as extra spending power. That distinction matters more here than the polished interface or the convenience of checking an order from a phone.
With an average rating of 4.0 from around 167 thousand ratings, the app has clearly reached a large audience. It has over 10 million installs, carries an Everyone age classification, and requires Android 7.0 or later. Those figures suggest broad accessibility, but they do not remove the need to read each payment screen carefully before confirming a purchase.
Where the experience usually gets stuck
I look at the moments when a checkout feels uncertain, because that is where a payment app can become frustrating even if the underlying purchase is straightforward. This section focuses on separating a delayed update from a genuine failure and on checking the retailer’s order record before taking another step. That distinction sets up the preparation that can prevent avoidable snags.
The first problem is often expectation, not the app
Many people open a pay-over-time service expecting it to work exactly like a normal card at every shop. That is not how I would approach Afterpay. The important question is not simply whether I can afford the first payment. I also need to be comfortable with the remaining scheduled payments and with the possibility that an order, refund, or authorization may take time to settle.
This is the first practical insight: the app is best used as a payment-planning tool, not as a way to stretch an uncertain budget. Before I confirm anything, I check the full purchase amount, the first amount due, the later dates shown in the checkout flow, and the account balance that will be available when those payments arrive. That small pause prevents the most common kind of frustration: discovering that a convenient first installment was easier than the total commitment.
A second sticking point is the difference between a purchase being accepted and the order being fully visible in the app. If I move quickly between a retailer’s checkout and Afterpay, I do not assume that a delayed screen means the transaction failed. I first check whether the retailer shows an order confirmation, then return to the app and review the relevant activity. Repeating the purchase immediately can create confusion or duplicate pending attempts.
Catch Up on the Latest Stories
Microsoft Teams on Mobile Keeps Work Moving, If You Keep It Tidy
Groupon Turns Local Discounts Into a Marketplace, With a Catch
App of the Week: Yandex Go Makes City Errands Easier
Make Xiaomi Weather Work Harder with Smarter Settings and Daily Routines
Boomplay Turns Music Streaming Into a Daily Discovery Habit
Google Docs on Mobile Keeps the Page in Focus, Until Formatting Gets in the Way
Why an apparently declined purchase can be confusing
A declined attempt does not always tell me exactly what needs changing. It may be related to the purchase details, the account information, the payment method, or the retailer’s checkout session. The useful response is to slow down and identify which stage failed rather than trying the same button repeatedly.
I start by checking whether the basket total changed, whether shipping or billing details were edited, and whether the payment method still works for ordinary transactions. I also make sure the app is showing the account I intended to use. These checks are simple, but they are more productive than assuming the service is broken.
Another source of friction is timing. A payment can be authorized before a retailer’s page finishes loading, while a retailer can also hold an order before the app displays the final status. I treat these as separate systems that need a moment to catch up. Taking screenshots of the confirmation or noting the order reference is useful when I later need to match a retailer record with the payment activity.
Refunds and returns need patience and matching records
Returns are another area where users can draw the wrong conclusion too quickly. A retailer may accept a return before the corresponding payment schedule changes. I keep the retailer’s return confirmation, the order details, and the Afterpay activity together until the adjustment is visible. If I only look at one screen, it is easy to believe that nothing happened.
This is where the app is helpful but not all-powerful. It can show the payment side of the arrangement, while the retailer controls whether an item was received, approved, or refunded. I contact the retailer first when the return itself is in question. I look to Afterpay when the retailer has confirmed the refund but the payment record still needs to reflect it.
Setup checks that prevent avoidable trouble
Before opening a checkout, I find it useful to make sure the account details and payment method are ready, then understand where I will verify the result. A little preparation is especially valuable when the retailer and payment app show different stages of the same transaction. Next, I’ll cover a calm sequence for narrowing down which part needs attention.
Install expectations and account preparation
The current Android version is 1.128.0, and the app supports Android 7.0 and newer. I would check the phone’s operating system before troubleshooting anything else. If the device is older, updating the app alone may not solve installation or opening problems. I also leave enough free storage for an update and use a stable connection during installation or account verification.
Because Afterpay handles shopping and payment activity, I use an account email and phone number that I can access reliably. A temporary email address or an old phone number can turn a routine sign-in into a recovery problem. I also make sure the spelling of my personal and billing details matches the information used during checkout. Small differences in names or addresses can create unnecessary verification friction.
I do not begin with a large purchase while learning the app. A better workflow is to open the account, inspect the available screens, review how upcoming payments are displayed, and understand where order activity appears. This gives me a reference point before I need the app under pressure at a retailer’s checkout.
Check the payment method before blaming checkout
When a payment attempt fails, I verify the underlying card or account outside the app where possible. The card may be expired, temporarily locked, out of funds, or restricted from a particular type of transaction. A payment method can work in one context and fail in another, so I do not treat a successful coffee purchase as proof that every online payment will work.
I also check whether the bank has sent a security alert or requires confirmation. A bank-side block can look like an Afterpay problem because the failure appears during the same checkout. If the payment method is declined elsewhere too, changing screens inside the app will not fix the cause.
Another useful habit is avoiding multiple rapid edits. If I change the payment method, address, basket, and retailer session all at once, I lose track of what solved the problem. I change one thing, retry once, and then review the result. This is slower than tapping repeatedly, but it produces a much clearer diagnosis.
Understand the difference between app access and purchase eligibility
Being able to open the app does not guarantee that every purchase will be accepted. The app can be functioning normally while a particular transaction is not approved. I therefore separate three questions: can I sign in, can I view my existing activity, and can this new purchase be completed?
That distinction also answers a common concern: an account that looks normal may still show a different result at checkout. I do not interpret that automatically as a lost account or a defective installation. I review the purchase amount, retailer details, payment method, and any message shown at the time. If existing activity loads correctly, the problem is more likely tied to the attempted purchase than to basic app access.
Recovering a workflow when something goes wrong
When a purchase, payment, or sign-in does not behave as expected, I avoid repeating the action until I know what the first attempt did. I compare the app’s activity with the retailer’s confirmation and keep a short record of the time and amount, which makes follow-up clearer. The next section turns to cases where those checks point outside the app itself.
When an order is missing from the app
If I finish checkout but cannot immediately see the order, I first confirm whether the retailer issued an order number or confirmation message. I then close and reopen the app, check the account details, and look through the relevant activity rather than starting another order. A missing display entry is not enough evidence that the purchase should be repeated.
If the retailer has no order record and the payment attempt also appears incomplete, I wait briefly before trying again. The goal is to avoid turning one uncertain attempt into two. If a pending amount appears at the bank, I record its date and value and keep the retailer confirmation, if any. Those details make later support conversations much easier.
When a payment appears twice
Duplicate-looking entries deserve careful comparison. I check whether one is a pending authorization and the other is the completed payment schedule, rather than assuming two final charges exist. I compare the retailer order number, timestamps, and amounts. I do not cancel or retry a payment solely because two lines appear on the first screen I open.
This is one of the less obvious advantages of reviewing the whole activity trail: the sequence often explains more than a single balance. A pending entry, a completed order, and a later adjustment can look alarming when viewed separately. Keeping the records together helps me distinguish a temporary status from a genuine duplicate.
What I do after an update or sign-in problem
If the app stops opening or behaves strangely after an update, I start with ordinary checks: restart the phone, confirm the connection, install any available app update, and try again later if the service appears temporarily unavailable. I avoid deleting the app as a first step because reinstalling can add another sign-in hurdle without addressing a server-side or account issue.
If I do reinstall, I make sure I know the correct account details before removing anything. I also avoid creating a second account simply because the first login fails. Multiple accounts can make order history and payment activity harder to identify. Recovering the original account is usually the cleaner route.
How to contact support with useful information
When self-checks do not solve the issue, I prepare a concise timeline: when I attempted the purchase, which retailer was involved, whether the retailer supplied an order number, what the app displayed, and whether my bank showed a pending or completed amount. I do not send unnecessary card details. A clear timeline is safer and more useful than a long description saying only that the app failed.
I also keep retailer support and Afterpay support separate. The retailer is the right first contact for missing goods, incorrect products, shipping, or a return that has not been accepted. Afterpay is the more relevant contact for account activity, payment scheduling, or an adjustment that has not appeared after the retailer confirms its side.
When the app is not the cause
A confusing checkout is not always caused by the payment app: a retailer’s order flow, a bank’s security checks, or an unstable connection can produce similar symptoms. I separate those possibilities before changing account settings or retrying, so I do not create extra uncertainty while trying to fix the wrong thing. The final section considers how to recognize those outside causes.
Retailer checkout issues can look identical
Sometimes the payment service is blamed because its name appears at the final step, even though the retailer’s basket or checkout page is the part that failed. I test the retailer’s site or app separately, confirm that the item is still in stock, and check whether shipping information is complete. If the retailer cannot create an order, changing settings in Afterpay is unlikely to help.
Similarly, a retailer may show an order as pending while the payment arrangement is already visible. I do not treat those two labels as interchangeable. I use the retailer’s order page to understand fulfillment and the Afterpay app to understand the payment record.
Bank controls and network conditions matter
A weak connection can interrupt a redirect between the retailer and the app. I switch to a reliable network, avoid submitting the same checkout repeatedly, and check the account activity afterward. If the bank has blocked the transaction, I resolve that with the bank rather than repeatedly reinstalling Afterpay.
These checks are especially important when a purchase is time-sensitive. A limited-stock item can encourage rushed retries, but rushed retries are exactly when duplicate authorizations and unclear order status become more likely. I would rather lose a purchase than create several unresolved payment attempts.
When a different payment option is better
Afterpay is not my first choice for every purchase. I prefer paying directly when I already have the full amount available and want the simplest possible refund path. A debit or credit card can also be more practical when I need a payment method accepted broadly without checking whether a particular retailer and transaction qualify.
I would skip a pay-over-time arrangement for essentials that I cannot comfortably cover later, for impulse purchases, or when several existing schedules are already active. The app may make the first payment feel small, but the household budget still carries the full obligation. In those situations, saving first or using a conventional payment method is the safer choice.
Who benefits most from it
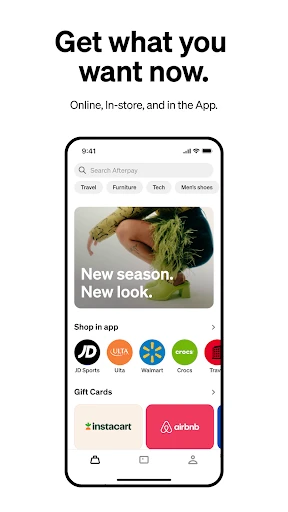
I see the strongest use case in a planned purchase where the total is already accounted for, but spreading payments helps align the expense with a predictable budget. For example, if I need a replacement household item after payday but want to keep cash available for known bills, I can review the schedule, set aside the later amounts, and monitor the activity from the app. The benefit comes from organization, not from spending beyond my means.
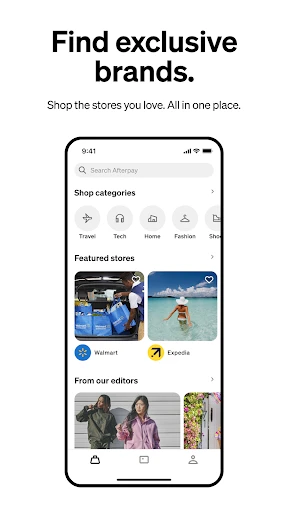
It can also suit shoppers who want one place to review eligible purchases and upcoming payment activity instead of relying on memory or scattered retailer emails. That convenience is real, but it works only when I check the app regularly and keep enough money available for each scheduled payment.
My practical verdict after using it
Afterpay: Pay over time is a useful shopping companion when I treat it as a structured payment schedule rather than a shortcut around affordability. The free price makes it easy to try, and the Everyone rating makes its audience broad. Its scale is reflected in roughly 70 thousand written reviews and a 4.0 average, while the current release, version 1.128.0, keeps it relevant for supported Android devices.
My recommendation comes with a clear condition: read the schedule before confirming, keep retailer and payment records together, and troubleshoot one layer at a time. If an order is missing, do not immediately repeat it. If a payment fails, check the payment method and retailer session before assuming the app is at fault. If a return is pending, follow the retailer’s confirmation through to the payment activity.
The app is a good match for a careful shopper who wants visibility over planned installments and is willing to manage them actively. It is not the right choice for someone looking for unrestricted credit, maximum simplicity, or a way to make an unaffordable purchase feel harmless. Used with that boundary in mind, I find it practical and approachable. Used without it, the convenience can hide the very budget pressure the app is supposed to help organize.
Pros
- Flexible payment plans.
- No interest fees.
- Easy-to-use interface.
- Wide acceptance at retailers.
- Real-time purchase notifications.
Cons
- Late fees apply.
- Requires credit check.
- Limited to partnered stores.
- Potential for overspending.
- Customer service can be slow.
Frequently Asked Questions
What is Afterpay and how does it work?
Afterpay is a 'buy now, pay later' service that allows you to purchase items immediately and pay for them in four equal installments every two weeks. This is interest-free, provided you make your payments on time, making it a flexible option for managing your budget. It's available at various retailers and can be used both online and in-store.
Is there a credit check required to use Afterpay?
No, Afterpay does not require a credit check when you sign up. This makes it accessible to a wider range of users who may be concerned about their credit score. However, it's important to note that your payment history with Afterpay can influence your ability to use the service in the future.
Are there any fees associated with using Afterpay?
Afterpay itself does not charge any interest. However, if you miss a payment, there may be late fees incurred. These fees can vary, so it's crucial to manage your payments responsibly. Additionally, some retailers may have their own fees or terms when using Afterpay, so be sure to check these details before making a purchase.
How do I sign up and start using Afterpay?
Signing up for Afterpay is straightforward. You can download the Afterpay app from the App Store or Google Play and create an account by providing some basic information. Once your account is set up, you can start shopping at participating retailers. When you check out, select Afterpay as your payment method to split your purchase into four interest-free installments.
What happens if I miss a payment with Afterpay?
If you miss a payment with Afterpay, you may incur late fees and your account could be paused until the balance is paid. It's important to keep track of your payment schedule to avoid these penalties. Afterpay sends reminders and notifications to help you stay on top of your payments, ensuring a smooth experience without any additional costs.