Amex
- Rating
- 3.6
- Downloads
- 10,000,000+
- Age
- Everyone
Additional Info
- App Name
- Amex
- Category
- Finance
- Package Name
- com.americanexpress.android.acctsvcs.us
- Developer
- American Express
- Rating
- 3.6
- Version
- 7.25.0
 Analysis by Appcrazy
Managing a credit card from a phone is convenient, but convenience only matters when I can see what is happening and take action without confusion. That is the main reason I spent time with Amex, the finance app from American Express. It puts account access, payments, rewards, and everyday card management into one mobile space rather than making me rely on a browser.
My overall impression is practical rather than flashy. This is an account-management tool first, not a budgeting coach or a general banking replacement. If you already use an American Express account, the app can make routine tasks easier to reach. If you want one application to combine cards from several providers, analyze every household expense, or replace a full bank account, its usefulness is more limited.
What the app is really for
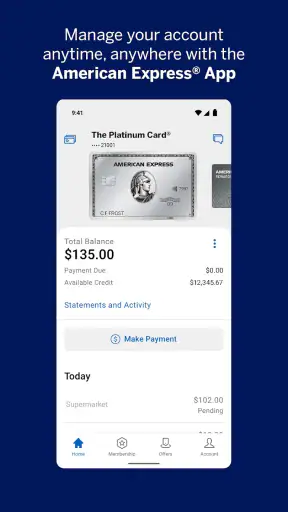
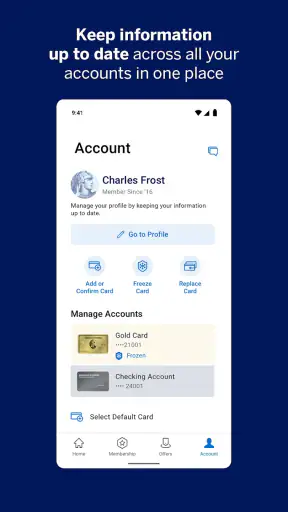
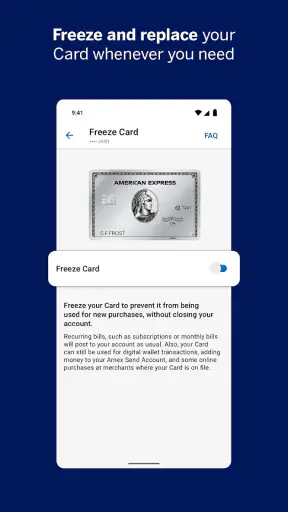
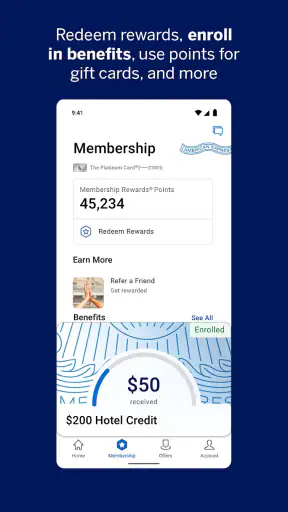
The app belongs firmly in the finance category, and its purpose is easy to understand: it gives Amex customers a mobile way to view their balance, make payments, redeem rewards, and handle other account tasks. I found that focus helpful because the interface does not need to pretend to be a complete financial planner. It is built around the moments when a cardholder wants a quick answer or needs to complete an account action.
American Express has maintained the app since its release on December 2, 2010, and the current version is 7.25.0. It is free to download, carries an Everyone content rating, and requires an operating system version of 12 or newer. Those details matter in practical terms: the app is accessible to a broad audience, but someone using an older phone may need to check compatibility before planning to rely on it.
The scale of adoption is also notable. The app has passed 10 million installs, while its average rating is 3.6 from around 44 thousand ratings. I would read that combination carefully. It suggests that many people use it regularly, but the rating also tells me not to expect every device, account situation, or update experience to feel equally smooth. A finance app should be judged by how reliably it handles important tasks, not only by how polished its screenshots look.
Trust starts with the account boundary
My first trust question with a financial app is simple: does it stay focused on the account I expect to manage? Here, the developer is clearly identified as American Express, and the app is designed around Amex account access. That narrow purpose is reassuring in one sense because I am not being asked to hand one unrelated service control over a collection of financial products just to see a card balance.
At the same time, the narrow focus is a real trade-off. The app is most useful to existing American Express customers. Someone with cards from several issuers may still need separate apps or a third-party money manager. I prefer this focused approach for sensitive actions such as payments, but I would not choose it as my only financial overview if my spending is spread across multiple providers.
Catch Up on the Latest Stories
Microsoft Teams on Mobile Keeps Work Moving, If You Keep It Tidy
Groupon Turns Local Discounts Into a Marketplace, With a Catch
App of the Week: Yandex Go Makes City Errands Easier
Make Xiaomi Weather Work Harder with Smarter Settings and Daily Routines
Boomplay Turns Music Streaming Into a Daily Discovery Habit
Google Docs on Mobile Keeps the Page in Focus, Until Formatting Gets in the Way
I also appreciate that the main account jobs are visible in the product’s purpose. Checking a balance, paying a bill, and using rewards are not hidden behind an elaborate personal-finance system. That makes the app easier to explain to a family member who does not want to learn a complicated dashboard. The important caution is that a simple entry point does not remove the need to review details before confirming a payment or redemption.
Controls I would check before using it regularly
For a finance app, the useful question is not only whether I can open an account screen, but whether I can make deliberate choices before an action becomes final. When I use a mobile card app, I look for the amount, destination, timing, and confirmation state before submitting anything. I also want to know whether I am viewing the current balance or a different figure connected to a statement or payment cycle.
That habit is especially important with Amex because a balance screen and a payment screen serve different purposes. A quick glance can tell me what the account shows, but it should not replace reading the payment details. I would slow down when choosing how much to pay, particularly if I am deciding between a minimum amount, a statement amount, or a larger custom payment. The app supports payments, but the responsibility for selecting the right amount remains mine.
Rewards deserve the same care. Redeeming points or other rewards can feel less urgent than paying a bill, yet redemption is still an account decision. I would review the available choice, the amount being used, and the result shown before confirming. A useful workflow is to check the account first, deal with any payment task separately, and only then move to rewards. Keeping those actions distinct reduces the chance of tapping through a familiar screen too quickly.
My strongest practical tip is to treat every confirmation screen as a checkpoint, not a formality. A fast fingerprint or device sign-in can make access convenient, but speed can also encourage automatic tapping. I would verify the account context and transaction details every time the app asks me to approve a payment or redemption, especially when using a shared environment or a phone I have recently changed.
Where privacy and data awareness matter most
A card-management app naturally deals with sensitive financial activity. That means I would be more careful here than with a weather or recipe app, even when the app’s basic task seems simple. Opening the balance is one type of interaction; submitting a payment or redeeming rewards has a more direct effect on my account. I would avoid doing those actions casually while distracted, and I would make sure the phone itself is protected with a passcode or another lock method I trust.
I would also pay attention to the choices presented during sign-in, account recovery, and account changes. If the app asks me to confirm identity or review account information, I would read the prompt instead of treating it as an obstacle. This is not about assuming a problem; it is about recognizing that financial security depends on user decisions as much as on the application’s interface.
Notifications are another data-sensitive moment. A notification that reveals too much account information on a locked screen can be inconvenient in a shared home, workplace, or public setting. I would review the phone’s notification settings and choose a level of detail that fits my circumstances. The best setting is not necessarily the most informative one; it is the one that lets me notice important activity without displaying private details to anyone who happens to see the screen.
When I install or update a finance app, I also look at the permissions and system prompts shown by my device rather than approving everything automatically. The app’s purpose does not give me a reason to ignore those prompts. If a request seems unrelated to viewing an account or managing a card, I would pause and decide whether I actually need the related function. That approach gives me a clearer sense of control without making claims about permissions that are not visible to me in the same way on every device.
A realistic everyday payment routine
Imagine I am preparing for a weekend trip and want to make sure my card account is in order. I open the app to check the balance, review the payment area, and confirm that I am looking at the intended account before submitting anything. If I have rewards to use, I handle that as a separate step rather than mixing it into the payment decision. This sequence is less about saving seconds and more about preventing two unrelated actions from becoming one rushed habit.
Later, if I notice an unexpected figure or an account detail I do not recognize, I would stop rather than repeatedly refreshing the screen or trying random options. A mobile app is useful for presenting account information and available controls, but a confusing or disputed situation may require the issuer’s formal support route. The app should be my first place to inspect the account, not my excuse to guess at the meaning of a transaction.
This is where a focused card app can be better than a general expense tracker. A third-party tracker may show a broader picture across accounts, but an issuer’s own app is the more natural place for an Amex card payment or reward action. The reverse is also true: a general tracker is more convenient when I want to compare spending across different banks and cards. Neither tool completely replaces the other.
Who will get the most from it
I think the app is a good fit for an American Express cardholder who wants mobile access to the essentials without opening a desktop browser. It should appeal to people who check their balance while away from home, make payments from a phone, or prefer to review rewards in the same place as account information. It is also a sensible option for users who value a direct relationship with the card issuer rather than connecting their financial details to an unrelated aggregation service.
The app may be particularly useful for someone who travels or makes purchases away from a computer, because account access is available in the setting where the spending happens. I would still avoid making important decisions on a weak or unfamiliar connection, and I would not assume that a phone interface makes a financial action risk-free. Convenience is valuable, but deliberate review remains part of responsible use.
It is less suitable for a person who wants detailed household budgeting, shared expense planning, investment tracking, or a single dashboard covering every financial institution. The app’s identity is tied to American Express account management. Choosing it for those broader jobs would leave gaps that a dedicated budgeting tool or a bank app with wider account coverage might handle better.
Where the experience can feel limited
The 3.6 average rating is a useful reminder to keep expectations realistic. I would not interpret the app as universally poor, especially given its large install base, but I would expect that some users encounter friction related to device compatibility, account access, updates, or individual workflows. A finance app can be valuable even when it is not perfect, yet reliability matters more here than it would in a casual app.
The minimum operating system requirement of 12 is another practical limitation. Owners of older devices should check whether their phone can run the current release before depending on it for payments. If the phone is no longer receiving security updates, I would be even more cautious about using it for financial management, regardless of whether the app itself can be installed.
There is also a mental limitation: a balance display can encourage me to think I understand my whole financial position when I am only looking at one card. I would not use this app as a substitute for reviewing other accounts, upcoming obligations, or a complete monthly budget. Its strength is direct card control, not a complete picture of personal finances.
How I would use the app safely and efficiently
I would begin by signing in only on my own protected device and then spend a few minutes learning where the balance, payment, and rewards areas are located. Familiarity is useful because it reduces frantic searching when I am away from home. However, I would not let that familiarity turn into blind confirmation. The most important details deserve a fresh look each time.
For payments, I would use a short personal checklist: confirm the account, read the amount, check the timing or payment context shown, and save any confirmation information that the app presents. I would then revisit the account later if the payment is important or time-sensitive. This is a simple workflow, but it is more dependable than assuming that a tap automatically means the account has reached the result I intended.
For rewards, I would decide what I want before opening the redemption flow. That prevents me from choosing an option merely because it appears first or because I am in a hurry. I would also keep payment management and rewards management mentally separate. One concerns meeting an account obligation; the other concerns using an available benefit. Treating them as different decisions makes the app easier to use responsibly.
Finally, I would review notification visibility, device security, and sign-in behavior after changing phones or updating the operating system. These checks are easy to overlook because the app may still open normally. In my view, user agency is strongest when I know which device is being used, what appears on the lock screen, and what I am approving before the app completes an account action.
My cautious verdict
Amex is a focused, free finance app that makes sense for people who already manage an American Express account and want essential card controls close at hand. Its value comes from direct access to balance information, payments, rewards, and related account tasks, not from trying to become an all-purpose money manager. I like that clear boundary because it makes the app easier to understand and easier to recommend for the right person.
I would recommend it to an Amex customer who uses a compatible phone and wants a convenient mobile route for routine account management. I would not recommend relying on it alone for a multi-bank financial picture, detailed budgeting, or every kind of account support. In those situations, a broader finance tool or a direct support channel may be a better companion.
The final decision comes down to how much you value issuer-specific control. With over 10 million installs and a long history, the app is clearly established, but its 3.6 average means I would approach it with sensible expectations rather than assuming a flawless experience. Used thoughtfully—especially by checking payment and redemption details, reviewing notification privacy, and keeping the phone secure—it can be a useful everyday tool. For me, that makes it worth trying when American Express is already part of my financial routine, while keeping a separate budgeting method for everything the app is not designed to do.
Pros
- User-friendly interface
- Comprehensive reward options
- Strong security features
- Wide acceptance globally
- 24/7 customer support
Cons
- High annual fees
- Limited merchant acceptance
- Complex rewards system
- Not ideal for international travel
- Occasional app glitches
Frequently Asked Questions
What is the American Express (Amex) mobile app used for?
The Amex mobile app is designed to help American Express cardholders manage their accounts conveniently from their smartphones. Users can view recent transactions, monitor account activity, pay bills, and even check their Membership Rewards points balance. Additionally, the app provides personalized offers, fraud alerts, and a secure platform for managing financial information.
Is the American Express mobile app secure?
Yes, the Amex mobile app is secure and incorporates advanced security features to protect users' personal and financial information. These include multi-factor authentication, secure login with biometrics like fingerprint or facial recognition, and encryption of sensitive data. Amex also offers fraud alerts and notifications for unusual activities to ensure users' accounts remain safe.
Can I use the Amex app to make payments and transfer funds?
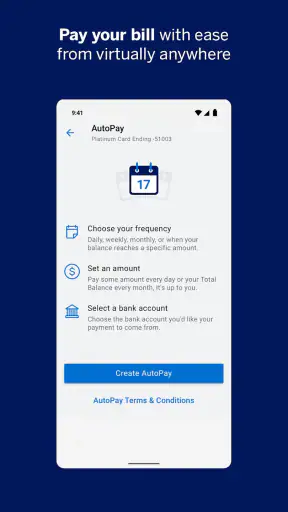
Yes, the Amex app allows you to make payments towards your Amex card balance directly from your bank account. Additionally, you can set up auto-pay to ensure timely payments. However, the app itself does not support direct money transfers to other bank accounts; it is primarily focused on managing your Amex card account and related transactions.
Does the Amex app offer customer support options?
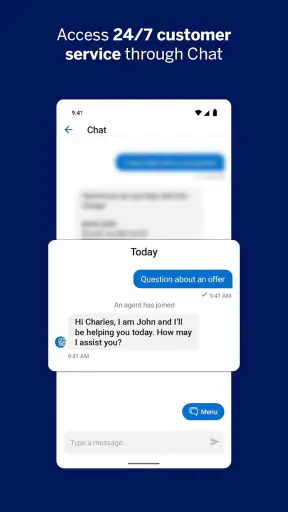
The American Express mobile app provides several customer support options, including a direct in-app messaging feature where users can chat with customer service representatives. Additionally, the app offers quick access to contact numbers for immediate assistance and a comprehensive FAQ section to help users find answers to common questions and issues.
How do I download and set up the Amex app?
To download the American Express app, visit the Google Play Store for Android devices or the Apple App Store for iOS devices and search for 'Amex'. Once installed, open the app and follow the on-screen instructions to log in using your Amex account credentials. If you're a new user, you'll need to register your card and create an account before you can fully access the app's features.