Barclays US
- Rating
- 4.7
- Downloads
- 1,000,000+
- Age
- Everyone
Additional Info
- App Name
- Barclays US
- Category
- Finance
- Package Name
- com.barclaycardus
- Developer
- Barclays US
- Rating
- 4.7
- Version
- 8.5.7
 Analysis by Appcrazy
Choosing a banking app is less about finding the flashiest interface and more about deciding which everyday money tasks you want to handle from your phone. I spent time with Barclays US as a finance app, and my impression is straightforward: it is most useful when you already use Barclays US and want a practical mobile route into that relationship. It does not try to be a general-purpose budgeting platform or a marketplace for every financial product. Its value comes from keeping banking access close at hand.
The app is free to download, carries an Everyone age rating, and is developed by Barclays US. That combination makes it easy to consider for ordinary personal banking, but the real decision depends on your habits. Do you want a mobile companion to an existing Barclays account, or are you searching for an app that brings together accounts from different institutions, detailed spending analysis, or broader financial planning? Those are different needs, and choosing well means separating them before you move your routine.
What I looked for before recommending it
My first test was convenience. A finance app earns its place when it reduces small points of friction: checking whether a payment has cleared, reviewing available money before a purchase, or dealing with an account while away from a computer. Barclays US makes sense in that context because its purpose is tied to Barclays customers rather than to being a neutral dashboard for every bank.
My second test was confidence. Banking on a phone should feel controlled, not rushed. I paid attention to whether the app encouraged a quick glance followed by a sensible decision, rather than making money management feel like browsing a shopping app. The store summary presents it as safe, convenient, and rewarding, but I would treat those words as a starting point rather than a complete evaluation. The important question is whether the app fits the way you already manage your Barclays relationship.
The third test was switching effort. If you are already a Barclays US customer, installing the app is a relatively contained change: you are adding a mobile access point to something familiar. If you are not a customer, the decision is larger because an app alone is not a replacement for choosing an institution. That distinction is easy to overlook when comparing icons in an app store.
There is also a useful difference between popularity and suitability. Barclays US has an average rating of 4.7 from roughly 47 thousand ratings, with about 6.5 thousand written reviews, and it has passed one million installs. Those figures show that many people have chosen to use it, but they do not tell me that it is ideal for every banking style. A high rating can support confidence in the general experience while still leaving room for individual frustrations.
The everyday moments where it makes the most sense
I see the strongest use case in short, repeated sessions. Imagine standing at a grocery checkout and wanting to confirm that a recent payment has not reduced your available money more than expected. A mobile banking app is valuable there because you need an answer, not a full financial planning session. The same applies when checking an account before moving money, reviewing recent activity after a purchase, or handling a banking task while travelling.
Catch Up on the Latest Stories
Microsoft Teams on Mobile Keeps Work Moving, If You Keep It Tidy
Groupon Turns Local Discounts Into a Marketplace, With a Catch
App of the Week: Yandex Go Makes City Errands Easier
Make Xiaomi Weather Work Harder with Smarter Settings and Daily Routines
Boomplay Turns Music Streaming Into a Daily Discovery Habit
Google Docs on Mobile Keeps the Page in Focus, Until Formatting Gets in the Way
My practical advice is to use it as a “check before acting” tool. Before making a large payment, glance at recent activity and the available balance. After an unfamiliar transaction appears, review it promptly instead of waiting for a monthly statement. This habit does not turn the app into a complete budget, but it can make your daily decisions less dependent on memory.
A less obvious benefit is the reduction of mental switching. If your main account is with Barclays US, using its own app keeps the account view and the banking relationship in the same place. You do not need to maintain a separate mental map of which third-party service reflects which institution. That simplicity matters most for people who prefer a clear banking routine over a collection of financial tools.
How the app fits into a broader money routine
I would not rely on a banking app alone to answer every financial question. The app can be the place where I verify what is happening in an account, while a separate note, spreadsheet, or budgeting method can explain why it is happening. That division is healthy. A current balance is not the same thing as a spending plan, and recent transactions are not automatically a forecast of the month ahead.
One useful workflow is to create a small weekly review. I would open Barclays US, scan recent activity, identify anything I do not recognize, and then compare the result with my own upcoming commitments. The point is not to stare at the balance every day. It is to use the app as a reliable checkpoint, especially before recurring bills or larger discretionary purchases.
Another practical tip is to avoid making the app your only record of important financial information. For major payments or account changes, I prefer keeping a personal note of the date and purpose. That gives me context later and prevents a mobile transaction list from becoming my entire financial history. The app is better at showing current account activity than at replacing personal organization.
Where Barclays US wins, and where another category may fit better
I’d use this section to weigh the app’s direct connection to Barclays US against the wider view a budgeting or multi-bank tool can offer. The right choice depends less on a feature checklist than on whether your recurring task is checking one banking relationship or understanding money across several. That distinction also makes it easier to judge whether the app will keep earning a place in your routine.
Its clearest advantage is relationship-based access
The main strength here is focus. Barclays US is not presented as an independent budgeting service that asks you to gather information from several banks. It is a direct mobile channel for Barclays US customers. That can be a better fit than a general finance aggregator when your priority is checking and managing the relationship you already have.
I also like the psychological simplicity of using an institution’s own app. When I want to verify an account, I would rather begin with the source connected to that account than depend on a separate service that may organize the information differently. This does not mean an aggregator is bad; it means the two tools solve different problems. One centers on direct banking access, while the other centers on a combined financial picture.
The app’s long presence also matters in a modest way. It was released on February 16, 2012, so it is not a newly appearing banking product that has yet to establish a history of use. Its current version is 8.5.7, and it requires an operating system version of 12 or later. That requirement is reasonable for people with a modern device, but it is still worth checking before planning a switch, especially if you keep an older phone for financial tasks.
Another advantage is cost at the app level: there is no download charge. That makes trying the mobile experience a low-risk step for an existing Barclays customer. I would still separate the free app from the terms of any banking products connected to it. “Free” here describes the app download, not every possible cost associated with an account or transaction.
Why a budgeting app may be better for some readers
If your central question is “Where did all my money go this month?”, Barclays US may not be the best category of tool by itself. A dedicated budgeting app is usually designed around classification, targets, trends, and planning across spending areas. Someone who wants a detailed household budget may prefer that kind of specialist view, using Barclays US only to confirm the underlying account activity.
The same applies if you use several banks, cards, or investment services. A multi-account finance dashboard can be more convenient when the goal is one combined overview. The trade-off is that aggregation introduces another layer between you and the original institution. I would choose direct access when account-specific confidence matters most, and a broader dashboard when comparison across institutions matters more.
There is also a case for using a desktop browser instead. If you are reconciling many transactions, preparing records, or working through a complicated financial task, a larger screen may be easier. The app is strongest for immediate access and short checks. It is not automatically the best environment for every task simply because it is portable.
The friction I would expect before making it your main tool
The first friction is eligibility in practice: the app is useful in proportion to your connection with Barclays US. Someone looking for a bank-neutral money manager may install it and quickly discover that its value is narrower than expected. I would not choose it merely because its rating is high; I would choose it because Barclays US is already part of my financial life or because I have deliberately decided to make it so.
The second is device compatibility. With a minimum operating system of 12, an older phone may not qualify. That is not a flaw for most current devices, but it can become a genuine obstacle for people who avoid upgrading hardware. Check compatibility before rearranging your banking routine.
The third is the limit of mobile convenience itself. A quick view can encourage quick decisions, and a balance does not always explain pending activity, timing, or the difference between money visible in an account and money that is genuinely available for discretionary use. I would use the app actively but not casually. A few seconds of checking should support a decision, not replace judgment.
What switching actually costs
For an existing Barclays US customer, the cost of switching from occasional web access to the app is mostly behavioral. You need to learn where the information you use most often appears, decide whether mobile access suits your routine, and build a habit of reviewing activity without becoming overly dependent on notifications or quick glances. I would begin with one simple task, such as checking recent transactions, before trying to move every banking activity into the phone.
For someone coming from another bank, the cost is much higher because changing an app is not the same as changing a banking relationship. You may need to update payment instructions, review recurring arrangements, and learn a new account structure. I would not make that move solely for a more convenient icon. Compare the institution, account fit, support experience, and your actual money needs first; then treat the app as one part of the decision.
There is also a data-habit cost when moving from a broad finance dashboard to a direct banking app. You may lose the convenience of seeing multiple institutions together, even if direct access feels cleaner. Conversely, moving from a bank website to Barclays US may reduce the effort required for quick checks but leave you wanting a separate system for budgeting. Knowing which convenience you are giving up prevents disappointment.
Who I would recommend it to
I would recommend Barclays US to an existing Barclays US customer who wants dependable mobile access for ordinary account checks and banking tasks. It is especially sensible for people who value direct access, prefer one institution’s own interface, and do not need a single dashboard covering every financial provider.
I would also consider it for a user who wants to start with a simple mobile routine rather than a full financial-management project. Open the app before a significant purchase, review recent activity once a week, and use a separate method for longer-term budgeting if needed. That combination keeps the app in the role where it is most useful instead of demanding that it solve every money problem.
Who should look elsewhere first
I would start with a different category if your main goal is detailed budgeting, shared household planning, or a consolidated view across many institutions. A specialist budgeting tool may give you a clearer answer to those questions, while a broader dashboard may reduce the need to sign into several separate banking apps.
I would also hesitate if your phone cannot meet the minimum operating system requirement, or if you strongly prefer completing financial tasks on a desktop. In those cases, the app may add more inconvenience than value. There is no prize for forcing a mobile workflow when another format matches your habits better.
My final decision guide
After reviewing Barclays US as a finance app, my recommendation is conditional but positive. If you already bank with Barclays US, I think it is worth trying because the free mobile access can make routine account checks easier and more timely. Its 4.7 average and broad user base support the impression that it works well for many people, but I would still judge it by the tasks you personally repeat.
Choose it for direct Barclays access, not as a replacement for every financial tool. That is the distinction I would want a friend to understand before installing it. Use it to verify account activity and stay connected to your banking relationship; pair it with a budgeting method if you need deeper planning. If you want a bank-neutral overview or detailed spending analysis, compare alternatives in those categories instead.
For me, the app’s best quality is restraint. It belongs in a routine where a few focused checks help me make better decisions without turning money management into a constant activity. The limitations are equally clear: it is tied to Barclays US, depends on a compatible device, and should not be mistaken for a complete financial plan. With those boundaries in mind, I would recommend Barclays US to the right customer, while encouraging everyone else to choose the tool that matches the question they actually need answered.
Pros
- User-friendly interface for easy navigation.
- Comprehensive financial tools and resources.
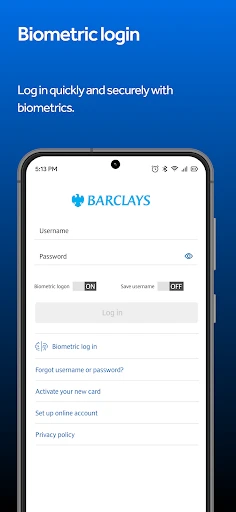
- Secure login with fingerprint and PIN options.
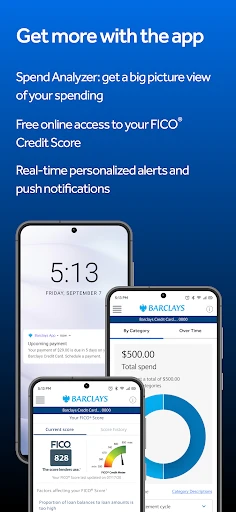
- Real-time transaction alerts and notifications.
- Efficient customer support service.
Cons
- Limited to Barclays US account holders only.
- Some features require strong internet connection.
- Occasional bugs and app crashes reported.
- Limited customization options for app interface.
- No multi-language support available.
Frequently Asked Questions
What features does the Barclays US app offer?
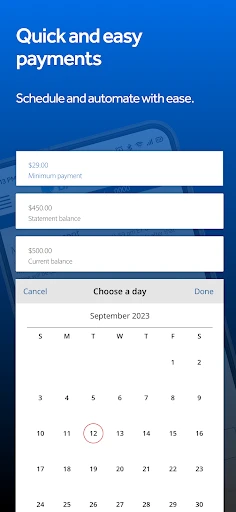
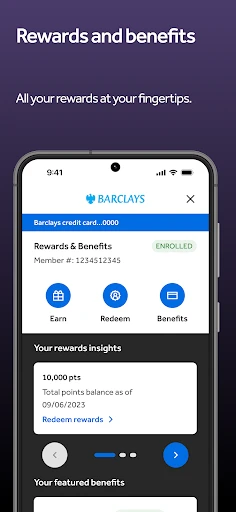
The Barclays US app provides a variety of features to enhance user convenience, including easy account management, transaction monitoring, and instant alerts. Users can also access their credit card statements, make payments, and track their rewards. Additionally, the app supports secure login with fingerprint or face recognition for added security.
Is the Barclays US app secure for online banking?
Yes, the Barclays US app employs multiple security measures to ensure safe online banking. It uses encryption to protect your data, and offers biometric login options like fingerprint and face recognition. Additionally, the app provides real-time fraud monitoring and alerts to keep your financial information secure.
Can I manage multiple accounts with the Barclays US app?
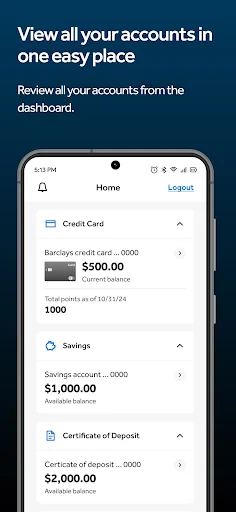
Indeed, the Barclays US app allows you to manage multiple accounts from a single interface. Whether you have different credit cards or bank accounts with Barclays, the app lets you switch between them seamlessly. This feature is particularly useful for users who need to oversee various financial activities in one place.
How can I troubleshoot issues with the Barclays US app?
If you encounter issues with the Barclays US app, you can start by checking for updates in your app store, as a newer version may resolve your problem. Also, ensure your internet connection is stable. For persistent issues, the app provides a customer support section where you can find help or contact Barclays support directly for assistance.
What platforms is the Barclays US app available on?
The Barclays US app is available on both Android and iOS platforms, making it accessible for a wide range of smartphone users. You can download the app from the Google Play Store for Android devices or the Apple App Store for iOS devices. Ensure your device meets the app's system requirements for optimal performance.