BILL Spend & Expense (Divvy)
- Rating
- 4.5
- Downloads
- 100,000+
- Age
- Everyone
Additional Info
- App Name
- BILL Spend & Expense (Divvy)
- Category
- Business
- Package Name
- com.divvypay.Divvy
- Developer
- Bill.com Inc.
- Rating
- 4.5
- Version
- 4.0.17
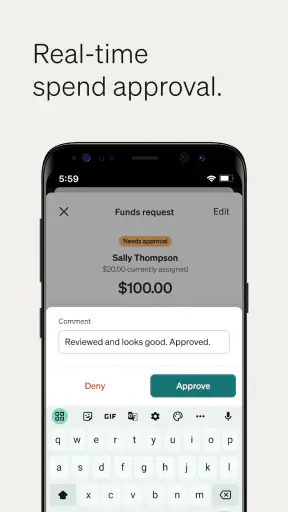
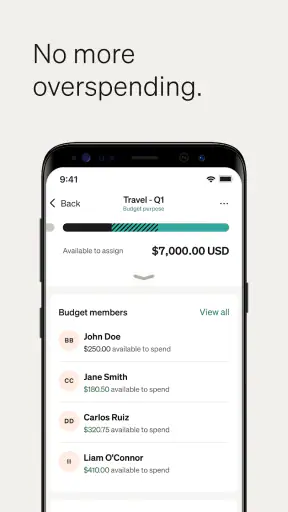
 Analysis by Appcrazy
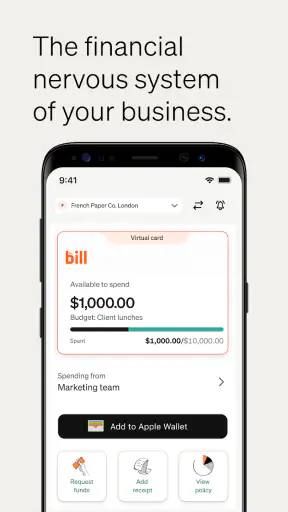
Managing business spending from a phone sounds simple until receipts, employee purchases, approvals, and card limits start arriving from different places. My experience with BILL Spend & Expense is that it is most useful when a company wants those daily money movements to follow one shared process instead of living in email threads, spreadsheets, and scattered card statements. It is a free business app from Bill.com Inc., focused on corporate cards and expense management rather than personal budgeting.
The central idea is practical: give business spending a clearer home, then make it easier to review what was bought and why. That makes the app a better fit for teams than for individuals who simply want to watch household expenses. I would recommend it to a small business owner, finance lead, or team manager who needs visibility over employee spending without turning every purchase into a manual administrative task. I would be more cautious with a freelancer or a very small operation that has no shared card activity and only a handful of expenses each month.
What using BILL Spend & Expense feels like in daily work
The first thing I noticed is that the product is built around business accountability. A corporate card purchase is not treated as an isolated transaction; it belongs in a wider process where someone can connect spending with a work purpose, review it, and keep the record organized. That distinction matters because ordinary banking apps are good at showing that money left an account, but they are rarely designed around the question a finance team asks next: what was this purchase for, and is it acceptable?
In a realistic everyday scenario, imagine a small consulting team with employees visiting clients. One person pays for a meal or local transport with a company card, then opens the app while the details are still fresh. Instead of waiting until the end of the month to reconstruct the purchase, the employee can deal with the expense as part of the normal workday. The manager has a better chance of seeing the context while it is still understandable, and the finance person is not left deciphering a vague line on a statement later.
That workflow is the strongest reason to choose this app. It shifts expense administration closer to the moment of purchase. I find that especially valuable for teams where the real cost is not the transaction itself but the time spent chasing missing explanations, receipts, or approvals afterward. The app does not make spending decisions for a business, but it can make the trail around those decisions easier to manage.
It is also worth separating the corporate-card side from the expense-management side. A company may care about controlling how employees spend, but it may care just as much about what happens after the card is used. BILL Spend & Expense brings those concerns into the same business-oriented experience. That is more focused than using a personal finance tracker, and more relevant to a manager than simply handing employees access to a bank account.
Where the app earns its place
My favorite aspect is the reduction of ambiguity. Business expenses often become difficult not because the purchase was complicated, but because the explanation arrives too late. A coffee meeting, software renewal, taxi ride, or client meal can look obvious to the person who paid and completely unclear to someone reviewing the account weeks afterward. A dedicated expense workflow encourages better context while the information is still available.
That creates a useful behavioral advantage. When employees know that company spending belongs in an organized review process, they are less likely to treat the corporate card like an ordinary personal payment method. The app becomes a shared record of responsibility, not merely a place to check a balance. For a growing team, that distinction can be more important than having a longer list of isolated finance tools.
Take a Look at Our Blog
How foodpanda Is Turning Food Delivery Into an Everyday Habit
Prime Video's Strategic Surge in the Streaming Wars
Gardenscapes: Puzzle Solving Meets Garden Restoration
Why Google Messages Is the Ultimate Communication Hub
Lords Mobile: Kingdom Wars Tested When Mobile Strategy Goes Wrong
Mastering Plants vs. Zombies™: The Essential Sunflower Strategy
Another practical strength is the mobile setting. Expense work is often delayed because it is assigned to a desk-bound task, even though the purchase happens on the road. A phone-based workflow is sensible for sales staff, consultants, field workers, and managers who are rarely sitting in front of the same computer at the same time. I would still expect serious reconciliation and financial review to require careful attention, but mobile access makes the first step less likely to be forgotten.
The app’s business focus also makes it easier to discuss spending with a team. Instead of asking employees to understand a finance system designed primarily for accountants, a company can give them a more direct route into the part of the process that affects them. That does not remove the need for internal rules. It does make those rules easier to connect to actual purchases.
Its public reception supports the impression that the concept is resonating with a substantial user base: the app holds a 4.5 average from around 4.3 thousand ratings, with more than 500 written reviews. I treat those figures as useful context rather than proof that every company will have the same experience. Expense processes depend heavily on company policy, card setup, approval habits, and how consistently employees use the workflow.
Three workflows that deserve more attention
First, I would use the app as a “same-day cleanup” tool rather than a monthly bookkeeping tool. Asking employees to resolve the context of a purchase soon after it happens is a small operational change, but it can prevent a large amount of end-of-month detective work. This is particularly helpful for travel and client-facing work, where the reason for a transaction becomes harder to remember quickly.
Second, I would treat the app as a coaching mechanism for spending policy. If a team repeatedly submits unclear or questionable expenses, the manager can identify a pattern and clarify the rule with the whole group. That is more constructive than correcting each transaction in isolation. The app is therefore useful not only for recording expenses but also for showing where a company’s internal guidance is too vague.
Only Want to Download? BILL Spend & Expense (Divvy)
Third, I would avoid giving every employee the same expectations. A frequent traveler may need a quick mobile routine, while an office-based employee may only use the system occasionally. The best results come from matching the process to the person’s work: simple instructions for occasional users and a consistent habit for people who make regular business purchases. That is an implementation insight, not a flashy feature, but it can determine whether the tool actually reduces administrative work.
These workflows also reveal an important trade-off. The app can organize a company’s process, but it cannot create discipline by itself. If managers do not review spending, or if employees ignore the company’s rules, a digital record will still be incomplete. I would introduce it alongside a short, plain-language expense policy rather than expecting the app to solve policy confusion on its own.
What it does better than familiar alternatives
The usual alternative is a mixture of corporate cards, email, spreadsheets, and a general accounting package. That combination can work, especially for a very small business with predictable expenses. Its weakness is fragmentation. The transaction may appear in one place, the receipt in another, and the explanation in a message that nobody remembers to save. BILL Spend & Expense is more appealing when the company wants the employee’s spending activity and the review process to feel connected.
A personal finance app is an even poorer comparison for most business teams. Personal budgeting tools are generally designed around an individual’s income, household categories, and financial goals. They do not naturally answer the operational questions that matter in a company: who made the purchase, what business purpose supports it, and how should a manager review it? For those questions, a dedicated business expense app is the more logical category.
On the other hand, a full accounting platform may remain the better choice for a company that needs broad bookkeeping, tax preparation, invoicing, payroll, or complex financial reporting in one environment. I would not choose this app as a replacement for every finance system simply because it handles spending well. Its value is strongest at the card-and-expense layer, where employee purchases need structure and visibility.
That boundary is important for buyers. If your main problem is uncontrolled employee spending and messy expense follow-up, this app deserves serious consideration. If your main problem is producing complete financial statements or running an entire back office, you should evaluate it as one part of the workflow rather than assuming it is the whole solution.
The friction I would want a team to understand
The biggest limitation is behavioral, not cosmetic. Every expense process introduces another responsibility for employees. Even a well-designed mobile workflow can feel like an interruption when someone is traveling, meeting a customer, or moving between jobs. If the company makes the process too demanding, employees may postpone it, and the promised time savings will disappear into reminders and follow-ups.
There is also a learning curve around responsibility. Managers need to decide who reviews spending, how quickly they review it, and what happens when information is missing. Without those decisions, the app may collect transactions without producing a reliable approval habit. In my view, this is where many business expense tools disappoint: the software is ready before the organization has agreed on the process.
Another point of caution is scale and complexity. A small team with straightforward card use may find the app approachable, but a larger organization with highly specialized finance controls may need a more extensive platform or a carefully planned integration strategy. I would test the real workflow with a few employees before rolling it out widely. The important test is not whether a finance expert can operate it, but whether a busy employee can complete the necessary expense work without repeated assistance.
The minimum operating-system requirement is also something to check before deployment. The current version is 4.0.17 and requires iOS or Android 12, so older devices may not be suitable for a company-wide rollout. That is not a problem for teams with reasonably current phones, but it can become an unexpected obstacle when a business allows employees to use aging personal devices.
I would also be careful about confusing a clean record with a complete record. A transaction can be categorized and still need human judgment. A manager should continue checking whether the expense fits the company’s policy and business purpose. The app can make that review more manageable, but it should not encourage automatic approval of everything that looks tidy on screen.
Who should use it, and who should skip it
I see the best fit in small and midsize businesses where several people spend on behalf of the company and someone needs a clearer way to supervise that activity. It is particularly suitable for teams with travel, client meetings, distributed work, or employees who rarely submit expenses from a central office. The mobile format makes the most sense when purchases happen away from a desk.
It can also suit a business that has outgrown a shared spreadsheet but is not ready to adopt a much broader finance platform. That middle ground is where the app is most convincing. It gives the company a more deliberate expense process without forcing every employee to become an accounting specialist.
I would skip it if you only need a personal spending tracker, if nobody else uses company cards, or if your monthly expense volume is so low that manual review takes only a few minutes. In those cases, adding a business workflow may create more setup than value. I would also look elsewhere if your priority is a complete accounting suite rather than corporate-card and expense administration.
Before choosing it, I would ask four practical questions. Will employees use the app soon after making purchases? Is one person clearly responsible for review? Does the company have a simple policy that employees can understand? And are the team’s devices compatible with the current operating-system requirement? If the answers are yes, the app has a realistic chance of improving the process. If the answers are no, changing the workflow may matter more than changing the software.
Availability and day-to-day expectations
The app is free to download and carries an Everyone content rating, which makes it easy to consider for a mixed business workforce. It was released on August 10, 2017, and has passed 100 thousand installs. Those details suggest an established mobile product rather than a newly launched experiment, while the current version indicates that it continues to be maintained.
I would still judge it by the quality of the company’s process around it. A free app can be valuable when it removes repeated administrative work, but “free” should not be mistaken for “effortless.” The real investment is employee adoption, manager review, and deciding how the records fit into the rest of the business’s financial routine.
My final view is positive but deliberately specific: BILL Spend & Expense is a strong choice for organizing corporate-card activity and making employee expenses easier to follow. Its best contribution is not that it turns finance into something exciting; it is that it can move expense context closer to the purchase and reduce the confusion that appears later.
I would recommend it to a business that needs a practical bridge between scattered card activity and a more accountable expense process. I would not recommend treating it as a universal replacement for accounting software, nor would I install it without agreeing on simple internal rules first. For the right team, the real win is less chasing and more timely visibility. That is a modest promise, but in everyday business administration, it is exactly the kind of improvement that can make a tool worth keeping.
Pros
- Virtual cards help control employee spending and reduce fraud risk.
- Real-time transaction alerts make unusual purchases easier to spot.
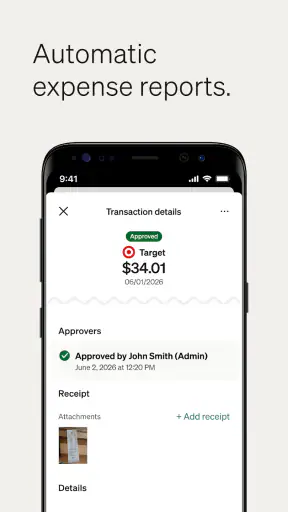
- Receipt capture keeps supporting documents attached to expenses.
- Custom approval rules can match different team and budget requirements.
- Useful reporting tools help identify spending patterns and budget leaks.
Cons
- Some advanced features may require a higher-priced subscription plan.
- Employees may need training to follow card and receipt procedures correctly.
- Limited offline functionality can be inconvenient during travel.
- Bank or accounting integrations may need extra setup and maintenance.
- Expense categorization may require manual corrections for some transactions.
Frequently Asked Questions
What is BILL Spend & Expense (Divvy), and who is it designed for?
BILL Spend & Expense, formerly known as Divvy, is a business spending and expense-management platform designed for companies, finance teams, and employees. It combines corporate cards, budgets, expense tracking, receipt collection, approvals, and reporting in one system. It is mainly intended for organizations rather than personal budgeting, and availability depends on the employer’s BILL account and administrative setup.
Can employees use the BILL Spend & Expense app without a company account?
Usually, no. The mobile app is primarily a companion for businesses already using BILL Spend & Expense and generally requires an invitation or login connected to an organization’s account. Employees may need administrator-provided credentials, company authentication, or an assigned corporate card. If you are looking for a personal finance app, this service may not be suitable because its main features depend on employer configuration.
What can I do with the BILL Spend & Expense mobile app?
Depending on your company’s plan and permissions, the app can help you view available spending funds, check card activity, submit or review expenses, upload receipts, add notes, and monitor transactions while traveling or working remotely. Managers may also be able to approve expenses and review spending. The exact tools shown can differ because administrators control budgets, policies, cards, and user permissions.
Is BILL Spend & Expense safe for handling business transactions and receipts?
BILL Spend & Expense is built for business spending management and uses account access controls, transaction monitoring, and administrative policies to help organizations manage financial activity. However, no online service is completely risk-free. Users should protect passwords, enable available security features, avoid sharing login details, and report suspicious transactions promptly. Companies should also review BILL’s current security documentation and privacy terms before adopting the platform.
Does BILL Spend & Expense charge users, and are there any important limitations?
Individual employees typically do not pay a separate fee simply to use the mobile app, but the organization may have a paid BILL subscription, corporate card arrangement, or other applicable costs. Features, limits, reimbursement options, integrations, and approval workflows can vary by plan and account configuration. Before downloading, confirm with your employer whether your account is supported and which functions are enabled for your role.