ConnectEBT
- Rating
- 4.3
- Downloads
- 1,000,000+
- Age
- Everyone
Additional Info
- App Name
- ConnectEBT
- Category
- Finance
- Package Name
- com.conduent.ebt
- Developer
- Conduent Incorporated
- Rating
- 4.3
- Version
- 2.3.5(20251009)
 Analysis by Appcrazy
Managing SNAP or cash benefits is easier when the information you need is available before you reach the checkout line. I found ConnectEBT most useful as a focused account-checking tool: it brings EBT account information into a mobile app instead of making every balance check depend on a phone call, a receipt, or a trip to an office. That narrow purpose is also the key to deciding whether it belongs on your phone.
ConnectEBT is a free finance app from Conduent Incorporated. It is intended for everyone, has earned a 4.3 average from around 14 thousand ratings, and has passed over a million installs. Those figures suggest that it is not an obscure utility, but the real question is more practical: does it make your particular EBT routine simpler, and are you comfortable using a dedicated app rather than the usual alternatives?
What I looked for when deciding whether it is worth using
I judge an EBT app by a few everyday standards. First, it should help me answer the question I usually have at the worst possible moment: how much money or SNAP balance is available right now? Second, it should reduce uncertainty around recent activity, because an unexpected balance can come from a purchase, a delayed transaction, or a benefit adjustment. Third, it should be simple enough to use when I am busy, shopping, or helping someone who is not especially comfortable with smartphones.
I also pay attention to what the app is not. ConnectEBT is not a general budgeting platform, a bank replacement, or a broad personal-finance dashboard. Its value comes from staying close to EBT account information. If you want investment tracking, bill management, credit monitoring, or a combined view of several bank accounts, a conventional finance app is likely a better match. Adding ConnectEBT will not turn your benefits into a complete household budgeting system.
That specialization is helpful for people who want a direct route to their benefit information. It also means the quality of the experience depends on whether the app supports the EBT account and program relevant to the user. I would check that practical fit during setup rather than assuming that any EBT-related app automatically covers every account in every location.
The first useful habit: check before shopping
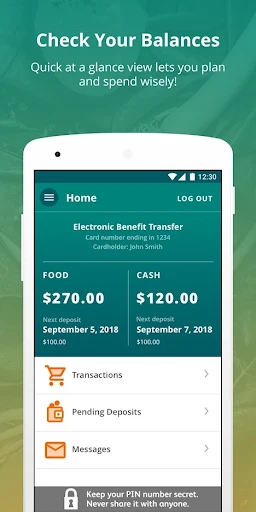
The most valuable workflow is simple but easy to overlook. Before leaving for the supermarket, I would open the app and check the available SNAP or cash balance, then compare it with the amount I expect to spend. This is more useful than waiting until the payment terminal rejects a transaction. It also helps when I am dividing a shopping trip across benefits and another payment method.
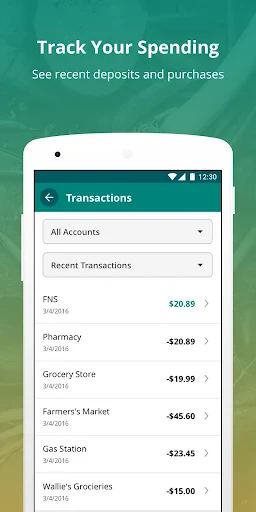
A second good habit is checking after an important purchase rather than relying only on a printed receipt. A receipt can tell me what happened at one store, while an account view is more useful for understanding the balance I have left for the rest of the week. I would not treat the app as a substitute for keeping receipts, though. Receipts remain useful when I need to investigate a disputed or confusing transaction.
Catch Up on the Latest Stories
Microsoft Teams on Mobile Keeps Work Moving, If You Keep It Tidy
Groupon Turns Local Discounts Into a Marketplace, With a Catch
App of the Week: Yandex Go Makes City Errands Easier
Make Xiaomi Weather Work Harder with Smarter Settings and Daily Routines
Boomplay Turns Music Streaming Into a Daily Discovery Habit
Google Docs on Mobile Keeps the Page in Focus, Until Formatting Gets in the Way
There is a small but important planning advantage here. If benefits are shared across a household, checking the balance before shopping can prevent an awkward conversation at the register. It gives the person making the purchase a chance to adjust the list, postpone nonessential items, or bring another payment method. That is a practical benefit that a short store summary does not reveal.
How the focused design helps
ConnectEBT does not ask me to organize my entire financial life. For someone who only wants EBT account information, that focus can be less distracting than opening a banking app filled with unrelated balances, offers, charts, and notifications. The app’s purpose is immediately understandable: use it to stay aware of SNAP and cash account information.
I also see value for caregivers or family members helping someone manage benefits. A quick account check can support a shopping plan without requiring the person to remember a customer-service process every time. That does not remove the need to protect login details or respect the account holder’s privacy, but it can make routine assistance more manageable.
Another useful approach is to make the app part of a regular schedule. Checking only when a payment fails is reactive. Checking before a major grocery trip, after a transaction that looks unusual, and when planning the final shopping trip before the next benefit cycle creates a clearer picture. The app is most helpful when used as a small planning tool rather than an emergency button.
Where I noticed friction
The narrow scope that makes ConnectEBT clear can also make it feel limited. I would not install it expecting detailed spending analysis, a full monthly budget, or advice on stretching household income. It is designed around access to account information, not around teaching personal finance. Users who want categories, goals, bill reminders, or multiple financial accounts in one place will probably need another app alongside it.
There is also a difference between seeing account information and resolving an account problem. If a balance looks wrong, an app can help me notice the issue, but it may not explain every reason behind it or settle a dispute by itself. I would keep transaction records and use the appropriate official support route when the issue involves a missing benefit, an unfamiliar charge, or a card problem. Expecting a balance-checking app to replace account support is a common source of disappointment.
Like any account app, it also requires a little discipline around access. I would avoid saving sensitive details where another person can easily see them, and I would be careful when using a shared device. Convenience is valuable, but EBT information is still personal financial information. A quick check should not become a reason to treat account security casually.
Choosing ConnectEBT instead of the usual alternatives
The first alternative is the traditional route: calling the number associated with the EBT account or using information from a receipt. That approach may suit someone who rarely checks a balance, has limited phone storage, or prefers not to manage another login. It can also be useful when the app is unavailable or when a question requires a human representative. The trade-off is that it is less convenient for quick planning before a shopping trip.
Receipts are particularly useful as a record of an individual purchase, but they are not a complete replacement for an account view. A receipt can be misplaced, and it does not help much before the first purchase of the day. I see ConnectEBT as stronger for current awareness, while receipts remain stronger for keeping a paper trail. Using both is more sensible than forcing one method to do every job.
The second alternative is a general banking or budgeting app. That option makes more sense for someone who wants a complete household picture, especially if the main goal is tracking checking accounts, recurring bills, savings, and spending categories together. The drawback is that a general finance app may not offer the same direct focus on SNAP and cash account information. For a benefits-centered task, a broader dashboard can be more work than necessary.
A third alternative is a state or program-specific service, where available. That may be preferable if a user needs a wider set of administrative tasks or support connected to a particular local program. I would choose such a service when its main purpose matches the problem I am trying to solve. I would choose ConnectEBT when the priority is a straightforward mobile way to access the relevant account information and the account is supported.
This is why I would not call ConnectEBT universally better than every alternative. It wins on focus and convenience for routine checks. A phone line may be better for resolving a complicated issue. A receipt may be better for documenting one transaction. A general finance app may be better for a complete budget. The right choice depends on whether the user needs visibility, support, documentation, or broader financial organization.
A realistic shopping-day example
Imagine I am planning a grocery trip near the end of the benefit period. I open ConnectEBT before making the list and see the balance available for the account. I then separate essential items from items that can wait. At the store, I keep the receipt, and after paying I check the account again when I have time. If the remaining balance does not match what I expected, I have both the receipt and the account view available when I investigate.
That workflow does not require complicated budgeting, but it prevents several avoidable problems. I am less likely to discover the balance at the checkout, less likely to confuse an old receipt with the current account position, and better prepared to identify a transaction that deserves attention. For me, this is the strongest argument for the app: it turns a vague question into a quick routine.
What switching to the app really involves
Moving from phone checks or receipts to ConnectEBT is not a major financial commitment because the app is free. The real cost is setup time, learning a new routine, and deciding whether another account credential is worth managing. Someone who checks a balance only once in a while may not feel enough benefit to change. Someone who shops frequently or needs to plan carefully may recover that small effort quickly through easier access.
I would also avoid deleting the old method immediately. Keep the account’s support information and retain receipts while learning how the app fits into your routine. If the app does not work for a particular account or if an account question requires assistance, the traditional route remains important. Switching should add convenience, not remove the fallback that helps when something goes wrong.
The current release is listed as version 2.3.5(20251009), and it supports Android 7.0 or later. In practical terms, that makes it accessible to many older Android phones, although the experience will still depend on the device and the account setup. I would update the app when updates are available and avoid judging the entire service from one temporary connectivity or login problem.
Because the app is rated for everyone, it is positioned as a general-access utility rather than something limited to a mature audience. That does not mean every child should manage an account independently; it simply reflects the app’s broad content classification. For families, the sensible approach is to decide together who checks the information and how account access is protected.
Who should use it, and who should skip it
I recommend ConnectEBT to people who regularly need to check SNAP or cash account information from an Android phone and want a quicker option than calling or waiting for a receipt. It is especially practical for shoppers who plan purchases around a changing balance, households where one person helps another with shopping, and anyone who has experienced the stress of discovering the available amount too late.
I would be more cautious about recommending it to someone who wants one app for every part of personal finance. It will not replace a full budgeting service, and I would not choose it as the main tool for tracking bank accounts, debts, subscriptions, or long-term goals. I would also suggest sticking with a familiar alternative if the user rarely checks benefits or finds account setup and login management more frustrating than helpful.
People who need immediate help with a disputed transaction should also think beyond the app. ConnectEBT can be useful for spotting the discrepancy and reviewing the account situation, but a support channel may be the better next step for correction or explanation. That distinction matters: information access is valuable, but it is not the same as case resolution.
My recommendation
After using it as a focused finance utility, I see ConnectEBT as a sensible choice for its intended job. It does not try to be a bank, a budgeting coach, or a customer-service replacement. Instead, it gives EBT users a convenient way to stay aware of SNAP and cash account information, which can make ordinary shopping decisions less stressful.
My recommendation is to try it if balance awareness is a recurring part of your week. Start by using it before a grocery trip, compare what you see with your receipt afterward, and keep the traditional support route available for problems that require more than a balance check. If you need broad financial management rather than EBT-focused access, choose a general budgeting or banking option instead.
For the right user, the app’s restraint is its advantage. ConnectEBT is free, widely used, and easy to understand as a dedicated account-information tool. Its limitations are real, but they are mostly limitations of scope rather than a reason to dismiss it. If your decision comes down to “Can I check my EBT information more conveniently before I shop?”, this is the kind of app I would put on my shortlist.
Pros
- Easy to navigate user interface.
- Fast balance updates and transaction history.
- Supports multiple EBT card types.
- Secure login with biometric options.
- Free to download and use.
Cons
- Limited customer support options.
- Occasional app crashes reported.
- Requires constant internet connection.
- No offline transaction history access.
- Ads may appear during use.
Frequently Asked Questions
What is ConnectEBT and how does it work?
ConnectEBT is a mobile application designed to help users manage their Electronic Benefits Transfer (EBT) accounts conveniently. It allows users to check their balance, view transaction history, and find nearby stores that accept EBT. By logging in with their EBT card details, users can efficiently track their benefits and expenditures without needing to call customer service or visit an ATM.
Is ConnectEBT safe and secure to use for managing my benefits?
Yes, ConnectEBT is designed with security in mind, employing robust encryption and security protocols to ensure that your personal and financial details are kept safe. The app requires users to log in with their EBT card information and a secure PIN, similar to online banking apps, to protect against unauthorized access.
Can I use ConnectEBT on any device?
The ConnectEBT app is available for both Android and iOS devices. Users can download it from the Google Play Store for Android devices or the Apple App Store for iOS devices. However, it is important to ensure that your device meets the app's compatibility requirements, which usually include having a recent operating system version and sufficient storage space.
What should I do if I encounter issues logging into ConnectEBT?
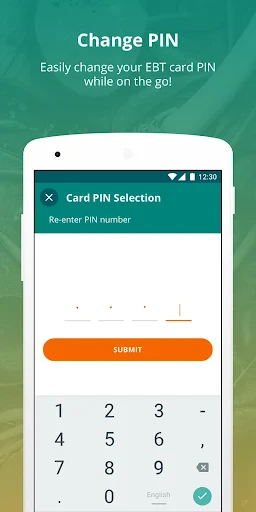
If you experience login issues with ConnectEBT, first ensure you are using the correct EBT card number and PIN. If problems persist, consider resetting your PIN through the app or contacting customer support for assistance. The app may also provide troubleshooting tips or guidance on resolving common login issues within its help section.
Does ConnectEBT charge any fees for using its services?
No, ConnectEBT does not charge users for accessing their EBT account information through the app. The service is completely free, allowing you to manage your benefits without incurring additional costs. However, be aware of any data charges from your mobile network provider when using the app, especially if accessing features that require an internet connection.