CPOS: Tap to Pay Card Reader
- Rating
- 4.4
- Downloads
- 10,000+
- Age
- Everyone
Additional Info
- App Name
- CPOS: Tap to Pay Card Reader
- Category
- Business
- Package Name
- com.cpos.taptopay
- Developer
- CPOS
- Rating
- 4.4
- Version
- 2.34.0
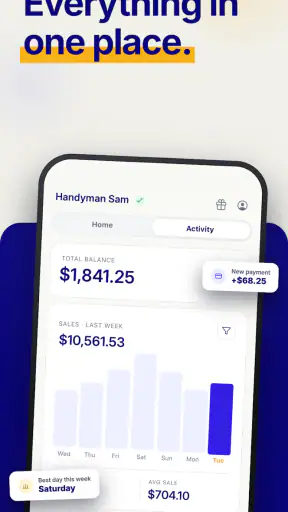
 Analysis by Appcrazy
Accepting a card payment from a phone sounds simple, but the practical difference is bigger than it first appears. CPOS: Tap to Pay Card Reader is a free business app from CPOS that turns a compatible phone into the point where a customer can tap a card or contactless payment method. In my experience, its appeal is not that it replaces every checkout system; it is that it removes the need to carry a separate reader for certain kinds of selling.
That makes it especially interesting for people who take payments away from a permanent counter. A market seller, mobile service provider, independent professional, or small team working at events can keep the payment point in the same device they already use for communication and administration. The app is listed for everyone, and its current version is 2.34.0, with Android support beginning at version 8.0.
I would describe it as a focused business tool rather than a complete retail platform. Its central job is taking a contactless payment through the phone, and that narrow purpose is also its main strength. If you need a full register, stock control, staff permissions, detailed sales reporting, or a broad collection of checkout accessories, this is not the kind of app I would choose first. If your main problem is carrying or setting up payment hardware, however, the idea is much more practical.
Turning the phone itself into the payment point
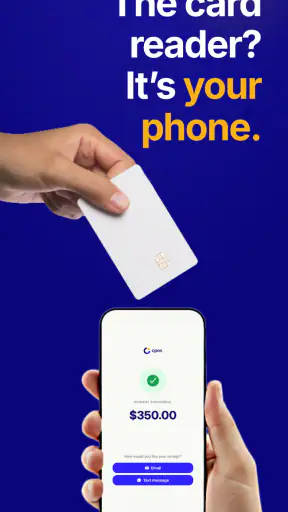
The important capability here is phone-based card acceptance. Instead of pairing the app with a dedicated terminal, the customer presents a contactless card or compatible device to the phone. The phone becomes the physical point of interaction, which can make a short transaction feel much less complicated.
That change matters most when the sale happens somewhere temporary. A conventional reader is another item to charge, remember, protect, and connect. A phone-based approach keeps the payment step close to the person already handling the appointment, delivery, demonstration, or sale. It also reduces the visual clutter that can make a small transaction feel more formal than it needs to be.
I like this model for businesses that do not need a permanent checkout station. Imagine a photographer collecting a remaining balance after a session, a repair specialist taking payment at a customer’s home, or a stallholder selling a few items during a short event. In each case, the phone is already part of the workflow. Adding a separate reader can feel disproportionate, while using the phone keeps the setup compact.
The app is free, which lowers the barrier to trying the approach. That does not mean every payment-related cost disappears; the wider payment arrangement and transaction terms still matter in real use. I would not treat “free” as a promise that accepting payments has no commercial cost. I would treat it as a reason the software itself is easier to evaluate before committing to extra equipment.
Catch Up on the Latest Stories
Microsoft Teams on Mobile Keeps Work Moving, If You Keep It Tidy
Groupon Turns Local Discounts Into a Marketplace, With a Catch
App of the Week: Yandex Go Makes City Errands Easier
Make Xiaomi Weather Work Harder with Smarter Settings and Daily Routines
Boomplay Turns Music Streaming Into a Daily Discovery Habit
Google Docs on Mobile Keeps the Page in Focus, Until Formatting Gets in the Way
There is also a useful distinction between a card reader and a complete business system. CPOS focuses attention on accepting the payment. It should not be mistaken for an automatic replacement for invoicing, bookkeeping, inventory management, customer records, or a traditional till. I found that distinction helpful because it prevents unrealistic expectations: the app can simplify the moment money changes hands without organizing the whole business around that moment.
What the tap changes for a small business
A contactless transaction through the phone can shorten the handoff between agreeing on a price and completing the sale. The customer does not need to wait while a separate terminal is found or connected, and the seller does not need to move the customer to a fixed counter. That flexibility is the real effect of the feature.
It can also make occasional card acceptance more approachable. A business that only takes payments at appointments, pop-up events, or on-site visits may not want a permanent terminal sitting unused between jobs. The phone-based format suits that irregular rhythm better than hardware designed around a fixed checkout.
My practical advice is to think about where the phone will be held during payment. A compact setup is convenient, but it also means the device is doing more than one job at once. If you are checking an appointment, messaging a customer, and accepting payment on the same phone, you need a clean handoff between those activities. Keeping the payment moment deliberate helps avoid entering the wrong amount or rushing the customer through the tap.
Another non-obvious benefit is consistency of location. When the payment point is always the phone, staff or owners do not have to remember which reader belongs to which account or which device is charged. That can be valuable for a solo operator who works from different places. The trade-off is that the phone becomes more important: if it is unavailable, the payment workflow is affected too.
How I would use it during a real transaction
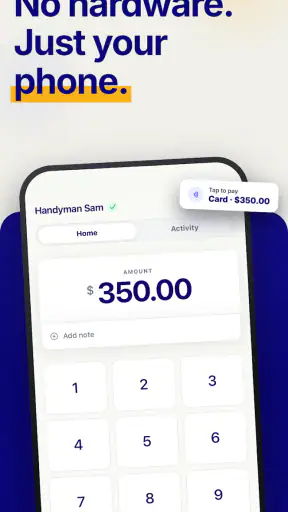
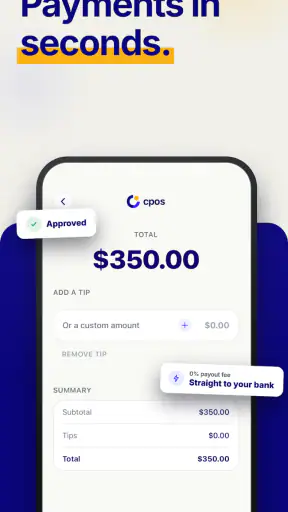
The day-to-day process is easiest to understand as a short sequence. I would prepare the amount, show the customer the total, let the app guide the contactless interaction, and wait for the transaction result before treating the sale as complete. The customer then taps the relevant card or device against the phone rather than against a separate reader.
That sounds obvious, but the small habits around it make a difference. I would confirm the amount aloud before presenting the phone, especially when several customers are waiting. I would keep the display visible to the customer where possible, so the interaction feels transparent rather than like the seller is silently operating a device. Once the result appears, I would make sure the customer knows whether the payment succeeded before moving on.
This is also where phone placement matters. A crowded counter, thick case, or awkward grip can turn a quick tap into an uncertain one. I would hold the phone steadily and give the customer a clear target. The app’s value comes from removing hardware, not from removing the need for a calm payment routine.
For a mobile professional, I would build the payment step into the end of the appointment. After confirming the work is finished, I would open the app, enter or confirm the amount, and keep the phone available while the customer taps. That avoids the common problem of searching through apps while the customer is waiting. For a market seller, I would use the same habit after each sale rather than trying to prepare several transactions mentally in advance.
One useful workflow is separating payment confirmation from record keeping. I would not rely on memory to reconstruct the day later. After a transaction, I would make a quick note in the business system I already use, if one is available, or at least maintain a simple sales record elsewhere. This is an important trade-off: a phone card reader can make collection easier, but it does not automatically become the complete source of truth for the business.
Another practical question is whether a customer can use the payment method they prefer. The app’s purpose is contactless card acceptance, so it is best suited to customers who can tap. I would keep an alternative available for situations where someone cannot use contactless payment or where the phone-based interaction does not work smoothly. A payment tool is most useful when it fits into a fallback plan instead of being treated as the only possible route.
The best everyday scenario
The strongest use case, in my view, is an independent service provider who visits customers and wants to collect payment immediately after completing a job. Consider a mobile cleaner, tutor, stylist, or technician. There is no permanent counter, the customer may not want to handle cash, and carrying a separate terminal adds one more object to an already mobile routine.
With CPOS, the provider can keep the payment point with the phone used for calls, directions, and scheduling. The customer sees the amount, taps, and the provider can finish the visit without arranging a later transfer or invoice simply because the payment hardware was left at home. The convenience is not theoretical; it changes the timing of the business’s cash collection.
I also see a good fit for small events. A seller who attends occasional fairs or pop-up activities may need card acceptance only on certain days. A phone-based app is easier to pack than a full checkout setup, and the seller can move around rather than forcing every customer toward one table. The limitation is that the seller should plan for the phone’s availability, connectivity, battery, and customer flow before relying on it for a busy period.
For a very small transaction, the reduced setup can be more valuable than sophisticated reporting. A person selling a limited range of services or products may prefer a direct payment step over learning a large retail system. That simplicity is exactly why I would recommend testing the app in the real environment before expanding its role. A quiet appointment and a crowded event place very different demands on the same phone.
Where the convenience has limits
The first trade-off is dependence on the phone. With a separate terminal, the payment device has one clear purpose. With CPOS, the phone is also your communication tool, camera, calendar, and possibly your navigation device. If the battery is low, the screen is damaged, or the phone is needed for another urgent task, accepting a payment becomes less convenient.
I would prepare for that by starting a selling period with the phone charged and by avoiding unnecessary multitasking during the transaction. This is not a criticism unique to CPOS; it is the natural cost of consolidating several tools into one. The fewer devices you carry, the more important that single device becomes.
The second limitation is scope. A business that needs barcode scanning, product catalogs, printed receipts, cash-drawer control, employee accounts, or detailed inventory movement may quickly outgrow a phone card reader. A traditional point-of-sale system or a more comprehensive commerce app would be a better fit in that situation. CPOS makes sense when payment acceptance is the missing piece, not when the entire operation needs rebuilding.
There is also a human factor. Some customers are comfortable tapping a card on a phone, while others may expect a conventional terminal. I would explain the process clearly and let the customer see the payment screen. That small amount of communication helps the phone feel like a deliberate payment device rather than a personal handset being used casually.
Security and privacy deserve sensible attention too. I would use a dedicated business phone or at least a separate user profile where practical, keep the device locked when not in use, and avoid leaving payment activity visible to people who do not need to see it. These are general good habits, but they matter more when the business and personal worlds share one device.
The app’s public adoption gives some reassurance that it is not an entirely unknown experiment. It has an average rating of 4.4 from over two hundred ratings, with more than one hundred reviews and over ten thousand installs. I see that as useful context rather than proof that it will suit every workflow. Payment experiences are highly dependent on the phone, the seller’s setup, the customer, and the surrounding payment service.
The age rating of Everyone makes the app broadly approachable, but that should not be confused with suitability for every business environment. A company handling several employees, multiple locations, or complex reconciliation still needs to examine its operational requirements. A simple age rating says little about whether the workflow is sophisticated enough for a particular organization.
Who gets the most value from CPOS?
I would recommend trying it first if you are a solo operator, a mobile service provider, an occasional event seller, or a small business that wants to accept contactless payments without adding a dedicated reader to the kit. It is particularly attractive when sales happen in different places and when the phone is already central to the workday.
The app is also a sensible option for someone testing whether card acceptance would improve a small operation. Since the app itself is free, the evaluation can focus on the actual routine: how quickly you can prepare a payment, how customers react to tapping on the phone, and whether the process fits your records. I would run a few low-pressure transactions before using it at a crowded event or during a tightly scheduled day.
I would be more cautious if you run a busy shop with a queue, several staff members, or a large catalog. In that setting, the phone may become a bottleneck, and the lack of a broader checkout structure could create more manual work than it removes. A dedicated terminal paired with a full point-of-sale system would likely be more efficient, even if it costs more or requires more setup.
I would also look elsewhere if your customers frequently need payment methods outside the app’s contactless focus, or if your business depends on printed receipts and detailed end-of-day reconciliation built into the same system. CPOS can sit alongside those tools, but I would not assume it replaces them. The right question is whether you want a compact payment acceptance layer or a complete business platform.
One final point is worth keeping in mind: the developer is CPOS, and the app was released on January 17, 2025. That places it in a relatively recent stage of its product life, so I would pay attention to how comfortably the current version fits my own phone and routine rather than assuming that every business workflow has been covered. The current version is 2.34.0, and the Android requirement is modest, but compatibility in practice still depends on the device and the payment environment.
After using it as a focused card-acceptance tool, my opinion is positive but specific. CPOS does not need to be a full register to be useful. Its real advantage is letting a seller bring a contactless payment point to the customer with less equipment. If your business is mobile and your main need is a simple tap-to-pay moment, that can remove genuine friction. If you need inventory, staff controls, extensive reporting, or a dedicated checkout experience, I would choose a broader solution instead.
For the right person, the app is easiest to recommend as a practical companion to an existing business routine. Keep your records separately when necessary, plan for the phone’s battery and availability, explain the tap clearly, and maintain a backup payment option. Used with those expectations, this free business app can make occasional or on-site card acceptance feel much more natural.
Pros
- Turns an iPhone or Android phone into a portable card reader.
- Supports contactless payments without requiring extra reader hardware.
- Useful for small businesses
- freelancers
- and mobile service providers.
- Can help reduce checkout queues at events or customer locations.
- Keeps payment acceptance available when operating away from a fixed register.
Cons
- Device compatibility may vary by phone model
- region
- and operating system.
- Requires NFC support and a reliable internet connection for many transactions.
- Transaction fees can reduce earnings
- especially for frequent small payments.
- Customers may be unable to pay if their card or wallet lacks contactless support.
- Account verification and business setup may take time before accepting payments.
Frequently Asked Questions
What is CPOS: Tap to Pay Card Reader?
CPOS: Tap to Pay Card Reader is a mobile point-of-sale solution designed to help businesses accept card payments using a compatible smartphone or tablet. Instead of requiring a traditional card terminal, the app can use contactless payment technology, allowing customers to tap supported cards, phones, or smartwatches on the merchant’s device. Availability and features may depend on the country, payment provider, and supported hardware.
Can I accept contactless payments without a separate card reader?
In supported markets, CPOS may allow merchants to accept contactless transactions directly through a compatible NFC-enabled Android device, reducing the need for additional terminal equipment. However, not every phone is suitable, and iOS and Android support can differ. Before downloading, check the app’s current compatibility list, operating-system requirements, NFC availability, and whether your payment account or acquiring bank supports Tap to Pay.
What types of cards and payment methods does CPOS support?
CPOS is primarily intended for contactless payments, which may include NFC-enabled debit and credit cards as well as digital wallets such as Apple Pay or Google Pay, depending on the payment provider. Support is not necessarily universal, and some cards, wallets, currencies, or transaction types may be restricted. Merchants should confirm supported payment networks and local regulations before relying on the app for daily sales.
Is CPOS: Tap to Pay Card Reader secure for business transactions?
The app is designed for commercial payment acceptance and may use security measures required by its payment partners, such as encrypted communication, tokenization, device authentication, and transaction verification. Nevertheless, security also depends on keeping the phone updated, protecting account credentials, enabling a screen lock, and using a trusted network. Review the provider’s privacy policy, fees, dispute procedures, and compliance information before processing customer payments.
What do I need to use CPOS, and are there transaction fees?
To use CPOS, you will generally need a supported mobile device, an internet connection, NFC capability for contactless transactions, a registered merchant account, and approval from the relevant payment service provider. Fees may include per-transaction charges, subscription costs, account fees, or settlement-related charges. Pricing and eligibility can vary significantly by country and provider, so check the official terms before downloading or accepting payments.