DailyPay On-Demand Pay
- Rating
- 4.7
- Downloads
- 1,000,000+
- Age
- Everyone
Additional Info
- App Name
- DailyPay On-Demand Pay
- Category
- Finance
- Package Name
- com.DailyPay.DailyPay
- Developer
- DailyPay Inc
- Rating
- 4.7
- Version
- 37.0.0
 Analysis by Appcrazy
When an unexpected bill lands before payday, the problem is often not a lack of income but the timing of it. DailyPay On-Demand Pay is built around that gap. It is a finance app from DailyPay Inc that lets eligible workers access wages they have already earned before their normal payday. I see its main value in that very specific promise: it can turn part of a waiting problem into a timing decision.
I would not describe it as a budgeting app, a bank replacement, or a general-purpose borrowing tool. Its usefulness depends on your employer, your pay cycle, and whether taking money early actually improves your situation. Used carefully, it can help with a necessary expense. Used casually, it may make the next payday feel tighter. That distinction is the key to understanding the app.
Getting paid earlier is the whole point
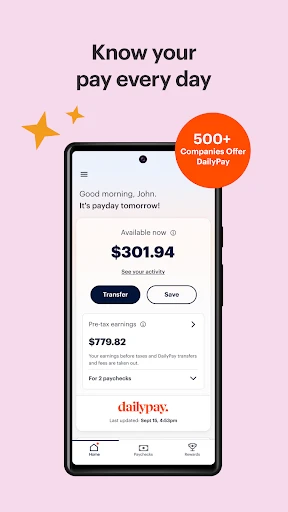
The central capability is access to earned wages before the scheduled payday. In practical terms, the app is aimed at people who have already worked and want to use some of the resulting pay sooner rather than waiting for the complete payroll deposit. That makes it different from a conventional credit card or personal loan: the decision is connected to income you have earned, rather than a separate line of credit.
That difference can feel meaningful during a short cash-flow squeeze. If a utility payment, transport cost, or essential purchase arrives several days before payday, waiting may create more stress than the amount itself. DailyPay gives the user a way to consider whether bringing forward part of the paycheck is preferable to missing the payment or relying on a more expensive alternative.
My strongest impression is that the app solves a narrow problem rather than trying to solve every money problem. It does not automatically make income higher. It changes when available earnings can be used. That sounds simple, but it affects how you plan the rest of the pay period, so I would treat the early-access option as a cash-flow lever, not as extra money.
The app is free to download and is rated for Everyone, which makes it approachable for a broad audience. It has a 4.7 average from around 203 thousand ratings, with more than a million installs. Those figures suggest that the idea is easy for many people to understand, although popularity should not replace checking the actual terms and availability attached to your employment situation.
What I would check before relying on it
The first practical question is whether your employer participates in the DailyPay system. Without that connection, the app cannot serve its main purpose for you. I would confirm eligibility before building a bill-payment plan around early access. This is especially important if you are downloading it during an emergency and need certainty rather than another account setup step.
Catch Up on the Latest Stories
Microsoft Teams on Mobile Keeps Work Moving, If You Keep It Tidy
Groupon Turns Local Discounts Into a Marketplace, With a Catch
App of the Week: Yandex Go Makes City Errands Easier
Make Xiaomi Weather Work Harder with Smarter Settings and Daily Routines
Boomplay Turns Music Streaming Into a Daily Discovery Habit
Google Docs on Mobile Keeps the Page in Focus, Until Formatting Gets in the Way
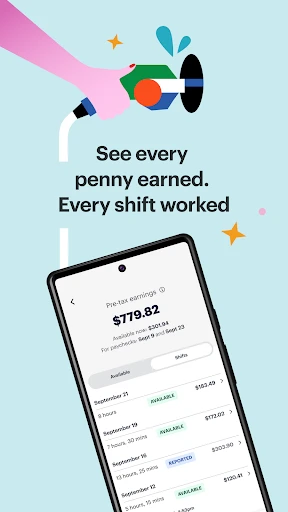
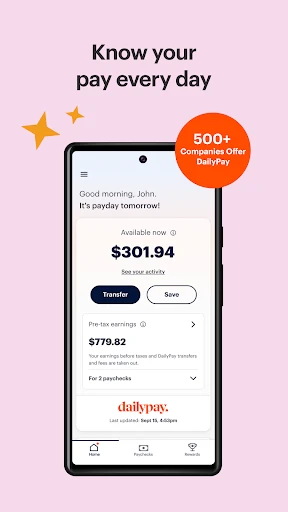
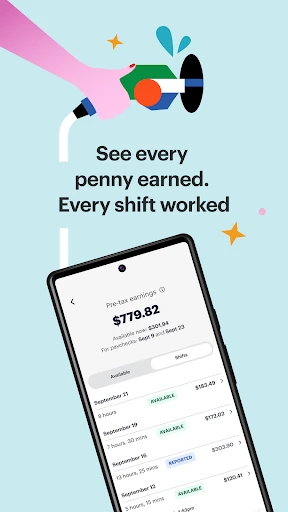
The second question is how much of your earned pay is available at the moment you need it. The amount can depend on work already recorded and processed, so the balance shown in the app may not immediately reflect a shift you have just completed. I would avoid assuming that an unprocessed shift is already spendable.
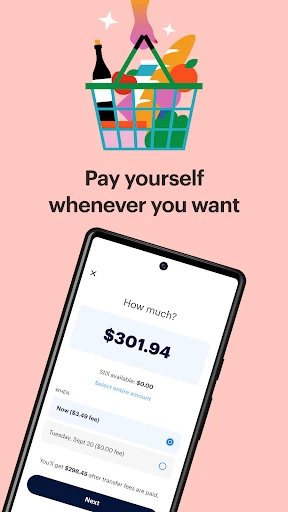
The third question concerns the delivery choice and any cost attached to it. DailyPay is free as an app, but that does not mean every way of receiving money must be treated as cost-free. Before confirming an early transfer, I would read the screen carefully and compare the available timing and fee information with the urgency of the expense. If waiting is acceptable, the regular payroll route may be the better financial choice.
This is one of the less obvious habits that makes the service safer: open the app before the crisis, understand what it displays, and learn how your employer’s payroll information appears. Familiarity matters because a rushed transfer decision is more likely to be based on panic than on a real calculation.
How the process feels in everyday use
The basic workflow is straightforward in concept. You check the amount of earned pay available, decide whether to move some of it early, and then account for the fact that the next regular paycheck will be smaller by that amount. That last step is easy to overlook. The money is not a bonus or a second paycheck; it is an earlier portion of the same earnings.
I recommend thinking in terms of a “next-payday remainder.” Before taking money, estimate what must still be covered when the normal payday arrives: rent, food, transport, subscriptions, and any automatic withdrawals. If the early transfer solves a genuine shortfall without creating a larger one later, it may be reasonable. If it only makes today feel comfortable while leaving the next week underfunded, it is probably postponing the problem.
A useful workflow is to reserve early access for expenses that protect your ability to work or maintain basic stability. For example, getting to work, keeping essential utilities active, or handling a necessary household purchase may justify considering it more than an impulse purchase. This is not a rule imposed by the app; it is the discipline I would bring to using it.
I would also keep a simple note of each early withdrawal and its purpose. That small record reveals whether the tool is helping occasionally or becoming part of every pay cycle. If the same expense repeatedly forces an early transfer, the deeper issue may be an income-and-expenses mismatch that requires a budget change, payment-date adjustment, or conversation with a provider.
The app’s current version is 37.0.0 and it supports Android 9 or later. That is useful to know before downloading, particularly if you use an older phone. I would also keep the application updated because finance apps handle sensitive account information and compatibility with payroll connections can depend on the software environment.
A realistic situation where it makes sense
Imagine that I have completed several shifts, but my scheduled payday is still a few days away. My car needs fuel for the commute, and waiting could make getting to work difficult. I open DailyPay, check what has been recorded as earned, and consider transferring only the amount needed for fuel rather than taking the largest available sum.
That limited approach is important. The benefit is not simply having access to more money; it is being able to match the amount taken to the immediate need. If I withdraw extra because it is available, I have weakened the next paycheck without gaining anything essential. If I take only what protects the commute, the service has addressed a specific timing problem.
Another reasonable use could involve a bill whose due date falls before payday. I would compare the consequences of paying early through DailyPay with the consequences of waiting, including any late charge or service interruption. The app can be useful in that comparison, but it cannot make the decision for me. The right choice depends on the actual cost and urgency of the bill.
There is also a less obvious benefit for workers with irregular schedules: earlier visibility into recorded earnings may make it easier to judge whether a short pay period is developing. I would use that visibility as a planning signal, not as permission to spend. Seeing a lower amount early gives me a chance to reduce optional spending before payday rather than discovering the shortfall after the deposit arrives.
The tradeoff is timing, not free cash
The main limitation is built into the product’s strength. Accessing wages early can relieve pressure now, but the regular paycheck later reflects that advance. Anyone who already struggles to make it from payday to payday should be especially cautious. Repeated use can create a cycle in which each payday starts with less available money, leading to another early withdrawal.
I would also avoid judging the app only by how quickly money arrives. The more important question is whether the transfer improves the whole pay period. Speed is valuable during a genuine emergency, but convenience can encourage decisions that would not survive a calm review. A short pause to identify the bill, amount, and next-payday impact is worth taking.
Employer and payroll timing can also create friction. Earned wages need to be recognized by the connected payroll system, and there may be a delay between working and seeing an amount available. For that reason, I would not use the app as the only emergency plan if the expense is time-critical. Keeping a small buffer, arranging a due-date change, or contacting the bill provider may be more dependable for recurring obligations.
Compared with a credit card, DailyPay is more directly tied to earned income and may be preferable when the need is brief and the repayment-like effect will be absorbed by the next paycheck. A credit card, however, can offer a predictable payment window and may be more suitable for a planned purchase if the user can repay it responsibly. Compared with a personal loan, early wage access is aimed at a much smaller timing gap rather than a larger, structured expense.
Compared with simply waiting for payday, the app offers flexibility but removes some of the natural protection created by a fixed pay schedule. Waiting costs nothing in terms of bringing forward earnings, so it remains the best option when the purchase is optional or the next paycheck is already tightly allocated.
Small decisions that improve the experience
I would start by identifying the exact amount needed before opening the transfer screen. This prevents the available balance from becoming the target. A written figure, even a quick note in the phone, keeps the decision connected to the bill rather than to the maximum amount displayed.
I would then look at the next payday as a complete budget, not just a deposit date. List fixed expenses first, subtract the amount already accessed, and leave room for ordinary spending. This simple calculation exposes the tradeoff that a quick tap can hide.
Another useful approach is to separate emergency use from convenience use. If the app is used because a necessary expense cannot wait, review the result afterward. If it is used because spending earlier feels nicer, consider waiting next time. That distinction helps preserve the app as a safety valve instead of turning it into a routine advance.
Finally, I would check the app after a shift or payroll update rather than repeatedly refreshing it throughout the day. Repeated checking can encourage impulsive withdrawals, while a planned check gives the information a clear purpose. The app works best when it supports a decision I have already framed, not when it becomes a source of temptation.
Who will benefit most from it
DailyPay is most useful for an eligible worker with a predictable upcoming paycheck and a short-term expense that cannot reasonably wait. It can be particularly practical when the timing of bills does not match the timing of wages, or when a small necessary cost could otherwise trigger a late fee or disrupt work.
I think it is less suitable for someone whose regular paycheck is already fully committed before it arrives. In that situation, taking money early may provide relief for one day while making the following period harder. It is also not the right tool for financing a large purchase, covering an ongoing deficit, or replacing a proper emergency fund.
People who prefer fixed, highly predictable budgeting may also find the flexibility uncomfortable. A normal payday creates a clear boundary; early access introduces more choices and more responsibility. If you know that available money tends to become spendable money in your mind, waiting for the scheduled deposit may be the healthier option.
The developer, DailyPay Inc, has built the experience around a focused financial use case rather than a broad collection of money tools. I appreciate that focus because it makes the app easy to evaluate: ask whether earlier access to earned pay solves a specific problem without damaging the next pay period. If the answer is yes, it may earn a place on your phone. If the answer is no, its central feature is unlikely to change your financial position.
My conclusion after weighing the convenience
I see DailyPay On-Demand Pay as a practical timing tool with a very clear boundary. Its best contribution is giving an eligible worker more control when earned wages and real-life expenses arrive on different schedules. The app can be genuinely helpful when used for a defined, necessary amount and followed by a realistic plan for the next payday.
Its weakness is equally clear: early access can feel like extra flexibility while quietly reducing what comes later. I would recommend it to someone facing an occasional cash-flow mismatch, provided they check availability, review the delivery details, and take only what the immediate need requires. I would not recommend relying on it as a permanent solution to expenses that exceed regular income.
For me, the deciding test is simple: does this early transfer solve a specific problem, or merely move the pressure forward? If it solves the first, the free Finance app can be a useful option. If it does the second, waiting, renegotiating a due date, or choosing a more structured financial solution is likely wiser.
Pros
- Instant access to earned wages.
- User-friendly and intuitive interface.
- Secure and reliable transactions.
- Integration with major payroll systems.
- 24/7 customer support availability.
Cons
- Fees may apply for instant transfers.
- Limited to partnered employers.
- Requires stable internet connection.
- No option for financial advice.
- Some features may be complex for novices.
Frequently Asked Questions
What is DailyPay On-Demand Pay, and how does it work?
DailyPay On-Demand Pay is a financial service that allows users to access their earned wages before the official payday. By linking your employer's payroll system with the DailyPay app, you can transfer a portion of your earned income to your bank account or debit card anytime, giving you the flexibility to manage financial needs without waiting for the standard pay cycle.
Is DailyPay safe to use for accessing my wages early?
Yes, DailyPay uses advanced security measures to protect your personal and financial information. The app employs encryption and other security protocols to ensure that your data is secure. Additionally, DailyPay is compliant with industry standards and regulations, offering users peace of mind when accessing their wages.
Are there any fees associated with using DailyPay On-Demand Pay?
DailyPay may charge a small transaction fee each time you transfer money from your earned wages to your bank account or debit card. However, the exact fee structure can vary depending on your employer's agreement with DailyPay. It is advisable to check the fee details within the app or with your HR department for accurate information.
Can I use DailyPay if my employer is not partnered with the service?
Unfortunately, you cannot use DailyPay On-Demand Pay if your employer is not partnered with the service. The app requires integration with your employer's payroll system to function correctly. If you're interested in using DailyPay, you might consider discussing the benefits with your employer and suggesting they explore a partnership.
How quickly can I access my earned wages through DailyPay?
With DailyPay, you can access your earned wages almost instantly, depending on your bank's processing times. Transfers initiated during business hours are typically completed within minutes to a few hours. This rapid access to funds makes DailyPay a convenient option for those needing immediate financial support.