Klarna | Shop now. Pay later.
- Rating
- 4.8
- Downloads
- 50,000,000+
- Age
- Everyone
Additional Info
- App Name
- Klarna | Shop now. Pay later.
- Category
- Shopping
- Package Name
- com.myklarnamobile
- Developer
- Klarna Bank AB (publ)
- Rating
- 4.8
- Version
- 25.46.299
 Analysis by Appcrazy
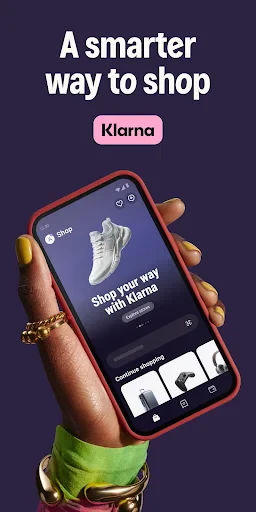
I usually open a shopping app with a very practical goal: find the item, understand the total cost, choose a payment method, and finish without losing track of what happens next. Klarna is built around that complete journey rather than only the checkout screen. It combines shopping discovery, payment management, cashback, and information about the Klarna Card in one place. After spending time with it, I see it as most useful for people who want a single dashboard for purchases and payment planning, not simply another way to browse products.
Klarna is a free shopping app from Klarna Bank AB (publ), available for Everyone and running on Android versions from 9 onward. Its scale is immediately noticeable: it has passed 50 million installs, with an average rating of 4.8 from around 1.4 million ratings and roughly 49 thousand written reviews. Those figures do not replace personal testing, but they do show that this is a mature, widely used service rather than a small experimental shopping tool.
From shopping intention to a completed payment
Starting with a real shopping task
Imagine I need a pair of headphones, a replacement kitchen item, or a gift. My first step in Klarna is not necessarily to search one familiar store and leave. The app encourages me to discover products and merchants, then move toward a purchase while keeping payment choices nearby. That is a different starting point from a retailer’s own app, where the experience is focused on one shop and its checkout.
This broader approach is convenient when I am still comparing options. I can use the app as a shopping layer before deciding where to buy, instead of opening several retailer apps and trying to remember which order belongs to which account. The trade-off is that discovery can feel less direct than visiting a store I already know. If I have a specific product page and want the shortest possible route to payment, Klarna may add an extra stop rather than remove one.
The most useful mindset is to treat the app as a purchase workspace. I am not only looking for an item; I am also checking how the transaction will be handled afterward. That distinction matters because the app’s value becomes clearer once a purchase exists. Someone who only wants occasional product browsing may find a normal retailer app simpler, while someone managing several purchases can benefit from having payment activity gathered together.
Moving from discovery to checkout
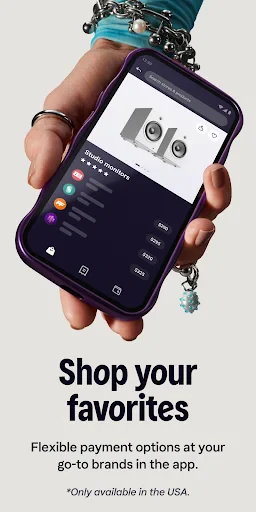
Once I have chosen something, the important question is not simply whether I can pay. I want to know which payment route is presented, what I need to do immediately, and what I will need to remember later. Klarna places payment management close to the shopping experience, so the handoff from finding an item to dealing with the transaction feels more connected than it does when shopping and banking are completely separate activities.
That connection can make a busy shopping session easier to follow. Instead of treating checkout as the end of the experience, I can think of it as the beginning of an organized record. I still need to read the terms shown at the point of purchase carefully, especially when choosing a payment option that changes when money leaves my account. The app can make payment planning more visible, but it cannot make an unaffordable purchase affordable.
Catch Up on the Latest Stories
App of the Week: Yandex Go Makes City Errands Easier
Make Xiaomi Weather Work Harder with Smarter Settings and Daily Routines
Boomplay Turns Music Streaming Into a Daily Discovery Habit
Google Docs on Mobile Keeps the Page in Focus, Until Formatting Gets in the Way
How foodpanda Is Turning Food Delivery Into an Everyday Habit
Prime Video's Strategic Surge in the Streaming Wars
One of my practical tips is to pause before confirming and check the payment schedule displayed in the app rather than relying on memory. This is a small habit, but it prevents a common mistake: focusing on the product price while overlooking the timing of the payment. Klarna is strongest when I use it as a planning tool, not as a reason to buy more than I intended.
Managing the purchase after checkout
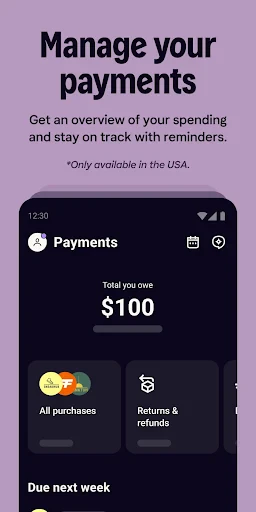
The handoff after checkout is where the app becomes more than a product finder. I can return to it to review payment activity and keep the purchase in the same environment where I discovered or arranged it. That continuity is useful when I have several orders in progress, because I do not have to reconstruct every detail from email notifications and separate retailer accounts.
There is also a psychological benefit to seeing purchases in one place: it encourages me to review what is pending instead of treating every checkout as an isolated event. For a household that buys online regularly, this can support a weekly money check. I would open the app, review recent activity, identify upcoming obligations, and then close it knowing which purchases still need attention.
However, the retailer remains an important part of the process. Product questions, delivery problems, returns, and stock issues may still depend on the merchant’s systems and policies. Klarna can help me keep track of the payment side, but I should not assume that one app replaces every conversation with the store. That separation between payment management and fulfillment is one of the first boundaries a new user should understand.
Using cashback without changing the whole routine
Cashback is another reason I might return to the app. In a good workflow, I would look for an eligible offer before shopping, read the conditions, then complete the purchase through the required path. The useful insight here is that cashback is not something I should treat as automatic simply because I opened the app. The offer details and the route used to reach the merchant matter, so I would make checking those conditions part of the shopping routine.
This creates a handoff that is easy to overlook: from an offer inside Klarna to a transaction completed with a merchant. If I jump between apps, use a different browser path, or change the order after starting, I may make the purchase harder to associate with the offer. I would not change a buying decision solely for cashback; I would use it when the product and merchant already make sense.
For me, cashback works best as a small optimization for planned purchases. It is less compelling for impulse shopping, where the promise of getting something back can distract from the total amount spent. The app gives cashback a visible place in the shopping flow, but responsible use still depends on comparing the final cost and choosing the product for its value rather than for the reward.
Where the Klarna Card fits
The app also presents information about the Klarna Card, which makes it relevant to people considering a more connected payment experience beyond individual online checkouts. I see this as a separate decision rather than an automatic next step. A user who wants a card linked to the wider Klarna experience may appreciate having the information close to shopping and payment activity.
On the other hand, someone who already has a preferred card, wants a straightforward bank app, or does not want another financial product to monitor may have no reason to adopt it. The presence of card information does not make the app a complete replacement for every banking tool. I would compare the card’s practical fit with my existing setup before treating it as part of my everyday wallet.
This is one of the app’s less obvious trade-offs. Combining shopping and payment tools reduces switching, but it also means the app can influence more stages of a purchase. That can be helpful for organization, yet it makes careful notification and account review more important. I would keep only the features that genuinely simplify my routine rather than activating every available option.
The result after the purchase
The best outcome is not merely that I bought something. It is that I know what I bought, how the payment is being handled, and where to look when I need to review it. Klarna’s main strength is this continuity between product discovery and payment follow-up. It turns a scattered process into something closer to a single timeline.
Consider a realistic evening shopping scenario. I am replacing a household item, compare a few possibilities, and choose one after checking the purchase details. I complete the transaction, then later return to the app to review the payment activity instead of searching through several inbox messages. Before my next shopping session, I can check whether the earlier purchase still needs attention. That workflow is more useful than a simple discount app because it continues to matter after the order is placed.
For a frequent online shopper, the result can be less mental clutter. I can use the app to separate “things I am considering” from “payments I need to remember,” provided I take the time to review the information rather than assuming the app will manage my budget for me. The service helps visibility; it does not remove the need for judgment.
Where the workflow breaks
The smoothest experience depends on several systems working together: Klarna, the merchant, the selected payment route, and sometimes a cashback tracking path. A problem at any handoff can make the journey feel less seamless. A retailer may have a question Klarna cannot answer, an offer may require a particular route, or a payment issue may need attention in the app while an order issue belongs with the store.
This is why I would not recommend Klarna to someone who wants the absolute minimum number of accounts and payment decisions. A direct retailer checkout may be easier for a one-off purchase. A traditional banking app may be better for someone whose priority is balances, transfers, and broader financial administration. Klarna occupies the space between shopping and payment management, and that middle ground is useful only if I actually want both sides connected.
There is also a risk of treating deferred payment as harmless because the interface makes it easy to select. My rule would be simple: if I could not comfortably afford the purchase under the displayed schedule, I would not use that route. The app can clarify timing, but the responsibility remains mine. This is the most important limitation because convenience can otherwise hide the cumulative effect of several purchases.
Another point of friction is attention. A shopping app that includes discovery, payment tools, cashback, and card information can offer more than I need in a single visit. I may open it to check one transaction and end up browsing products or offers. That is not a technical failure, but it can work against a focused budget routine. I would use notifications selectively and make payment review a deliberate task rather than a reason to browse endlessly.
How it compares with familiar alternatives
Compared with a retailer-specific app, Klarna offers a wider view across shopping and payment activity. The retailer app usually wins when I already know the store, want its loyalty features, or need detailed order support. Klarna wins when I want to compare shopping opportunities and keep payment-related activity closer together.
Compared with a standard digital wallet, Klarna is more involved in the shopping journey. A wallet is often designed to get me through payment quickly, while Klarna adds discovery, payment management, cashback, and card-related information. That broader scope can be valuable, but it also creates more choices. If speed at the register is my only goal, a simpler wallet may feel cleaner.
Compared with a bank app, Klarna is more purchase-centered and less suited to general financial administration. I would use my bank’s app for the wider picture of accounts and money movement, then use Klarna for the shopping and payment context it provides. The two can serve different purposes, but I would avoid assuming that one replaces the other.
Who will get the most from it
I think Klarna is a strong fit for people who shop online often, compare products across merchants, and want a visible place to review payment activity afterward. It is also useful for someone who likes checking cashback opportunities before planned purchases and wants information about the Klarna Card alongside shopping tools.
It may be especially helpful for a person who tends to lose track of several online orders. The benefit is not magic automation; it is having a repeatable workflow: discover, inspect the payment choice, complete the purchase, return to review, and contact the right party if something goes wrong. That structure can reduce the number of small tasks competing for attention.
I would be more cautious recommending it to someone who is trying to reduce shopping triggers, prefers paying immediately from one established account, or wants a banking app rather than a shopping-centered service. I would also skip the pay-later approach when my budget is already tight. In those situations, the app’s convenience may be less valuable than a simpler and more restrictive payment habit.
Everyday tips for using it deliberately
Before buying, decide whether you are using the app for discovery, payment organization, cashback, or card information. A clear purpose makes the session less distracting.
Review the displayed payment timing before confirming rather than estimating it from the product price.
For cashback, check the offer conditions first and follow the intended shopping path from start to finish.
After checkout, separate payment questions from delivery or return questions so you contact the correct side of the transaction.
Use the app for regular purchase reviews, but keep a wider budget view elsewhere if you need broader financial planning.
My final view after following the full journey
Klarna is more than a checkout shortcut. Its real appeal is the handoff from shopping to payment follow-up: I can discover an item, choose a payment route, review the transaction, consider cashback, and explore the Klarna Card without moving between completely unrelated services. That makes it a practical shopping companion for people who value visibility after the purchase as much as convenience during it.
At the same time, I would not use every feature automatically. The app is less suitable when I want a bare-bones retailer checkout, a traditional banking experience, or strict distance from shopping prompts. Its payment flexibility needs disciplined use, and merchant support remains part of the overall process.
With that understanding, I can recommend Klarna to a friend who shops online regularly and wants purchases and payment tasks organized in one place. The current version, 25.46.299, reflects an established app that has been available since November 1, 2018, while its free price and Everyone rating make it easy to try. My advice is to begin with one clear use case, such as reviewing purchases after checkout, and expand only when the extra tools genuinely make your routine easier.
Pros
- Flexible payment options available.
- User-friendly interface design.
- Extensive partner store network.
- Secure payment processing.
- No interest on split payments.
Cons
- Limited to partnered retailers only.
- Requires personal information for signup.
- Potential overspending temptation.
- App glitches occasionally reported.
- Customer service can be slow.
Frequently Asked Questions
What is Klarna and how does it work?
Klarna is a financial service app that allows users to shop online and pay for their purchases later. It offers various payment options, including paying in installments or delaying the full payment for up to 30 days without any interest. This flexibility is designed to enhance the shopping experience by providing financial convenience and control over your purchases.
Is Klarna safe to use for online shopping?
Yes, Klarna is considered safe for online shopping. It uses advanced security measures, such as encryption and fraud protection, to secure users' financial information. Additionally, Klarna is regulated by financial authorities in various countries, ensuring compliance with strict financial standards and consumer protection laws.
Are there any fees associated with using Klarna?
While Klarna offers many services without any fees, some features may incur charges. For example, if you choose to pay in installments, there might be interest fees depending on the retailer and the plan selected. It's important to read the terms and conditions related to each purchase to understand any potential costs involved.
What happens if I miss a payment with Klarna?
If you miss a payment, Klarna typically sends reminders and offers a grace period to settle the amount. However, continued failure to pay can result in late fees, and it could impact your credit score. It's crucial to contact Klarna’s customer support if you're having trouble making payments to explore possible solutions or extensions.
Can I use Klarna for in-store purchases?
Yes, Klarna can be used for in-store purchases at participating retailers. To use Klarna in-store, you typically need to download the app and generate a one-time card or QR code that can be scanned at the checkout. This feature provides the same flexible payment options as online shopping, making it convenient for various shopping experiences.