myWisely: Mobile Banking
- Rating
- 4.4
- Downloads
- 1,000,000+
- Age
- Everyone
Additional Info
- App Name
- myWisely: Mobile Banking
- Category
- Finance
- Package Name
- com.adp.wiselymobile
- Developer
- ADP, INC.
- Rating
- 4.4
- Version
- 25.23.0
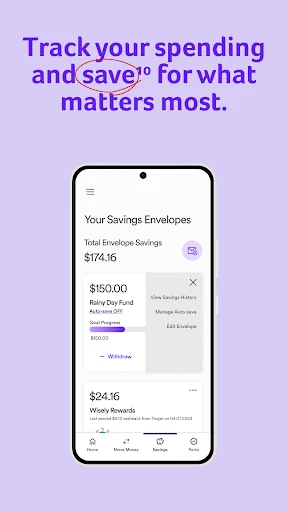
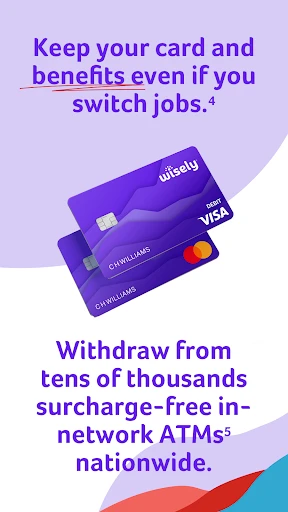
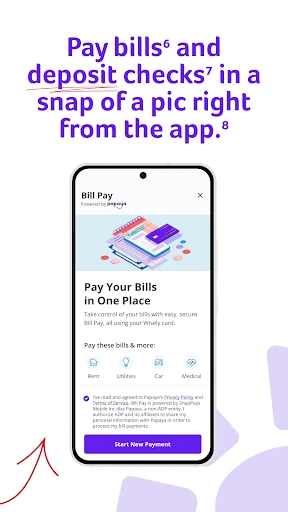
 Analysis by Appcrazy
My first impression of myWisely: Mobile Banking was that it is built around a very practical question: what do I need to know about my money today? Developed by ADP, INC., this free finance app is aimed at people who use a Wisely account or card and want a more convenient way to keep an eye on incoming pay, spending, and saving habits. It is available to users rated Everyone, and its store summary, “Get paid. Track spend. Save more,” captures the basic rhythm of using it without telling the whole story.
What makes it interesting is not novelty in the usual app sense. It is not something I open for entertainment or exploration. Its value depends on whether it becomes a quiet part of my routine: checking after a purchase, confirming that money arrived, and looking at my balance before making another decision. That makes the first week important, but the real test is whether the app remains useful after the initial setup and curiosity have disappeared.
From first-week convenience to a lasting money habit
I find the shift from early convenience to a lasting habit comes down to making each check answer a real question, rather than opening the app automatically. A useful next step is to connect a review to a routine you already have, such as planning a grocery run or checking your money after payday. That makes the habit easier to keep, while also bringing up an important question: how comfortably can different people use the app in everyday situations?
The first week feels focused rather than overloaded
During the first few days, the strongest appeal is the directness of the experience. A banking app can easily become cluttered with menus, offers, account notices, and financial terminology. myWisely presents itself around everyday money management instead. I can approach it with a specific purpose, such as checking whether a payment has arrived or seeing how much spending room remains, rather than treating it like a complete financial planning suite.
That focus matters for people who do not want to maintain spreadsheets or switch between several services. If my main need is to stay aware of money connected to my Wisely account, a dedicated mobile view is more approachable than manually checking statements or waiting until the end of the month to understand what happened. I found that the app makes short check-ins feel more realistic because the task is small enough to repeat.
The app is free, which removes one obvious barrier to trying it. It also has a mature presence in the finance category, with over a million installs and an average rating of 4.4 from around 29 thousand ratings. Those figures do not guarantee that every user will enjoy the same experience, but they do suggest that the app has reached a substantial audience rather than being an obscure experiment.
What I would do before relying on it
I would not treat the first login as the end of setup. The useful habit begins when I decide exactly when the app belongs in my day. For example, I might check it after pay arrives, review recent spending before a grocery trip, and glance at the balance before using the card for a larger purchase. Those moments are more useful than opening the app repeatedly without a question in mind.
Catch Up on the Latest Stories
Microsoft Teams on Mobile Keeps Work Moving, If You Keep It Tidy
Groupon Turns Local Discounts Into a Marketplace, With a Catch
App of the Week: Yandex Go Makes City Errands Easier
Make Xiaomi Weather Work Harder with Smarter Settings and Daily Routines
Boomplay Turns Music Streaming Into a Daily Discovery Habit
Google Docs on Mobile Keeps the Page in Focus, Until Formatting Gets in the Way
A small but important tip is to separate checking from judging. The app can show me what has happened, but it cannot automatically make every spending decision sensible. In my first week, I would use the information to establish a baseline: which transactions I recognize quickly, how often I need to check, and whether the balance gives me enough context to avoid surprises. That approach turns the app from a passive display into a simple decision tool.
I would also pay attention to how quickly I can reach the information I use most. If I need to move through several screens every time, that friction will matter more than a polished first impression. A finance app earns its place through repeated low-effort actions, so the best early test is not how attractive it looks once, but whether I still want to use it when I am busy or distracted.
Useful for a realistic everyday situation
Imagine I receive money before a weekend and need to divide it between essentials, transport, and discretionary spending. Instead of guessing from memory, I can open myWisely, check the available balance, and review recent activity before deciding whether a purchase fits. Later, after paying for several small items, I can check again rather than assuming those amounts are insignificant. This is where the app’s practical value becomes clearer: it shortens the distance between spending and awareness.
That workflow is especially helpful for someone whose income or expenses make frequent balance checks sensible. It can also suit a person who is trying to stop relying on a vague mental estimate. I would not call it a replacement for a detailed budget, but it can support the part of budgeting that many people skip: looking at real activity often enough to notice a pattern while there is still time to respond.
Why the second and third month matter more
After the first month, the novelty fades. I am no longer learning where things are, and the question changes from “Can this app show me my money?” to “Does opening it regularly improve my decisions?” In my experience, the answer depends on whether the app fits an existing routine. If I only use it when I am already worried about my balance, it becomes a damage-control tool. If I check it at predictable moments, it becomes maintenance that prevents some of that worry.
The recurring value comes from repetition. A single balance view tells me very little about my habits, while regular checks can reveal whether small purchases are accumulating or whether my available money is lower than expected. I do not need to turn every transaction into a financial analysis. A quick review can be enough to keep my mental picture close to reality.
One non-obvious advantage of a focused app like this is that it may be easier to sustain than a full budgeting platform. Detailed budgeting tools can ask me to create categories, set targets, reconcile accounts, and maintain a larger system. That depth is valuable for some people, but it also creates more work. myWisely makes more sense when the priority is staying connected to the account rather than building a complete household financial model.
Where it fits among the usual alternatives
Compared with checking through a general bank app, myWisely has a narrower purpose. A traditional bank application may be better if I manage several accounts, need extensive transfer tools, or want a broad view of loans, savings, and other products in one place. A budgeting application may be better if I want detailed categories, long-term goals, or reports across multiple financial institutions.
On the other hand, those alternatives can feel excessive when I simply want a clear connection to my Wisely money. A spreadsheet gives me control but demands manual effort. A general-purpose budgeting service may require more organization than I am willing to maintain. The trade-off is straightforward: myWisely is more convenient for focused account awareness, while broader tools are more capable for people who want financial planning beyond that central use.
I would therefore avoid choosing it because it sounds like a universal banking replacement. I would choose it because its narrower role matches my needs. That distinction is important for long-term satisfaction. The app can be useful every month without being the only financial tool I use.
The maintenance burden is low, but not zero
The app’s maintenance burden mainly comes from the discipline of checking it and interpreting what I see. No mobile banking tool can create a good habit on my behalf. If I ignore transactions, forget my own recurring expenses, or use the displayed balance without considering pending activity and timing, the app will not prevent poor decisions. Its information is useful only when I make room for it in my routine.
I would keep the routine deliberately short. A weekly review could involve checking recent activity, confirming that expected money is present, and noting whether spending is moving faster than planned. Around a pay cycle, I would make the review more deliberate. The goal is not to spend ten minutes searching through every screen; it is to make a few decisions while the information is fresh.
There is also a personal security habit to maintain. Because this is a finance app, I would use a strong device lock, avoid leaving the account open on a shared phone, and be cautious when reviewing sensitive information in public. Those steps are not special features of myWisely, but they are part of using any mobile money service responsibly. Convenience should not lead me to become careless with access.
What can create fatigue over time
The first source of fatigue is repetition without insight. If I open the app only to see the same balance and never change a decision, the routine can start to feel pointless. That does not necessarily mean the app has failed; it may mean I need a clearer purpose for each check. Still, an app that depends on repeated attention must make those checks feel worthwhile.
The second issue is scope. Users who expect advanced planning tools may find a focused account companion too limited for their ambitions. I would not use it as my only solution if I needed a consolidated picture of multiple accounts, a detailed debt strategy, or a highly structured budget. In those cases, a broader financial tool would likely earn more space in my routine, even if it took longer to maintain.
The third source of fatigue is the emotional side of money. Frequent checking can reassure me, but it can also encourage anxious refreshing if I do not have a clear reason to look. I get better results when I decide in advance what I am checking: an expected payment, a recent purchase, or the amount available for a planned expense. That small boundary keeps the app practical instead of turning it into a source of constant worry.
Version, accessibility, and everyday practicality
The current version is 25.23.0, and the app supports devices running Android 6.0 or later. That broad compatibility is useful for people who do not replace their phone frequently. I would still judge the experience on the particular device I own, especially if it is older, because finance apps need to feel dependable when I am checking something quickly.
The Everyone content rating also makes the app broadly approachable from an age-classification perspective. That does not mean every financial decision is suitable for every household, of course. A younger user may still need guidance about spending, account access, and privacy. The rating simply reflects that the app itself is presented for a general audience rather than being restricted to adults by its content classification.
For readers deciding whether to install it, the key question is not whether it has every banking feature. The better question is whether the account it supports is already part of your financial life. If it is, the app has a clear reason to exist. If it is not, installing it merely to browse may not create any lasting benefit.
Who will keep using it after the novelty fades?
I think it is best suited to people who want frequent, uncomplicated awareness of their Wisely money. That includes someone who wants to check whether funds are available before spending, someone trying to become more deliberate about small purchases, and someone who prefers a dedicated mobile experience over paper records or occasional desktop checks.
It is less suitable for a user searching for a complete financial command center. If I manage several institutions, need extensive investment information, or enjoy building detailed monthly plans, I would pair it with another tool or choose a broader alternative. The app’s strength is not breadth; it is the possibility of making a small but useful money check easy enough to repeat.
Another practical consideration is personal motivation. If I already review my account consistently through another reliable method, myWisely may not change much. The benefit is greatest when it replaces a weaker habit, such as guessing, postponing checks, or discovering spending only after the money is gone. In that situation, even a simple recurring glance can be meaningful.
My long-term verdict
After the initial appeal wears off, I see myWisely as a practical finance companion rather than a full budgeting system. Its lasting value comes from being close at hand when I need to check money connected to my Wisely account. The free price makes trying it easy, and the focused purpose means I do not have to build a complicated process before receiving some benefit.
My recommendation is conditional but positive: use it if you want a lightweight way to monitor pay, spending, and saving-related decisions in the flow of ordinary life. Give it a scheduled role, such as a quick review after income arrives and another before a larger spending period. That is where the app can earn permanent space instead of becoming another icon I forget.
I would skip it as a primary solution if I need advanced planning across many accounts or if I already have a stronger system that I maintain consistently. For everyone else, its appeal is refreshingly modest. It does not need to transform my finances to be useful. It only needs to help me look at the right information often enough to make fewer decisions by guesswork. That dependable, repeatable check is the real reason to keep it installed.
With around 12 thousand reviews and a 4.4 average, it has clearly attracted ongoing attention from users, but my final judgment rests more on fit than popularity. myWisely works best when I treat it as a habit-supporting tool: open it with a purpose, act on what I learn, and close it. Used that way, it can remain useful well beyond the first week.
Pros
- User-friendly interface for easy navigation.
- Instant notifications for transactions.
- No monthly maintenance fees.
- Access to financial insights and tips.
- Secure login with biometric options.
Cons
- Limited customer service hours.
- No check deposit feature.
- Requires stable internet connection.
- Some features are US-specific.
- Limited support for international transfers.
Frequently Asked Questions
What features does myWisely offer for managing finances?
myWisely provides a range of features designed to help users manage their finances efficiently. These include budgeting tools, spending insights, and automatic savings options. Users can also receive real-time notifications for transactions and account updates, ensuring they stay informed about their financial status at all times.
Is myWisely secure for online banking?
Yes, myWisely implements advanced security measures to protect users' financial data. The app uses encryption technology to safeguard information and offers two-factor authentication for an added layer of security. Users can have peace of mind knowing their sensitive data is well-protected while using the app.
Can I access myWisely internationally?
myWisely can be accessed internationally, but certain features may be limited depending on the user's location. It's important to check with the app's support team or terms of service for specific details about international usage, as some functionalities might not be available outside the United States.
Are there any fees associated with using myWisely?
While myWisely itself is free to download and use, there may be fees associated with certain transactions or services, such as out-of-network ATM withdrawals or expedited funds transfers. Users should review the app's fee schedule to understand any possible charges that could apply to their account activities.
How can I contact myWisely customer support?
Users can contact myWisely customer support through several channels, including email, phone, and live chat within the app. The support team is available to assist with any questions or issues related to account management, technical difficulties, or other concerns. Response times may vary, but the team is committed to providing timely assistance.