PayPal POS (ex Zettle)
- Rating
- 3.6
- Downloads
- 1,000,000+
- Age
- Everyone
Additional Info
- App Name
- PayPal POS (ex Zettle)
- Category
- Business
- Package Name
- com.izettle.android
- Developer
- PayPal Mobile
- Rating
- 3.6
- Version
- 8.18.0
 Analysis by Appcrazy
I approached PayPal POS as a small-business checkout tool rather than as another general PayPal wallet. That distinction matters. This is a free business app from PayPal Mobile, designed around point-of-sale work, so its value depends less on casual payments and more on whether it fits the way you actually sell, record transactions, and manage customer-facing moments.
My first impression is that it makes sense for a seller who wants to move away from a cash-only setup without jumping immediately into a large retail system. It is aimed at everyday commerce: taking a payment, keeping the checkout process organized, and using a familiar financial brand as the foundation. The experience feels more practical than flashy, which is appropriate for an app that may be used while serving customers rather than browsing at leisure.
PayPal Mobile released it on May 3, 2021, and the current version is 8.18.0. It belongs to the Business category, carries an Everyone age rating, and can run on devices using Android 8.1 or later. Those details make it accessible to many existing phones and tablets, although I would still check the device used at the counter before committing a busy shop to it.
What I looked at before trusting it with a checkout
Trust is the central question with any point-of-sale app. A checkout tool is not just a calculator: it sits close to payments, customer interactions, business records, and account access. In my view, PayPal POS benefits from being developed by PayPal Mobile, a name many sellers already recognize, but recognition alone should not replace careful setup.
The app is free to install, which lowers the barrier to testing it. That does not mean every part of operating a payment business is free, and I would not treat the download price as the complete cost picture. Before using it with real customers, I would review the payment terms presented during account setup, confirm how transactions are handled, and make sure the person responsible for the business understands which account is connected.
The public response is mixed rather than universally enthusiastic. PayPal POS has an average rating of 3.6 from around 43 thousand ratings, with roughly 1.1 thousand written reviews. I read that kind of score as a reason to test the workflow personally, not as an automatic rejection. Payment apps can feel excellent on one device and frustrating in a different shop because the problems often appear during login, connectivity changes, account switching, or a rush of customers.
Its reach is nevertheless substantial, with more than one million installs. That makes it easier to find people who have encountered the app, but popularity does not answer the questions that matter most to a particular seller: Can staff use it without confusion? Can the owner keep control of access? Does the checkout routine remain clear when several customers are waiting?
Catch Up on the Latest Stories
Microsoft Teams on Mobile Keeps Work Moving, If You Keep It Tidy
Groupon Turns Local Discounts Into a Marketplace, With a Catch
App of the Week: Yandex Go Makes City Errands Easier
Make Xiaomi Weather Work Harder with Smarter Settings and Daily Routines
Boomplay Turns Music Streaming Into a Daily Discovery Habit
Google Docs on Mobile Keeps the Page in Focus, Until Formatting Gets in the Way
Account ownership deserves attention from the beginning
I would set up the account with the business owner’s details and treat staff access as a separate operational concern. A common mistake with small businesses is connecting a payment tool to one employee’s personal phone or email simply because that person performs the first setup. That can create unnecessary friction when the employee leaves, changes devices, or is unavailable during an urgent account check.
Before taking a first payment, I would write down who controls the main account, where recovery messages go, and which device is authorized for daily use. I would also avoid sharing a personal password among several workers. Even if a small team trusts one another, shared access makes it harder to understand who performed an action and harder to remove one person’s access later.
This is one of the less obvious strengths of approaching the app carefully: the checkout routine becomes part of the business’s internal controls. The app cannot fix an informal staff process by itself. The owner still needs a simple rule for who can open the app, who can handle corrections, and who reviews the day’s activity.
Permissions and visible choices should be checked, not assumed
When I install a payment app, I pay attention to every permission request and to the explanations shown before granting access. I do not assume that a business app needs unrestricted access to everything on a phone. If PayPal POS asks for a permission, I would read the reason presented in context and decide whether it is necessary for the intended checkout workflow.
Permission choices are especially important on a shared device. A tablet used at a market stall may be handled by several people, while a phone used by the owner may contain personal messages, photos, and other accounts. Keeping the point-of-sale device limited to business activity reduces accidental exposure and makes it easier to notice unusual prompts.
I would also review the app’s account and privacy controls after installation rather than treating setup as a one-time event. Mobile apps change over time, and the current version is 8.18.0. A later update may alter a screen, introduce a new prompt, or change where a setting appears. The practical habit is to check the controls whenever the app changes significantly, especially before a major sales period.
Where sensitive moments happen during everyday use
The sensitive point is not only the payment itself. It begins when a seller signs in, continues when a customer is waiting at the counter, and may extend into receipts, transaction records, support conversations, and device notifications. I would avoid leaving the app open on a screen that exposes business activity when the tablet is unattended.
For a small weekend bakery, for example, I can imagine using a dedicated tablet at a market table. One person serves the queue while another prepares orders. In that situation, the useful discipline is to keep the checkout device facing the seller, confirm the transaction before moving to the next customer, and avoid discussing account details aloud. At the end of the market, the owner should review the device and account routine rather than simply putting the tablet in a drawer.
That scenario also reveals a trade-off. A simple mobile checkout can be convenient because it does not require a large fixed register, but the smaller setup puts more responsibility on the seller. Battery life, connectivity, screen visibility, and staff habits become part of payment reliability. PayPal POS may simplify the hardware side, yet it cannot remove the need for a backup plan when a device is unavailable or the connection is unstable.
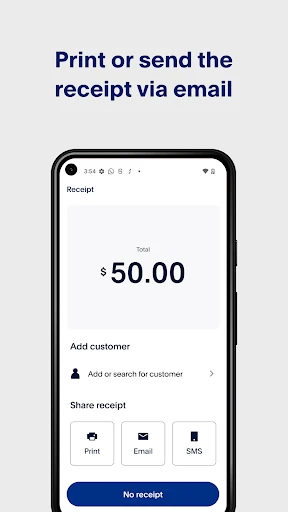
I would run several test transactions before opening to the public. The goal is not merely to see whether a payment goes through. I would watch how quickly a new worker understands the screen, whether the confirmation is obvious, whether the receipt choice is clear, and what happens when the seller pauses or needs to correct an entry. These are the moments that determine whether the app feels safe under pressure.
How it compares with familiar alternatives
Compared with a traditional cash register, PayPal POS offers a more connected mobile approach and avoids making the counter revolve around a bulky fixed system. That can suit a market seller, mobile service provider, pop-up shop, or small operation that changes location. The compromise is that a phone or tablet becomes part of the business infrastructure, so the owner must protect it and keep it ready.
Compared with a full retail platform, the appeal is likely simplicity. A larger system may be better for a business that needs extensive inventory control, complex staff permissions, detailed reporting, or several locations. I would not choose a lightweight point-of-sale app merely because it is free if the business has already outgrown basic checkout needs.
Compared with a generic card reader or a banking app, the point-of-sale focus is more relevant to sellers who need a repeatable customer-facing routine rather than an occasional transfer. The right choice depends on the business model. Someone who invoices clients and rarely sells face to face may find a dedicated invoicing workflow more suitable. Someone selling directly to customers may appreciate having a checkout-oriented tool instead.
The important comparison is not “which app has the longest feature list?” It is “which system leaves the fewest opportunities for mistakes in this shop?” A small seller should choose the tool that staff can operate consistently, that the owner can supervise, and that does not create unnecessary exposure on a shared device.
Practical controls I would use with a small team
I would begin with one clearly identified business device and one owner-controlled account. Then I would create a short opening routine: inspect the device, confirm the app is ready, check that the correct account is active, and make sure the screen is visible only to the seller. This takes little time but prevents a surprising number of avoidable errors.
For staff training, I would demonstrate the complete path rather than only the successful payment. Each worker should know how to recognize a completed transaction, what to do if the customer asks for confirmation, and when to stop and call the owner instead of improvising. The owner should handle account changes and sensitive recovery steps personally.
At closing, I would compare the day’s physical activity with the records available in the business account and note anything unusual while the details are fresh. I would not rely on memory after a busy shift. This is a useful workflow even for a very small seller because it separates normal checkout work from later review.
Another practical tip is to keep personal use away from the point-of-sale device. Installing unrelated apps, sharing the tablet with family members, or using it for casual browsing makes it harder to maintain a clean business environment. A dedicated device costs more than using an existing phone, but it can make permissions, notifications, and staff handoffs easier to control.
Who will get the most from it
I see PayPal POS as a good candidate for independent sellers who want a mobile business checkout and are willing to manage the surrounding account and device habits themselves. It may fit a craft seller at events, a small food stand, a service provider taking payment on location, or a new shop testing a straightforward sales process.
It is also appealing for someone who wants to start cautiously. Because the app itself is free and the age rating is Everyone, the initial step is relatively approachable. I would still treat the first week as a trial period: use it with a limited workflow, train the people who will touch it, and identify any confusing step before relying on it during the busiest hours.
The app is less convincing for a business that needs a sophisticated retail back office. If you manage many products, several locations, multiple roles, or complicated stock movement, a more specialized system may justify its extra cost and complexity. Likewise, a seller who dislikes handling account security, device maintenance, or mobile connectivity may be happier with a conventional register and professional setup.
Questions I would settle before going live
Would I use it on an old phone? Only after checking that the device meets the minimum operating-system requirement and performs reliably in real conditions. Android 8.1 is the minimum OS listed for the app, but compatibility alone is not the same as a comfortable checkout experience. A slow or damaged device can turn a simple transaction into an awkward customer interaction.
Would I let every employee manage the account? No. I would separate everyday checkout duties from owner-level account control. Staff can be trained to use the operational flow, while recovery details, account changes, and unusual transaction questions remain with a responsible manager.
Should I install it on my personal phone? It can be convenient, but I would prefer a dedicated business device whenever the phone contains private information or is used by several people. A dedicated device makes the boundary between personal and business activity much clearer.
Is the free price enough to decide? No. It is a useful reason to test the app, not proof that it is the cheapest complete solution. I would examine the terms shown for the payment services involved and compare the total operating fit with alternatives before moving all sales onto it.
What should I do if the workflow feels confusing? I would not wait until a queue forms. I would pause, run controlled tests, simplify the staff routine, and consider a different point-of-sale system if the confusion remains. In payment handling, familiarity and consistency are more valuable than forcing a tool to work because it was easy to download.
My cautious verdict
After looking at PayPal POS through the lens of trust and control, I find it most persuasive as a practical starting point for small, mobile, or straightforward sellers. PayPal Mobile gives it a recognizable foundation, and the app’s free availability makes experimentation realistic. Its business focus is clearer than that of a general payment wallet, which is important when the goal is repeatable selling rather than occasional transfers.
My recommendation comes with conditions. I would install it on a suitable device, test the full checkout routine, review every permission and account choice, and keep owner access separate from staff use. I would also compare its workflow with a larger retail platform before adopting it for a complex operation.
The best reason to choose PayPal POS is not the brand name or the free download; it is whether your team can use it clearly, consistently, and with sensible account boundaries. For a small seller who values a mobile setup and is prepared to take responsibility for those details, it is worth testing. For a business that needs deep retail controls or wants a completely managed register environment, I would look elsewhere.
Overall, I would describe it as a useful candidate rather than an automatic answer. The 3.6 average rating suggests that real-world experiences vary, so I would let a controlled trial decide. If the app fits your sales routine and your security habits are disciplined, it can be a reasonable business checkout companion. If it introduces more uncertainty than it removes, a more specialized alternative will be the better investment.
Pros
- Easy integration with PayPal accounts.
- User-friendly interface for quick transactions.
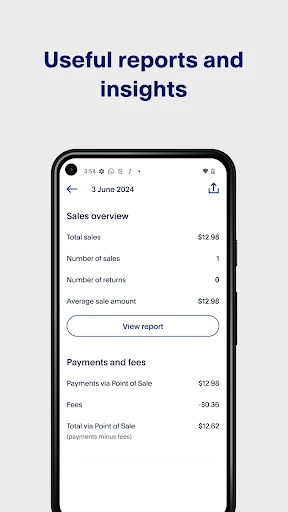
- Offers detailed sales analytics.
- Supports various payment methods.
- Compatible with multiple devices.
Cons
- Limited offline functionality.
- Higher transaction fees than some competitors.
- Occasional app stability issues.
- Customer support can be slow.
- Requires internet for full features.
Frequently Asked Questions
What is PayPal POS and how does it work?
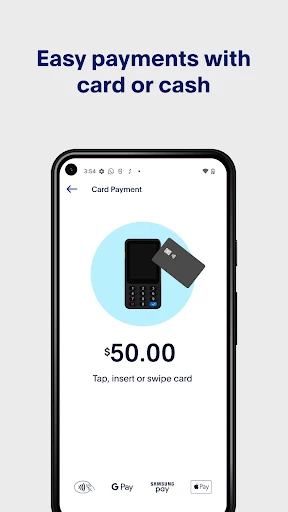
PayPal POS, formerly known as Zettle, is a point-of-sale system that allows businesses to accept card payments in person. It integrates seamlessly with PayPal, enabling merchants to manage sales, inventory, and customer data all in one place. The app connects to a card reader to facilitate transactions and provides detailed analytics and reporting features to help businesses track performance.
Is PayPal POS compatible with my devices?
PayPal POS is compatible with most iOS and Android devices. However, it is essential to ensure that your device meets the minimum operating system requirements specified by PayPal. Additionally, the app requires a PayPal account to function, and you may need specific hardware like a card reader, which connects via Bluetooth to your smartphone or tablet.
What fees are associated with using PayPal POS?
PayPal POS charges a transaction fee for each payment processed, typically a percentage of the sale amount plus a fixed fee. These fees may vary depending on the country and the type of transaction (e.g., credit card, debit card). It's crucial to review PayPal's current fee structure on their official website or within the app to understand the costs involved before getting started.
How secure is PayPal POS for handling transactions?
PayPal POS employs advanced security measures to protect sensitive data during transactions. It uses encryption and tokenization to secure card information and complies with PCI DSS standards, ensuring high-level security. Regular updates and monitoring also help protect against fraud and unauthorized access, making it a reliable option for businesses looking to handle payments securely.
Can I use PayPal POS to manage inventory and customer data?
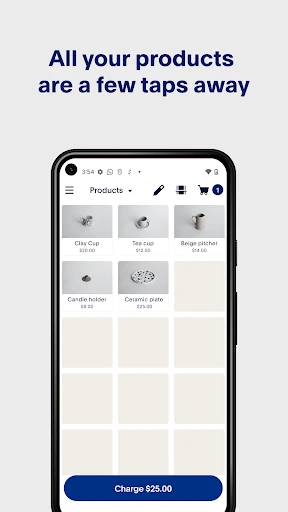
Yes, PayPal POS provides robust tools for managing inventory and customer data. The app allows you to track stock levels in real-time, set alerts for low inventory, and organize products into categories. Additionally, it helps you manage customer information, track purchase history, and offer personalized service, enhancing customer relationships and business efficiency.