Piggy Bank Allowance - Bomad
- Rating
- 4.4
- Downloads
- 50,000+
- Age
- Everyone
Additional Info
- App Name
- Piggy Bank Allowance - Bomad
- Category
- Parenting
- Package Name
- app.bomad
- Developer
- Graeme P
- Rating
- 4.4
- Version
- 2.0.266
 Analysis by Appcrazy
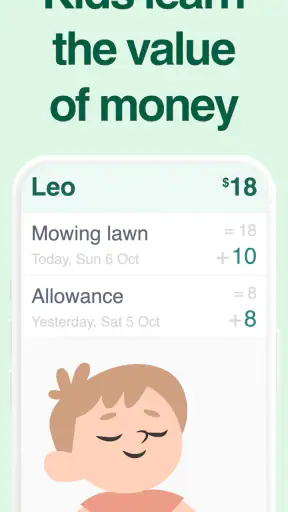
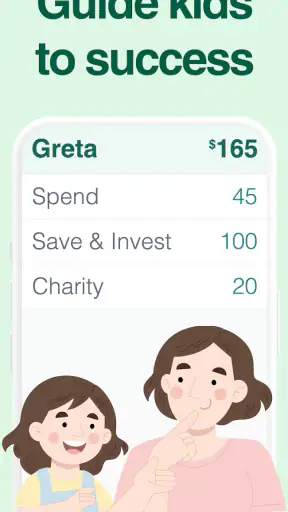
I found Piggy Bank Allowance - Bomad most useful when I treated it as a conversation tool rather than a replacement for real money. It is a free parenting app from Graeme P that helps families record allowances and divide virtual pocket money between saving and spending jars or pots. That sounds simple, and it is, but the simplicity can be valuable: children can see where their allowance is going without needing a bank account, a payment card, or a complicated financial service.
After using it, my impression is that its strongest quality is visibility. A child can connect an agreed chore or allowance with a clear result, while a parent has a shared place to discuss what is being saved and what can be spent. The app is aimed at Everyone, runs on Android devices using at least OS 9, and is free to start. Optional in-app purchases range from $1.99 to $29.99 per item, so I would still check the purchase screen carefully before handing the device to a child.
What Piggy Bank Allowance is really useful for
The app sits in a helpful space between a paper chart and a full financial app. A paper chart can show whether a chore was completed, but it becomes awkward when money is divided into several goals. A banking app may show actual balances, yet it can introduce cards, transfers, account access and adult financial information that are not appropriate for every family. Piggy Bank Allowance keeps the focus on the allowance conversation and the child’s choices.
I would use it with a child who is beginning to understand that receiving money does not mean spending everything immediately. The saving and spending jars or pots give parents a practical way to explain delayed gratification. Instead of saying “save some of it,” I can agree on a visible split and then revisit it when the child wants a toy, a treat or another small purchase.
The app also works for families who do not want to give a child physical cash every week. Virtual pocket money can represent an agreed amount while the parent remains responsible for the actual payment. That distinction matters. The balance inside the app should be treated as a teaching record unless the family separately agrees how and when it becomes real money.
One everyday example is a Saturday allowance. I might sit with my child, mark the allowance, and put one portion into spending and another into saving. When the child asks for something during the week, we can look at the spending pot together. If there is not enough, the decision becomes a lesson in waiting, choosing a cheaper alternative or saving longer, rather than an argument based on a vague promise.
That workflow is more useful than it first appears because it gives the child a stable reference point. The parent does not have to remember every verbal agreement, and the child can see why the available amount changed. I would still keep the discussion age-appropriate: younger children may need the jars explained with physical examples, while older children may be ready to talk about goals, trade-offs and whether an allowance is linked to chores.
Catch Up on the Latest Stories
Microsoft Teams on Mobile Keeps Work Moving, If You Keep It Tidy
Groupon Turns Local Discounts Into a Marketplace, With a Catch
App of the Week: Yandex Go Makes City Errands Easier
Make Xiaomi Weather Work Harder with Smarter Settings and Daily Routines
Boomplay Turns Music Streaming Into a Daily Discovery Habit
Google Docs on Mobile Keeps the Page in Focus, Until Formatting Gets in the Way
A clear starting point for families
The store short description calls it Piggy Bank Allowance, and that is a fair description of the app’s role. It is not trying to be a complete family banking platform. Its appeal comes from making a small household system easier to maintain. If your current method is a notebook that gets lost, a whiteboard that is rarely updated or a string of promises nobody remembers, this is the kind of focused tool that may bring consistency.
I like that the basic idea is understandable without a long explanation. A parent can introduce the app by asking three questions: what has been earned, what is available to spend and what is being kept for later? Those questions remain useful even if the child is too young to manage money independently.
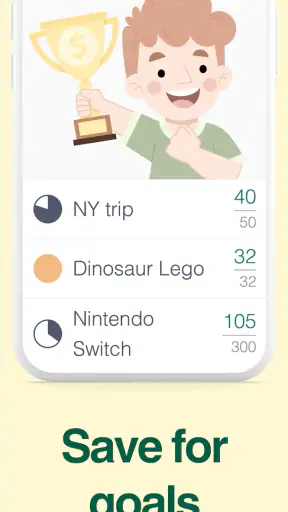
There is also a useful emotional benefit. Saving becomes visible progress instead of an instruction from an adult. A child who watches a goal grow may be more willing to wait, especially when the target is concrete. The app cannot create motivation by itself, but it can make the result of a decision easier to see.
Controls and trust in ordinary use
When I assess a parenting app, I look first at the boundary between a child-facing record and a real financial account. Piggy Bank Allowance is best understood on the record-keeping side of that boundary. That makes it less intimidating for families who want to teach money habits without connecting a child to banking infrastructure.
At the same time, parents should decide who is allowed to change the figures and when. The app can support an agreed routine, but it should not become the only source of truth if several adults handle allowances. I would establish a simple household rule: update the balance together, explain any correction immediately and avoid changing a child’s saved amount silently. That is not a technical feature; it is a practical control that protects trust.
I would also review any visible purchase prompts before letting a child use the app alone. The app is free, but it includes optional purchases priced from $1.99 to $29.99 per item. That does not automatically make it unsuitable for children, yet it does mean the adult should understand the device’s purchase protections and keep payment approval under adult control.
This is one of the app’s important trust moments. A child may see the allowance as their money, while an in-app purchase is a separate transaction involving the parent’s payment method. I would explain that difference clearly and use the device’s existing approval settings rather than assuming the child will understand it naturally.
Data-sensitive moments deserve attention
The most sensitive information in an allowance tracker is not always a bank balance. It can be the child’s name, age, habits, reward history or the family’s routine. Even a simple record can reveal when allowances are given, how much a child receives and what goals matter to them. I would therefore enter only the details needed to make the household system work.
Before setting up a profile, I would read the app’s current privacy and permission screens directly on the device. Those screens are the right place to check what access is requested, what choices are available and whether anything can be declined without affecting the core allowance workflow. I would not assume that a parenting label alone tells me how information is handled.
The same caution applies when a child uses a shared tablet or a parent’s phone. A visible balance may be harmless in one home but private in another. If the device is shared with siblings, I would avoid leaving the allowance screen open and would decide whether each child should see the others’ amounts. The app can support a family discussion, but privacy between siblings may require household rules beyond the app itself.
Notifications and purchase prompts are another point where user choice matters. I would keep only the alerts that help the family remember its routine. If a reminder creates pressure or becomes background noise, turning it off may make the system more effective. A money lesson should feel deliberate, not like a stream of demands from a device.
How to give children agency without giving away control
The best way to use this app is to give a child meaningful choices inside firm boundaries. I might let the child decide how much of an agreed allowance goes into saving and how much goes into spending, while keeping the total allowance and real-world payment under adult supervision. That creates agency without confusing virtual tracking with unrestricted access to money.
Another useful approach is to create a short review ritual. Once a week, I would ask the child to explain one recent choice: what they saved, what they spent or why they changed a goal. I would avoid turning every entry into a test. The purpose is to help the child notice patterns, not to make the app feel like homework.
A less obvious benefit of the jars or pots is that they can separate different kinds of decisions. Spending money can be available for small wants, while saving money can represent a larger target. If a child repeatedly moves everything into spending, that is not necessarily a failure; it may show that the saving goal is too distant or not personally meaningful. I would adjust the goal or the split together instead of using the app to enforce an adult’s preferred answer.
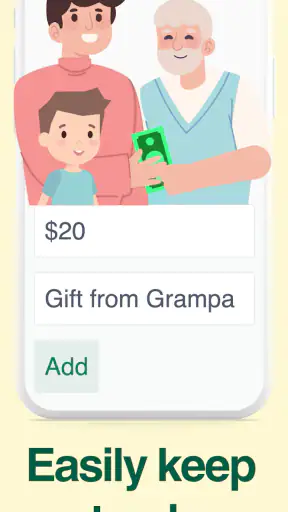
For older children, the app can also open a conversation about irregular money. A birthday gift, a one-off reward or a contribution toward a larger purchase can be discussed separately from the normal allowance. I would label the reason in the family’s routine, if the app allows the relevant record, so the child does not assume every increase is permanent. The important point is consistency: the child should know why a balance changed.
Where it compares well with familiar alternatives
Compared with cash in a physical piggy bank, the virtual approach is easier to review and less likely to disappear under a bed. It also makes separate saving and spending categories easier to maintain. Cash still has an advantage for younger children who learn through touching and counting coins, so I would not remove physical money if that experience is helping them understand quantity.
Compared with a paper allowance chart, the app offers a more focused home for the balance and the jar concept. Paper remains better for a chore checklist that the whole family can see at a glance. If your main problem is tracking tasks rather than tracking money, a dedicated family planner may be a better fit.
Compared with a child bank account or prepaid card, Piggy Bank Allowance is less suitable when the goal is independent real-world spending. It does not replace the decisions involved in opening an account, managing a card or teaching a child how a transaction appears in a financial statement. Its strength is the preparation stage: learning to divide, wait and choose before those decisions carry more serious consequences.
That distinction is important for expectations. I would recommend it to a parent who wants a controlled allowance framework, not to someone looking for automatic transfers, card controls or a complete family finance dashboard. Choosing the simpler tool can be wiser when the child’s immediate need is understanding the idea of saving rather than operating a financial product.
Practical friction I noticed in the concept
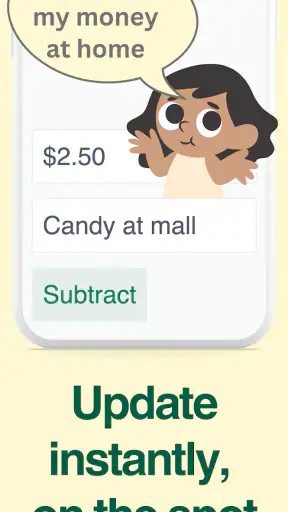
The app’s simplicity can also become a limitation. A virtual balance only stays meaningful when the family updates it consistently. If parents forget to record an allowance or make an offline payment without reflecting it in the app, the child may see numbers that no longer match the household agreement. I would set a regular update time instead of expecting the app to maintain the system automatically.
There is also a risk of over-focusing on the number. A child may begin to see every helpful action as a transaction, especially if chores and allowance are always linked. I would keep some responsibilities outside the reward system and explain that family contributions are not all paid tasks. The app should support values and communication, not replace them.
Another limitation is that the tool may feel too basic for families with complicated arrangements. Shared custody, multiple currencies, irregular income or several adults contributing to one child’s goals can require careful coordination. In those situations, a written agreement or a broader household finance tool may be easier to audit. I would only use this app if everyone involved can follow the same update rules.
The optional purchase model is worth considering as well. Free access lowers the barrier to trying the app, but the listed purchase range means families should decide in advance whether any paid extras are necessary. I would begin with the core routine, evaluate whether the child actually uses it, and avoid buying additions simply because they appear during setup.
Who should try it, and who should choose something else
I think Piggy Bank Allowance is a good match for parents introducing pocket money for the first time, especially when the child needs a visual distinction between immediate spending and longer-term saving. It is also useful for families moving away from cash but not ready to involve a child in formal banking. The free entry point makes experimentation easier, provided the adult manages purchases and privacy choices thoughtfully.
I would be more cautious if your child is very young and cannot yet distinguish virtual money from real money. In that case, combine the app with coins, pictures or a physical container. I would also look elsewhere if you need chore scheduling, detailed family task management, real payment controls or live banking features. Those needs go beyond what this focused allowance tracker is designed to provide.
Families who dislike screens may find that a paper system creates better conversations. That is not a weakness unique to this app; it is a question of fit. If opening a phone every week makes allowance feel bureaucratic, a physical piggy bank may be more engaging. The app earns its place when the digital record solves a real problem, such as forgotten agreements or unclear saving divisions.
My cautious verdict after using it
With an average rating of 4.4 from around 684 ratings and more than 50K installs, Piggy Bank Allowance has clearly found an audience among families looking for a straightforward digital allowance aid. It was released on March 24, 2023, and the current version is 2.0.266. Those details do not decide whether it belongs in your home, but they place it as an established, actively presented option rather than an idea limited to a paper concept.
My recommendation is positive, with boundaries. I would install it for a child who is ready to practise saving and spending decisions, then introduce it alongside a clear family agreement about updates, real payments, privacy and purchases. I would not present the virtual balance as a bank account, and I would not let the app make the financial lesson for me.
The app works best when it makes a parent-child conversation easier, not when it tries to replace that conversation. Used that way, its jars or pots provide a simple visual structure, its free starting point keeps the risk low, and its focused design avoids the distractions of a full banking product. If your family needs more advanced controls or actual transactions, choose a different category of tool. If you need a calm, visible way to practise allowance habits, this is a sensible place to begin.
Pros
- Simple way to track children’s allowances and savings goals.
- Encourages kids to learn budgeting through regular money management.
- Parents can monitor balances without relying on paper records.
- Useful for organizing chores
- payments
- and reward-based allowances.
- Digital records make allowance history easier to review and understand.
Cons
- May require both parents and children to use the app consistently.
- Features may feel limited for families needing advanced budgeting tools.
- Children may lose motivation if rewards and chores are not updated regularly.
- Depending on setup
- some functions may require an account or personal data.
- Digital allowance tracking does not replace conversations about responsible spending.
Frequently Asked Questions
What is Piggy Bank Allowance - Bomad, and who is it designed for?
Piggy Bank Allowance - Bomad is a family-focused allowance and money-management app designed to help parents teach children how to handle pocket money. It can be used to record allowances, organize chores or responsibilities, track savings, and encourage conversations about spending. It is best suited to families looking for a simple digital alternative to paper charts or informal cash tracking.
How can parents use the app to manage allowances and chores?
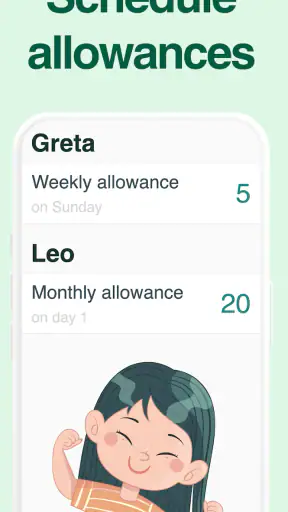
Parents can typically use Piggy Bank Allowance - Bomad to set up children’s profiles, define recurring or one-time allowances, and connect payments with completed chores or agreed responsibilities. The app provides a clearer overview of what has been earned, saved, or spent. Before downloading, parents should review the available settings to confirm that the allowance schedule and chore system match their family’s routine.
Does Piggy Bank Allowance - Bomad handle real money or only track allowances?
The app is primarily intended as a digital tool for recording and organizing allowance information, rather than replacing a bank account or functioning as a full payment service. Whether it supports transfers, linked accounts, or only virtual balances may depend on the current version and region. Parents should check the app’s latest description and permissions before assuming that money can be sent directly through it.
Is Piggy Bank Allowance - Bomad safe for children to use?
Because the app involves children, allowances, and potentially personal family information, parents should set it up and supervise its use. Check what data is collected, whether an account is required, and how information is stored or shared. Children should not be encouraged to enter sensitive details, banking credentials, or private information without parental guidance, even when the app is used only for educational purposes.
Is Piggy Bank Allowance - Bomad free to download, and are there any limitations?
The download price and available features can vary between Android and iOS, and some versions may include optional purchases, subscriptions, advertisements, or limits on profiles and tracking tools. Before installing, review the current store listing, in-app purchase section, privacy information, and device requirements. This will help you understand whether the free version is sufficient for your family or if additional features require payment.