Rain Instant Pay
- Rating
- 4.8
- Downloads
- 500,000+
- Age
- Everyone
Additional Info
- App Name
- Rain Instant Pay
- Category
- Business
- Package Name
- us.rain.app
- Developer
- Rain Technologies Inc
- Rating
- 4.8
- Version
- 1.77.1
 Analysis by Appcrazy
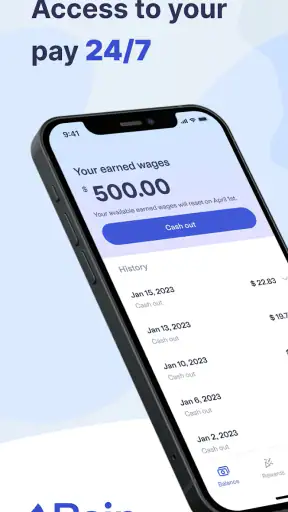
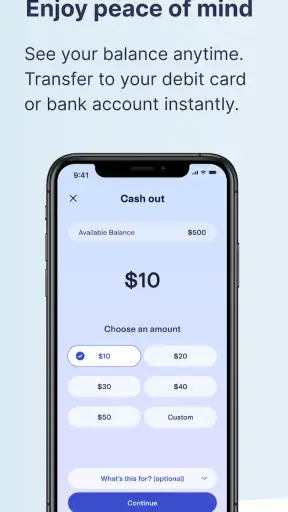
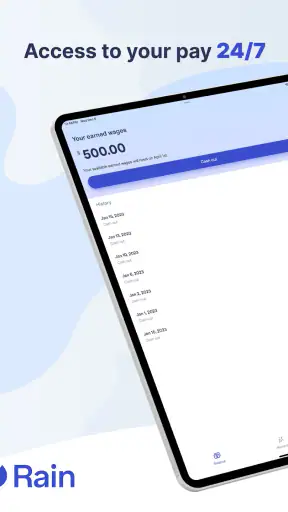
When an unexpected expense lands between paydays, the problem is often not income but timing. Rain Instant Pay is built around that gap, giving eligible employees a way to access employer-linked benefits through a mobile app rather than waiting for the usual payday cycle. I found the idea easy to understand: it is not trying to become a full banking replacement, but to make earned-pay access more practical when cash flow gets tight.
That narrow purpose is also the app’s biggest strength. Instead of presenting a huge collection of financial tools, Rain focuses on the connection between an employee and the benefits made available through their employer. In my experience, that makes the app easier to approach than a general money-management service, especially for someone who mainly wants to know whether they can use an available benefit and what action to take next.
How Rain Instant Pay turns a payday problem into a practical option
The central capability is instant pay access through an employer benefit. The important distinction is that the app is not simply a generic cash-advance tool that anyone can use after downloading it. Its usefulness depends on the relationship between the user, the workplace, and the benefits enabled for that employee. That makes the first step less about exploring menus and more about checking whether the workplace connection is available.
I would approach setup with realistic expectations. Downloading a free app does not automatically mean that every employee can use every part of it. Rain is most relevant when an employer participates and the employee is recognized within that arrangement. For that reason, I would first look for the workplace connection inside the app and make sure the employment details are entered carefully. A small mismatch can create more frustration than the feature itself deserves.
Once access is available, the app’s value is mostly about reducing the distance between an urgent need and an available benefit. That can be more useful than a traditional budgeting app in a specific moment. A budgeting tool may help me plan for next month, while Rain is aimed at the immediate question: can I use part of an employer-linked benefit before the normal pay cycle?
The practical workflow is best treated as a decision rather than a reflex. I would open the app, review what is available, consider the amount needed, and use only enough to solve the immediate problem. That habit matters because faster access can be helpful, but it can also make it easier to spend money intended for a later date. The app can improve timing; it cannot remove the need to manage the rest of the pay period.
One useful way to think about Rain is as a short-term cash-flow tool. It may help with a grocery trip, a transport problem, or a bill that arrives before payday. It is less suitable as a way to permanently stretch an income that is already insufficient. If I needed repeated access every pay cycle just to cover ordinary expenses, I would treat that as a warning sign and look for a broader financial solution instead.
Catch Up on the Latest Stories
Microsoft Teams on Mobile Keeps Work Moving, If You Keep It Tidy
Groupon Turns Local Discounts Into a Marketplace, With a Catch
App of the Week: Yandex Go Makes City Errands Easier
Make Xiaomi Weather Work Harder with Smarter Settings and Daily Routines
Boomplay Turns Music Streaming Into a Daily Discovery Habit
Google Docs on Mobile Keeps the Page in Focus, Until Formatting Gets in the Way
A realistic workday example
Imagine that my car needs an unexpected repair late in the week and I need the vehicle to reach work. Waiting for payday could create a larger problem, such as missed shifts or expensive alternatives. In that situation, I would check Rain before turning to a high-cost borrowing option. If my employer benefit is active and the available amount fits the repair, the app could help me handle the immediate disruption without starting a longer application process elsewhere.
The same logic applies to a household bill that cannot reasonably wait. The advantage is not that Rain makes the bill cheaper; it is that the timing may become more manageable. I would still compare the amount I need with the money left for rent, food, transport, and other fixed commitments. Taking the maximum available amount simply because it appears on screen would be poor use of the feature.
That is one of the less obvious lessons of an instant-pay product: convenience changes behavior. When access is visible on a phone, the psychological barrier to using it is lower than with a formal loan application. I see that as both a benefit and a responsibility. The app is most helpful when it supports a planned exception, not when it becomes an automatic response to every uncomfortable expense.
What the app is like as a business tool
Rain sits in the Business category, but I would not confuse that label with business accounting or company management software. Its business connection comes from the employer-benefit relationship. For workers, the relevant experience is personal and practical. For employers, the concept is tied to how benefits are made available to staff, but the everyday user is mainly concerned with access and timing.
Rain Technologies Inc is the developer behind the app. The product has been available since February 1, 2020, and its current version is 1.77.1. Those details suggest an established service rather than a brand-new experiment, although an established app can still require users to pay attention to updates and changes in the way employer access is handled.
The app is free to install, which removes an obvious barrier for someone who wants to check eligibility. It is also rated for Everyone, and the minimum operating-system requirement is Android 7.1. That broad compatibility is useful for people who do not own a recent phone, although the real deciding factor remains whether the employer-linked benefit works for them.
Its store summary describes the purpose as unlocking employer benefits, and the short description presents it as instant pay. I think that framing is accurate as long as it is read carefully. The app’s promise is about access to an available workplace benefit, not a guarantee of unrestricted money whenever a user asks for it.
Where Rain feels better than the usual alternatives
Compared with asking a bank for a personal loan, Rain can feel more proportionate for a small, urgent cash-flow issue. A bank product may involve a longer review, a larger commitment, or a repayment structure that does not match the problem. Rain’s employer-linked approach is more focused on the pay cycle and the benefit relationship.
Compared with a credit card, the app may be easier to understand for someone who wants to avoid opening another line of credit. A card can be useful for planned purchases and broader flexibility, but it can also encourage a balance to remain outstanding. Rain is more narrowly connected to immediate access, which may be preferable when the goal is to bridge a short gap rather than finance a purchase over time.
Compared with a conventional budgeting app, Rain does something different. Budgeting software helps me see patterns, set limits, and prepare for future expenses. Rain helps address the timing of money already connected to employment benefits. I would not choose one as a replacement for the other. The strongest setup could be using a budget to decide whether access is genuinely necessary, then using Rain only when the numbers still make sense.
Compared with asking friends or family for help, the app can feel more private and less socially uncomfortable. That does not automatically make it the cheapest or best choice, but it changes the experience. A user may prefer handling a short-term need through an employer-linked service rather than explaining the situation to someone they know.
There is also an important trade-off against simply waiting for payday. Waiting costs nothing in terms of a new financial action, but it may create late fees, missed transport, or lost work opportunities. Rain becomes more compelling when the cost of waiting is higher than the cost and consequences of accessing the benefit. If waiting is harmless, I would usually keep the money in the normal pay cycle.
The friction I would want users to anticipate
The first limitation is eligibility. The app’s usefulness is not universal in the way a basic calculator or notes app is. If the employer relationship is not available, the download alone will not solve the problem. This is the most important point for a new user because it prevents an unrealistic expectation before setup begins.
The second limitation is that instant access can make financial planning feel easier than it really is. The next payday does not become larger just because part of an employer benefit was accessed earlier. I would write down the amount used and treat it as money that has already been allocated. Without that simple step, it is easy to forget the effect on the rest of the pay period.
A third issue is that the best choice depends on the size and nature of the expense. For a modest, one-off gap, an employer-linked benefit may be sensible. For a long-term debt problem, recurring medical costs, or a major purchase, it is not the right tool. In those cases, I would rather speak with the relevant provider, review a full budget, or compare formal financial products carefully.
I would also avoid judging the app solely by how quickly it opens or how simple the first screen feels. The important questions are practical: am I eligible, what amount is actually available, how will using it affect my next pay period, and is this expense urgent enough to justify acting now? A polished interface cannot answer those questions for me.
Another trade-off is concentration. Because Rain is tied to an employer benefit, it may be useful while I am connected to that workplace but less relevant if my employment changes. That makes it a situational tool rather than something I would build my entire financial routine around. I would keep independent records of my budget and commitments instead of relying on one app to represent my complete financial position.
Small habits that make the feature safer to use
My first tip is to check the app before an emergency, not during one. If the workplace connection is available, learning the basic flow in a calm moment makes it easier to act carefully later. I would confirm that I can recognize the relevant benefit screen and understand the amount shown before a bill becomes urgent.
My second tip is to decide the exact expense before opening the access flow. “I need some money” is too vague. “I need enough for this repair” or “I need to cover this specific bill” creates a natural limit. That small change reduces the temptation to take more simply because more may be available.
My third tip is to pair every use with a next-payday plan. I would list the amount accessed, the expense it covered, and the bills that remain. This is especially important for users who already manage several automatic payments. Instant pay can solve today’s problem while quietly making the next week tighter.
A fourth useful habit is to compare the cost of alternatives before acting. If waiting means no real consequence, waiting may be better. If another option carries a serious fee or risks losing work, Rain may have more practical value. The right decision is not always “use the app”; it is “use the app when the timing benefit outweighs the downside.”
Finally, I would keep the app’s role clearly defined. It is a bridge for employer-linked access, not a replacement for emergency savings, a full budget, or professional financial advice. That boundary helps preserve its usefulness instead of turning a convenient feature into a recurring dependency.
Who will benefit most from Rain Instant Pay?
I think the strongest audience is an employee whose workplace supports the service and who occasionally faces expenses that arrive before payday. That person may have a steady income but still experience awkward timing around transport, groceries, household bills, or an unexpected repair. For them, the app can provide a more direct option than applying for a larger financial product.
It may also suit workers who value privacy and speed when handling a short-term need. The employer-benefit connection gives the service a different character from asking for a favor or opening a new credit account. Someone who wants a focused tool rather than a large financial dashboard may appreciate that limited scope.
I would be more cautious recommending it to anyone who frequently needs early access for routine living costs. In that situation, the problem is probably structural rather than temporary, and repeated use could make each following pay period harder. A budget review, savings plan, debt counseling, or a different financial product would likely address the underlying issue better.
I would also suggest skipping it if the user expects a universal cash app with no employer connection. Rain is not the right choice for someone who wants broad spending, investing, banking, or business-accounting features in one place. Its value comes from one specific capability, and that capability matters only when the employment benefit is available and the timing problem is real.
My final view after focusing on the one feature that matters
Rain Instant Pay succeeds because it concentrates on a problem many workers recognize: having income connected to work but not available at the exact moment an expense appears. In my view, the employer-linked instant-pay feature is genuinely useful when it prevents a small timing issue from becoming a missed shift, a late bill, or an unnecessarily expensive borrowing decision.
The app’s high average rating of 4.8 from around 30 thousand ratings, together with over 500 thousand installs, shows that it has attracted substantial user interest. I would treat those figures as signs of reach and satisfaction, not as proof that it will fit every employer or every financial situation. Eligibility and personal cash-flow discipline still matter more than popularity.
My recommendation is straightforward: install it if your employer offers the relevant benefit and you want a focused way to handle occasional gaps before payday. Use it with a written limit and a clear plan for the next pay period. If you need a complete financial system or depend on early access repeatedly, choose a broader solution instead. Rain is most valuable as a controlled bridge, not as a permanent substitute for financial planning.
Pros
- Fast access to earned wages.
- No credit check required.
- Easy-to-use interface.
- Secure transactions.
- Available on Android and iOS.
Cons
- Fees for instant transfers.
- Limited withdrawal partners.
- Requires employer participation.
- May encourage overspending.
- Not available in all regions.
Frequently Asked Questions
What is Rain Instant Pay and how does it work?
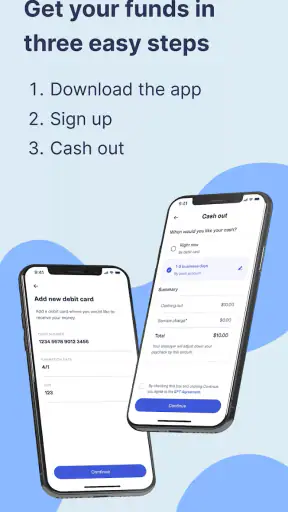
Rain Instant Pay is a financial wellness app designed to help employees access their earned wages before payday. By integrating with employers' payroll systems, it allows users to withdraw a portion of their earned pay on-demand, providing financial flexibility and preventing the need for high-interest loans or overdrafts.
Is Rain Instant Pay secure to use?
Yes, Rain Instant Pay prioritizes user security by employing advanced encryption technologies and adhering to strict data protection regulations. The app ensures that all transactions and personal information are safeguarded, providing users with a secure platform to manage their finances without worrying about data breaches or unauthorized access.
Are there any fees associated with using Rain Instant Pay?
While Rain Instant Pay aims to provide a cost-effective solution, users may encounter minimal fees for each transaction made through the app. These fees are typically lower than those associated with payday loans or overdraft charges, making it a more affordable option for accessing earned wages early.
Can anyone use Rain Instant Pay, or is it limited to certain employers?
Rain Instant Pay is available to employees of participating companies that have partnered with the app. If your employer is part of the program, you can easily sign up and start accessing your earned wages. If not, you can encourage your employer to join the Rain Instant Pay network for wider access.
How quickly can I access my earned wages through Rain Instant Pay?
Once your employer is set up with Rain Instant Pay, accessing your earned wages is typically a quick process. Users can often receive funds within minutes, depending on their bank's processing times. This instant access helps users manage unexpected expenses and improves overall financial stability.