Sezzle - Buy Now, Pay Later
- Rating
- 4.6
- Downloads
- 1,000,000+
- Age
- Everyone
Additional Info
- App Name
- Sezzle - Buy Now, Pay Later
- Category
- Shopping
- Package Name
- com.sezzle.sezzlemobile
- Developer
- Sezzle Mobile
- Rating
- 4.6
- Version
- 4.0.24
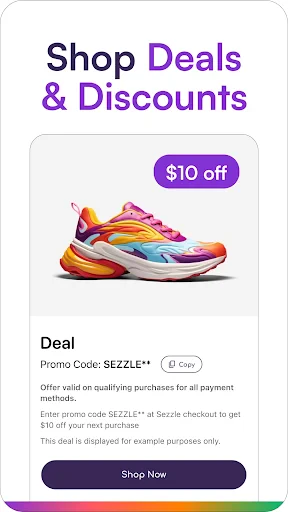
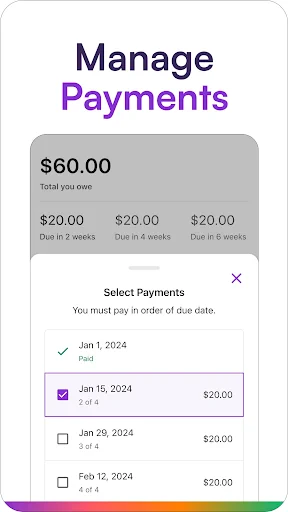
 Analysis by Appcrazy
When I look at a buy-now-pay-later app, I do not start with the promise of paying later. I start with a more practical question: will it make a planned purchase easier to manage, or will it make an impulse purchase feel harmless? After spending time with Sezzle, I see it as a useful shopping companion for people who already know what they want and need a clearer way to spread the payment. I do not see it as a replacement for a normal budget.
This is a free shopping app from Sezzle Mobile, aimed at people who want to pay over time without interest under the applicable terms. It has a 4.6 average from around 99 thousand ratings, with more than a million installs, so it is clearly being used at meaningful scale. The Everyone age rating also makes its presentation approachable, although the financial responsibility involved still matters more than the age label.
My overall view is positive but conditional. The app can be convenient when a necessary or carefully planned purchase arrives at an awkward time. It is less convincing when the payment plan is being used to justify buying something that was not in the budget. That distinction is the key to deciding whether it belongs on your phone.
How I decide whether a pay-later app is a good fit
I judge a pay-later app by what it asks me to keep doing after checkout: remember dates, protect money for future payments, and resist treating a smaller installment as a lower price. That makes the first purchase only a starting point; the real test is whether the routine stays clear when other bills and plans compete for attention.
Start with the purchase, not the payment screen
The first test is simple: would I still buy the item if the full amount had to leave my account today? If the answer is no, I treat the offer as a warning rather than a benefit. Splitting a purchase can improve timing, but it does not reduce the real cost of the item or remove the need to keep enough money available for later installments.
I also look at how often I would use the service. A single planned purchase is easier to track than several overlapping orders. The danger is not necessarily one individual installment; it is forgetting that several small commitments can become one large monthly obligation. I recommend writing down the total future payments before confirming an order, especially if other bills are due around the same time.
Check the practical details before confirming
In my experience, the most important part of using Sezzle is slowing down at checkout. I read the payment schedule, check the total amount, and make sure the payment method is still valid. I do not rely on memory for dates. A calendar reminder or a note in my budgeting app makes the arrangement much easier to manage.
Catch Up on the Latest Stories
Microsoft Teams on Mobile Keeps Work Moving, If You Keep It Tidy
Groupon Turns Local Discounts Into a Marketplace, With a Catch
App of the Week: Yandex Go Makes City Errands Easier
Make Xiaomi Weather Work Harder with Smarter Settings and Daily Routines
Boomplay Turns Music Streaming Into a Daily Discovery Habit
Google Docs on Mobile Keeps the Page in Focus, Until Formatting Gets in the Way
The phrase “no interest” should also be read carefully rather than treated as a universal promise that every situation is free of every possible cost. The exact terms shown for a transaction are what matter. I would review any displayed fees, timing conditions, and consequences of a failed payment before committing. That habit is more valuable than simply choosing the app with the friendliest headline.
Consider whether you need a shopping app at all
Sezzle makes the most sense when a participating retailer and a pay-over-time option solve a real problem together. If I can comfortably pay in full, a regular debit or credit card may be simpler. If I need longer-term borrowing, a conventional financial product may be more suitable, depending on my circumstances and its terms. If I am trying to stop overspending, avoiding installment services altogether is often the better decision.
That is why I would not judge this app only by how quickly it helps me place an order. I judge it by what happens afterward: can I remember the schedule, keep enough money available, and continue paying for essentials without stress? If not, convenience has become friction in disguise.
What the app is like in everyday use
The useful part of the experience is that the payment option sits close to the shopping process instead of requiring me to arrange a separate personal loan. That can be helpful when I am comparing an item, reviewing the order, and deciding how to handle the payment in one session. The app’s purpose is easy to understand, which reduces the learning curve for a first-time user.
At the same time, simple presentation can make a commitment feel lighter than it really is. I try to pause after seeing the installment amount and mentally reconstruct the complete purchase. A small recurring payment can sound comfortable while the total price remains significant. This is one of the less obvious skills needed to use Sezzle well: translate the small number back into the full obligation before proceeding.
Where Sezzle wins, and where another option may fit better
For me, the best alternative depends on the job: a debit payment is simpler when the money is ready, while a carefully managed credit card or a longer-term option may suit a different repayment need. I’ll weigh Sezzle’s focused convenience against the habit it requires, so you can decide whether its role in your shopping routine remains useful after the initial appeal fades.
Its strongest advantage is focused convenience
Sezzle wins for shoppers who want a dedicated way to divide an eligible purchase without turning the process into a lengthy borrowing exercise. The free download removes an upfront app cost, and the shopping-focused design keeps the purpose clear. I can see the appeal for replacing a worn-out household item, buying seasonal clothing, or handling a planned expense that arrives just before payday.
Another strength is the mental separation between shopping and ordinary banking. Some people prefer not to use a credit card for every purchase, while others do not have or do not want a traditional revolving credit account. For those users, a pay-later app can feel more controlled when the schedule is short, visible, and tied to one specific order.
The app is also useful as a decision checkpoint. Rather than immediately paying with a card and forgetting about the purchase, I am encouraged to look at how the cost will be divided. Used properly, that can make me more deliberate. I can ask whether the future payments fit my actual cash flow before the order is complete.
A realistic example of when it helps
Imagine I need a replacement pair of shoes for work after my current pair becomes unusable. I have already compared options, know the amount I can afford overall, and expect my next income payment soon, but paying the entire amount today would leave less room for groceries and transport. In that situation, I could use Sezzle to spread the purchase while keeping the total commitment visible.
The important detail is that I would reserve the money mentally from the beginning. I would not treat the remaining balance as spare cash. I would also avoid adding another installment purchase until the first one is finished. In this scenario, the app supports timing; it does not create affordability.
The trade-off behind “pay later”
The main weakness is behavioral. Because the first payment can appear smaller than the full price, the app may lower the emotional barrier to buying. That is not a technical failure, but it is a real usability concern. A tool that makes payment easier can also make overcommitment easier.
There is another practical trade-off: every payment plan creates something else to monitor. If I shop frequently, I need a system for tracking order totals and due dates. The app can organize the payment arrangement, but it cannot decide whether three simultaneous plans are sensible for my budget. That responsibility remains with me.
I also would not assume that every retailer, product, or transaction will offer the same experience. Eligibility and displayed terms are part of the checkout decision. I would open the relevant details for the specific order instead of planning a purchase around an assumption that may not apply at the moment I need it.
When a normal card or bank payment is better
A standard debit card is usually better when I already have the money and want the least complicated transaction. There is no future installment schedule to remember, and the purchase is finished immediately. For routine groceries, subscriptions, or small everyday items, adding a pay-later arrangement can create needless administration.
A credit card may be a better fit for someone who understands its terms, pays the balance reliably, and values the account features available to them. I would not switch from a well-managed card solely because an installment amount looks smaller. The right comparison is the total cost, the repayment discipline required, and the consequences if cash flow changes.
For a large expense that needs a longer repayment period, a different borrowing category may offer a more appropriate structure. I would compare the complete terms rather than forcing a short pay-later plan to carry a purchase that is too large for it. Sezzle is most persuasive for controlled, limited purchases, not as a general solution for ongoing financial pressure.
Who should probably skip it
I would tell someone to skip Sezzle if they are already missing bills, using one payment plan to cover another, or unsure how much money will be available after payday. I would also be cautious if the app encourages frequent browsing and unplanned purchases. In those situations, the best alternative may be a spending pause, a written budget, or saving before buying.
It is also not ideal for a person who dislikes tracking multiple due dates. A conventional full payment may feel less exciting, but it is often easier to understand. Likewise, anyone who wants a single place for broader banking, savings, and long-term financial planning may find a shopping-specific app too narrow.
What switching to Sezzle really involves
Moving from ordinary checkout to Sezzle is not just a matter of installing an app. I have to change my shopping routine. I need to check whether the option applies, review the specific payment arrangement, keep the selected payment method current, and remember that the order continues after the excitement of delivery has passed.
That ongoing attention is the real cost of switching. The app itself may be easy to understand, but the habit around it determines whether it helps. I would start with one modest, planned purchase rather than immediately using it for several orders. After that, I would review whether the schedule felt effortless or whether I had to keep searching for reminders and available funds.
There is also a return-related habit worth adopting: I would keep the payment plan in mind until the transaction is fully settled. If an item is returned, delayed, exchanged, or partially refunded, I would check how the payment arrangement reflects that change rather than assuming the schedule automatically matches my expectations. That small step can prevent confusion when the physical order and the financial record no longer look identical.
Version, compatibility, and basic access
The current version is 4.0.24, and the app supports Android 7.0 or later. That makes it accessible to people using older Android devices, although I would still keep the operating system and app updated when possible for general security and reliability. Since this is a financial shopping tool, I would use a device with a screen lock and avoid signing in on a shared phone.
Sezzle Mobile is the developer behind the app. The product has been available since March 21, 2019, which gives it a longer presence than a newly launched shopping tool. Its free price is convenient for trying the service, but the absence of a download charge should not distract from reviewing the terms attached to each purchase.
Three habits that make the experience safer and clearer
- Track the full order total: I record the original price, not just the first installment, so the purchase remains visible in my budget.
- Separate planned needs from browsing: I open the app with a specific item or spending limit in mind, rather than treating available payment options as a reason to shop.
- Review future commitments before adding another: I check upcoming installments alongside rent, utilities, food, and transport before accepting a second arrangement.
These habits sound basic, but they address the central weakness of pay-later shopping: the payment schedule can be easy to start and surprisingly easy to forget. I find the app most useful when I treat it as a budgeting event, not as a discount.
My recommendation after weighing the alternatives
I recommend Sezzle to a disciplined shopper who wants flexibility for a specific purchase and is comfortable checking the exact terms before confirming. It is especially reasonable when the total cost is already affordable, the timing is the only problem, and the user has a reliable way to monitor future payments.
I do not recommend it as a way to stretch an already tight budget, make frequent impulse purchases, or replace a proper emergency fund. In those cases, a normal payment, a savings plan, or simply waiting is likely to be healthier. The app cannot turn an unaffordable item into an affordable one; it only changes when the money leaves your account.
After using it, I would describe Sezzle as a convenience tool with a responsibility attached. Its focused shopping experience, free access, and strong user response make it worth considering, but the best results come from restraint. Start with one planned purchase, read the schedule carefully, and keep the full amount in your budget from day one.
If that approach sounds natural to you, Sezzle can be a practical addition to your shopping routine. If you prefer to finish every purchase immediately or do not want another payment schedule to manage, the usual alternatives may serve you better. My final choice is therefore clear: use it for controlled timing, never as permission to spend beyond what you can genuinely repay.
Pros
- Flexible payment options
- No interest if paid on time
- Easy account setup
- User-friendly interface
- Widely accepted at stores
Cons
- Late fees if payment missed
- Requires linking to bank account
- Limited support for some stores
- Potential impact on credit score
- App could use more features
Frequently Asked Questions
What is Sezzle and how does it work?
Sezzle is a buy now, pay later app that allows you to split your purchases into four interest-free payments over six weeks. When you check out with Sezzle, the first payment is made at the time of purchase, and the remaining three payments are automatically scheduled. This makes it easier to manage your budget without incurring additional costs.
Does Sezzle charge any fees or interest?
Sezzle does not charge interest on your purchases, making it a cost-effective alternative to credit cards. However, if you miss a payment, a late fee may be applied. To avoid any fees, ensure that you have sufficient funds in your linked payment method and make payments on time.
What are the eligibility requirements to use Sezzle?
To use Sezzle, you must be at least 18 years old and have a valid email address, a U.S. or Canadian phone number, and a non-prepaid payment method. Additionally, Sezzle performs a soft credit check to assess your eligibility, but this does not affect your credit score.
Where can I use Sezzle for payment?
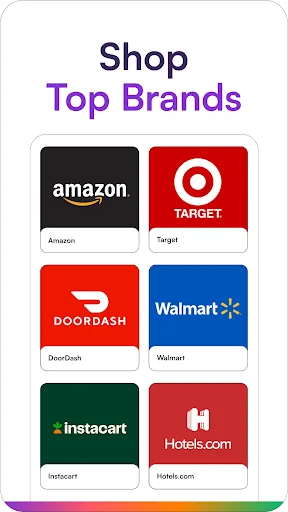
Sezzle can be used at thousands of online stores that partner with the platform. When shopping, look for the Sezzle logo at checkout to confirm that the store accepts Sezzle payments. Additionally, Sezzle is expanding its presence in physical retail locations, allowing for more opportunities to use the service.
How does Sezzle impact my credit score?
Using Sezzle does not affect your credit score since it performs only a soft credit check. However, if your account is sent to collections due to non-payment, it could negatively impact your credit. It's essential to make timely payments to maintain good financial health.