telebirr
- Rating
- 4.4
- Downloads
- 5,000,000+
- Age
- Everyone
Additional Info
- App Name
- telebirr
- Category
- Business
- Package Name
- cn.tydic.ethiopay
- Developer
- Ethio telecom SC
- Rating
- 4.4
- Version
- 1.2.5.035
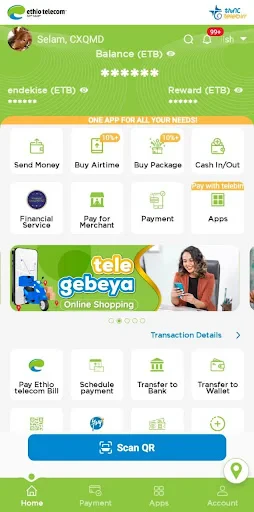
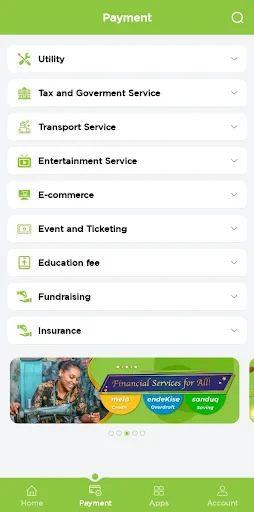
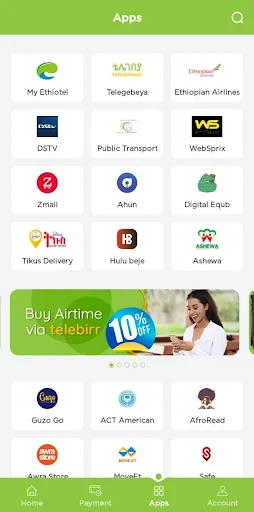
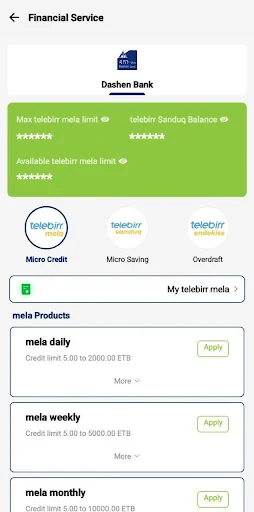
 Analysis by Appcrazy
When I first look at a financial app, I do not ask only whether it can move money. I ask whether it will still feel useful after the first week, when the novelty has gone and everyday payments become routine. telebirr makes a strong first impression as a free business app from Ethio telecom SC, built around the idea of bringing common money tasks into one place. Its store summary presents it as the telebirr SuperApp service, but the more important question for me is whether that promise translates into a habit that saves time rather than creating another app to maintain.
My overall view is positive, with an important qualification: this is most convincing for people already comfortable using mobile financial services and for users whose daily transactions fit the telebirr environment. It is less compelling for someone who wants a completely universal replacement for every banking, payment, and business tool. The app has a practical role, but its lasting value depends on how often it matches your real routine.
What the first week feels like
The first-week appeal comes from centralization. Instead of treating every money-related task as a separate errand, telebirr is designed as a single service from Ethio telecom SC. That makes the app easier to understand than a collection of unrelated tools: you install one application, open one account area, and begin learning one familiar workflow. For a new user, that simplicity matters more than a long list of functions.
I also appreciate that it is free to download and has an Everyone content rating. Those details remove two common barriers before you even start. You do not need to decide whether a paid download is worth the risk, and the age classification makes the app feel suitable for a broad household audience. The minimum operating-system requirement is Android 5.0, which gives it a wider reach than many newer apps that require recent hardware.
During the first few days, the main benefit is not excitement but reduced switching. If I am checking a balance, arranging a payment, or handling a small personal transaction, I would rather begin in one recognizable place than search through several unrelated apps. That is the kind of convenience that can make an app feel essential quickly, especially for people who use their phone as their main access point for financial services.
Still, a SuperApp label can create high expectations. I would not install telebirr assuming that one application automatically replaces a full bank account, a business accounting system, or every payment method used by the people around me. Its usefulness depends on the network of people and services with which I transact. A payment tool is only convenient when the recipient, merchant, or organization involved can work with it too.
A realistic everyday routine
Imagine a user who starts the morning by checking available funds, uses the phone to settle a routine payment during the day, and later sends money to a family member without visiting a physical location. In that scenario, the value is cumulative. Each individual action may save only a little effort, but avoiding repeated queues, searches, and separate sign-ins can make the app worth keeping.
Catch Up on the Latest Stories
Microsoft Teams on Mobile Keeps Work Moving, If You Keep It Tidy
Groupon Turns Local Discounts Into a Marketplace, With a Catch
App of the Week: Yandex Go Makes City Errands Easier
Make Xiaomi Weather Work Harder with Smarter Settings and Daily Routines
Boomplay Turns Music Streaming Into a Daily Discovery Habit
Google Docs on Mobile Keeps the Page in Focus, Until Formatting Gets in the Way
The important habit is to open telebirr before choosing a slower alternative. I find that this works best when I keep the app associated with a specific routine, such as checking the account before making a payment or using it as the first option for transfers that fit the service. If I only open it once every few months, I am more likely to forget the layout and question whether it deserves space on my phone.
One practical tip is to learn the confirmation steps carefully during the first week rather than rushing through them. Financial apps reward deliberate habits. I would verify the recipient or payment details before approving anything, keep transaction information available until the action is clearly complete, and avoid treating a familiar interface as permission to tap automatically. Convenience should shorten the process, not remove the checking step.
Where it compares well with usual alternatives
Compared with relying only on cash, telebirr offers a more phone-centered way to manage transactions. That can be especially useful when carrying cash is inconvenient or when a user wants a record of activity rather than depending on memory. Compared with using several specialized apps, its strongest advantage is consolidation: fewer places to remember and fewer separate routines to maintain.
On the other hand, a traditional bank app may remain the better choice for someone whose finances are organized around banking products, formal account management, or services outside the telebirr ecosystem. A dedicated business platform can also be preferable for detailed bookkeeping, staff controls, reporting, or other professional workflows. I see telebirr as a practical transaction companion, not automatically as a replacement for every financial tool.
The app’s public reception suggests that this approach has broad appeal: it holds an average rating of 4.4 from around 67 thousand ratings and has passed five million installs. Those figures do not guarantee that every user will have the same experience, but they do indicate that the service has moved beyond being a niche experiment. I would interpret that reach as evidence of relevance, not as a reason to ignore personal fit.
Why it can remain useful month after month
Long-term value comes from repetition. A financial app earns its place when it handles the same small tasks reliably enough that using it becomes automatic. telebirr has a reasonable foundation for that kind of habit because its purpose is tied to recurring money movement rather than occasional entertainment. If it matches the transactions I make regularly, I do not need a new reason to open it every month.
The best recurring use case is a predictable personal routine. Someone may use it to manage regular transfers, handle everyday payments, or keep mobile financial activity close at hand while away from a computer. The benefit is not that the app makes money management exciting; it makes ordinary actions more accessible. That quiet usefulness is exactly what helps a service survive after the first-week appeal fades.
For small business owners, the app may be useful as a convenient payment-side tool, particularly when work happens away from a desk. I would not use it as the sole record-keeping system for a growing business, but I can see value in having a mobile service available for immediate transactions. The trade-off is clear: speed and accessibility may improve, while deeper financial oversight still belongs in a more specialized system.
A second useful habit is to separate transaction convenience from financial organization. I would use telebirr for the action itself, then periodically review my broader records elsewhere if I needed a complete view of income, spending, or business performance. This prevents the app from being blamed for a job it was not designed to replace and helps keep financial decisions grounded in more than a stream of individual payments.
The maintenance burden is small, but not zero
Every financial app creates maintenance work, even when the interface is simple. I need to keep access details secure, pay attention to confirmations, and make sure my phone remains usable. I also need to remember which transactions I completed through telebirr so I do not duplicate them in another service. These are not dramatic burdens, but they become noticeable when an app is used frequently.
The current version is 1.2.5.035, and I would keep the application reasonably up to date through the normal app-store process. Updates are part of the practical cost of using any financial service: they may improve compatibility and stability, but they can also mean that a familiar screen changes. My advice is to avoid learning only the position of buttons. Learn the purpose of each step so small interface changes do not disrupt the whole routine.
Security discipline is another form of maintenance. I would never approve a transaction simply because the screen looks familiar, and I would check the destination and amount before final confirmation. I would also avoid sharing access information and would be cautious when using a phone that other people can unlock. The app can make a transaction faster, but it cannot replace careful behavior by the account holder.
There is also a social maintenance burden. Before depending on telebirr for an important payment, I would make sure the other party is prepared to receive or process it through the same service. This is one of the less obvious trade-offs of any digital wallet: the app may be excellent for my side of the transaction, yet inconvenient if the recipient expects cash or uses another platform. A quick check beforehand prevents a supposedly instant payment from becoming a negotiation.
What may cause fatigue over time
The first source of fatigue is repetition without enough payoff. If my usual contacts, merchants, or business partners rarely use the service, I may keep the app installed but return to cash or another financial app. In that situation, telebirr becomes a backup rather than a daily tool. No amount of interface familiarity can overcome a mismatch between the service and the transactions I actually make.
The second source is the expectation that a SuperApp should do everything. A broad label can make users compare it with a bank, a bookkeeping package, a bill-management system, and a wallet at the same time. That comparison is unfair if the user needs detailed financial controls or a complete business record. I would be more satisfied by treating telebirr as a focused mobile finance layer and pairing it with another tool when my needs become more complex.
Frequent confirmations can also feel tiring, although they are important in financial software. I prefer a process that asks me to pause before sending money rather than one that makes speed the only goal. The right balance is a workflow I can complete confidently without feeling rushed. If I regularly find myself second-guessing whether an action went through, the convenience advantage starts to disappear.
Another possible frustration is dependence on the phone itself. A mobile-first service is excellent when the device is charged, available, and working normally. It is less comfortable when the phone is shared, damaged, offline, or temporarily inaccessible. For that reason, I would not discard every alternative immediately. Keeping a sensible backup plan is part of responsible financial use, especially for time-sensitive payments.
Who should use it, and who should look elsewhere
I would recommend telebirr to users who want a free mobile financial service from Ethio telecom SC, prefer managing routine transactions from a phone, and regularly interact with people or services that fit its ecosystem. It is also a sensible option for someone who values consolidation and wants to reduce dependence on cash for ordinary payments.
I would be more cautious about recommending it as the only financial application for a business with complicated accounting needs. If you need detailed reports, multiple levels of approval, extensive expense categorization, or a full banking relationship in one place, a dedicated business or banking solution may suit you better. telebirr can still complement that setup, but it should not be forced to carry every responsibility.
I would also suggest skipping it if you rarely make mobile transactions or if the people you pay almost always require another method. An unused finance app adds clutter and another set of access details without delivering recurring value. The right question is not whether the service is popular; it is whether it fits the payments I make repeatedly.
My long-term verdict
After the novelty fades, telebirr has a credible reason to stay installed: it can turn recurring mobile money tasks into one familiar routine. Its free availability, broad age rating, low Android entry point, and established user base make it approachable. More importantly, its lasting value comes from reducing friction in the transactions I genuinely make, not from the SuperApp name alone.
My recommendation is to give it a fair trial built around real habits rather than random exploration. Use it for the payments and transfers that naturally fit your life, note whether the people you deal with can receive money through it, and judge how much checking and switching it saves. That test is more useful than simply opening every section once.
There are limits. It is not a universal substitute for a bank, a cash reserve, or professional accounting software. It also depends on careful user behavior and on compatibility with the wider payment habits of your contacts. Those constraints do not make it a poor app; they define where it works best.
For me, the final judgment is that telebirr earns lasting space when it becomes part of a repeatable payment routine. It is strongest as an accessible mobile finance companion for everyday use, especially for people who benefit from keeping transactions together. If your needs are more specialized, use it alongside a better-matched tool rather than expecting it to replace everything. That balanced role is where I think it offers the most dependable value.
Pros
- Offers low transaction fees
- Supports multiple payment methods
- User-friendly interface
- Secure and reliable service
- Quick transaction processing
Cons
- Limited international reach
- Requires internet for transactions
- Occasional app performance issues
- Customer support can be slow
- Limited features compared to competitors
Frequently Asked Questions
What is telebirr and how does it work?
Telebirr is a mobile money service that allows users to conduct financial transactions using their smartphones. It enables users to send and receive money, pay bills, and purchase airtime. The app is designed to provide a secure and convenient way to manage money digitally, eliminating the need for cash transactions. To use telebirr, users must download the app, register, and link their bank accounts or mobile numbers to start making transactions.
Is telebirr safe and secure to use?
Yes, telebirr is designed with security in mind, employing advanced encryption technologies to protect users’ financial information. The app requires users to set up a secure PIN for authentication, ensuring that only the account holder can authorize transactions. Additionally, telebirr regularly updates its security protocols to safeguard against potential threats. Users are advised to regularly update the app and avoid sharing their PIN with others to maintain account security.
What services can I access using telebirr?
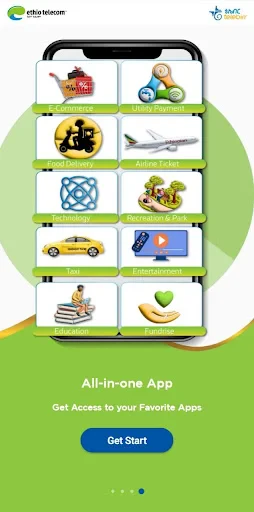
Telebirr provides a wide range of financial services, including sending and receiving money, paying utility bills, purchasing airtime for mobile phones, and making online purchases. Users can also make donations to charities or other organizations directly through the app. Telebirr is continually expanding its service offerings, so users can expect more functionalities to be added over time to enhance their digital financial experience.
How can I register for telebirr, and are there any requirements?
To register for telebirr, users need to download the app from either the Google Play Store or Apple App Store. Upon installation, users must provide personal information such as their name, phone number, and national identification details. In some cases, a verification process may be required to ensure the authenticity of the user. There are no specific requirements apart from having a valid smartphone and an active mobile number to complete the registration process.
Are there any fees associated with using telebirr?
Telebirr charges minimal fees for certain transactions, such as sending money or paying bills, which are usually lower than traditional banking fees. Most basic services, like checking your balance or receiving money, are free of charge. Users can find a detailed breakdown of applicable fees within the app’s settings or on the telebirr website. It is advisable to review these fees to understand any costs that may be incurred during transactions.