The General® Auto Insurance
- Rating
- 4.7
- Downloads
- 1,000,000+
- Age
- Everyone
Additional Info
- App Name
- The General® Auto Insurance
- Category
- Business
- Package Name
- com.pgac.general.droid
- Developer
- The General Automobile Insurance Services, Inc
- Rating
- 4.7
- Version
- 5.1.2
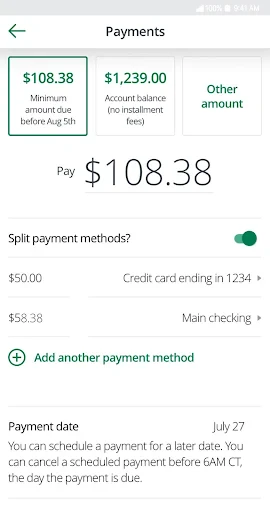
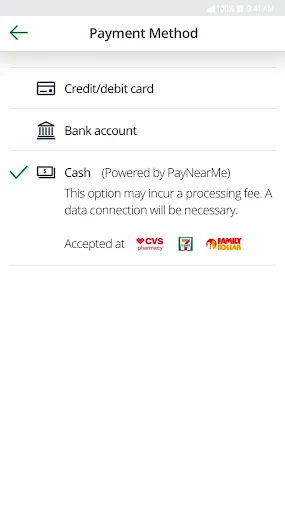
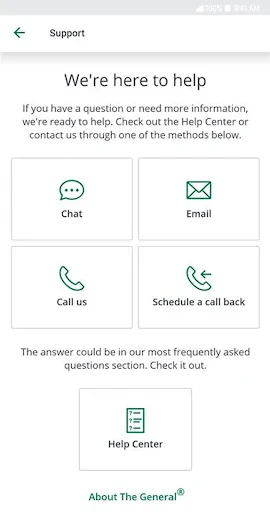
 Analysis by Appcrazy
Choosing car insurance is rarely exciting, but managing it from a phone can make an ordinary driving problem much easier to handle. I spent time looking at how The General® Auto Insurance works as a mobile business app, paying particular attention to whether its screens and workflows feel usable in different everyday situations. The app comes from The General Automobile Insurance Services, Inc, is free to install, and is aimed at customers who want to handle insurance tasks without relying on a desktop browser or a phone call for every small request.
My overall impression is that this is most useful as a practical companion to an existing policy. It is not trying to replace every conversation with an insurance professional, and I would not treat it as a complete solution for every complicated claim or coverage question. Where it does make sense is in giving customers a more direct way to review their insurance relationship, especially when they are away from home, preparing for a trip, or trying to deal with paperwork after an exhausting day.
How clearly the app supports different users and situations
I look at this section through a practical question: can different customers reach the right kind of help without treating every insurance task the same way? I’ll consider how the app fits people with different devices, comfort levels, and day-to-day circumstances, while keeping in view that convenience is most valuable when it supports careful decisions rather than rushing them.
Readability and navigation matter more than decoration
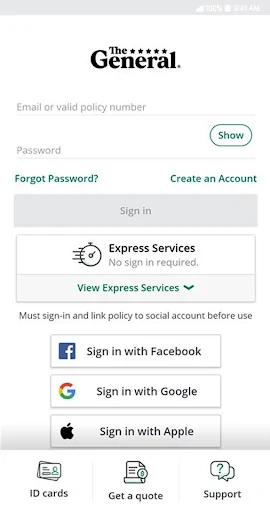
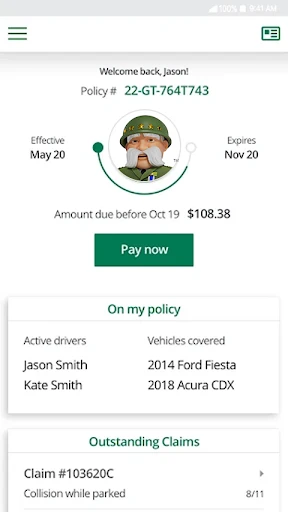
The strongest part of a mobile insurance app is not visual novelty. It is whether I can find the information I need when my attention is divided. Insurance language can already be difficult, so a useful app should make the path to common account tasks feel predictable rather than forcing me to interpret a dense website on a small screen. In that respect, the value of The General’s app is tied to reducing steps and keeping the purpose of each screen understandable.
I would approach it with the expectation that the main experience revolves around account and policy management rather than entertainment or exploration. That distinction is important. A banking app may put balances and transfers at the center, while an insurance app needs to help me understand coverage, account status, and documents at the right moment. The General’s mobile format is most convincing when I am checking something specific, not when I am casually browsing.
For people who read comfortably on a phone, the app should feel more manageable than searching through email attachments or opening a full insurance website in a mobile browser. The smaller screen is still a limitation, particularly when policy details contain several conditions or unfamiliar terms. I would slow down before accepting a change or assuming that a short label tells the whole story. A compact interface can improve focus, but it can also hide context that would be more obvious on a larger display.
My practical advice is to use the app in a quiet place when reviewing coverage, not while standing beside a busy road or trying to solve a problem in a hurry. Save the quick checks for moments when you only need confirmation. For anything involving a change in protection, a claim decision, or a question about what a policy actually covers, I would read the full wording and use the appropriate support channel rather than relying on a summary screen.
Catch Up on the Latest Stories
Microsoft Teams on Mobile Keeps Work Moving, If You Keep It Tidy
Groupon Turns Local Discounts Into a Marketplace, With a Catch
App of the Week: Yandex Go Makes City Errands Easier
Make Xiaomi Weather Work Harder with Smarter Settings and Daily Routines
Boomplay Turns Music Streaming Into a Daily Discovery Habit
Google Docs on Mobile Keeps the Page in Focus, Until Formatting Gets in the Way
The app has attracted a 4.7 average from roughly 38 thousand ratings, with more than 10 thousand written reviews. That level of public use suggests it is not an obscure experiment, and the experience has been shaped by a substantial customer base. It is also listed at over a million installs, which makes the app a familiar option for many people already insured through The General. Those figures tell me that the basic mobile approach has broad appeal, although they do not remove the need to judge whether its workflow suits my own needs.
Motor and sensory considerations during real use
Insurance tasks often happen when a user is tired, stressed, or physically uncomfortable. Someone may be dealing with a damaged vehicle, sitting in a repair shop, or trying to confirm documents while travelling. That makes clear text, sensible grouping, and uncomplicated navigation more important than flashy presentation. I found the accessibility question here less about special tools and more about whether the app lets me complete a necessary task without unnecessary visual or mental effort.
Users with reduced vision may prefer increasing the phone’s system text size, using display zoom, or turning on a screen reader before opening account details. The important caveat is that system adjustments only help when an app’s layout responds well to them. If text becomes crowded or controls lose their context, a larger display or browser session may be more comfortable. I would test the screens that matter most to me, such as policy information and documents, rather than assuming that the whole app behaves identically.
For users with hearing loss, a text-based mobile workflow can be more convenient than depending on a phone conversation for every routine question. That does not mean every insurance situation can be handled silently inside the app. A serious incident may still require communication through another channel, and a user should not wait for an app screen if immediate assistance is needed. The app is best viewed as one part of the service experience, not as a promise that every interaction is self-service.
People with limited dexterity may appreciate avoiding repeated typing, especially when they are entering information with one hand. At the same time, insurance forms can involve precise details, and small controls or time-sensitive screens can become frustrating. I would complete important changes while seated, with the phone supported, and check every entry before submitting it. Voice input may help with longer text, but I would review automatically entered names, addresses, registration details, and incident descriptions carefully because accuracy matters more than speed.
For users with cognitive or learning differences, the best approach is to break the task into one goal at a time. Instead of opening the app with a vague plan to “sort out insurance,” I would decide whether I am checking a document, reviewing an account item, or looking for help. Keeping a note of questions before starting can prevent repeated navigation and reduce the temptation to make a quick decision simply because the wording feels complicated.
Situational access: where the app earns its place
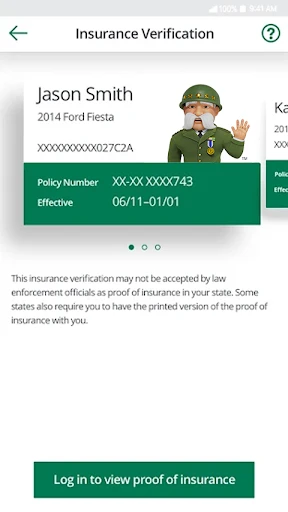
The most realistic use case is a minor incident in a car park. I might return to the vehicle and notice damage, feel unsure about the next step, and want to confirm my insurance details before speaking with anyone. A phone-based account gives me a way to begin from where I am. I can focus on identifying the relevant information rather than searching through a drawer for paper documents. I would still avoid using the phone while driving and would move to a safe location before opening anything.
Another useful situation is preparing for a long trip. Before leaving, I could review the information associated with my policy and make sure I know where to find the relevant documents. This is a better workflow than discovering during a roadside problem that I cannot remember my login or do not know which document contains the detail I need. My tip is to check access while calm and connected, not for the first time after a breakdown.
The app can also be helpful for people who do not have regular access to a computer. A smartphone may be the device they use for nearly every administrative task, so a dedicated insurance app can remove the need to find a larger screen. That is particularly relevant for customers who manage work, family, and transport from one device. However, a phone-only user should keep their account recovery information current and avoid assuming that a mobile app eliminates the need for secure login habits.
For someone with limited data, an unreliable connection, or an older phone, situational access becomes less certain. The app is convenient when the device, connection, and account are all cooperating. It is not a substitute for carrying essential information in a safe offline form when travelling through areas with weak service. I would keep necessary policy references available in a secure way and would not depend on one app as the sole source of help during an emergency.
Families and shared-car households may also need to think carefully about who is using the device. If several people drive the same vehicle, the person holding the phone may not be the person named on the account or the person handling the incident. That can create confusion if the app is opened without the right credentials or if the user assumes that one account view answers every driver’s question. I would agree in advance on who manages the policy and where important information can be found.
What the app does not solve by itself
The biggest barrier is the subject matter. Insurance is full of distinctions that cannot responsibly be reduced to a friendly button. A screen may help me reach a document, but it cannot make exclusions disappear or turn an uncertain situation into a straightforward one. I still need to read carefully, especially when deciding whether a particular event belongs in a claim conversation or whether a policy detail applies to my circumstances.
There is also a difference between accessibility and simplicity. An app can be easier than a website for one user and harder for another. Someone who has difficulty with small text may prefer a desktop browser. Someone who struggles with typing may prefer speaking to a person. Someone who needs an interpreter, detailed explanation, or help describing a complicated accident may find a direct conversation more suitable than navigating a self-service workflow.
Security creates another layer of friction. Login steps, verification, and account protection can interrupt a task, but they exist for a reason. I would rather spend extra time confirming identity than leave sensitive insurance information exposed on a shared device. If I use the app on a borrowed phone, I would be especially careful about saved credentials and would sign out when finished. Convenience should not mean treating policy information like a disposable note.
Older devices deserve attention as well. The current app version is 5.1.2, and it requires Android 6.0 or later. That makes it available to many existing Android users, but anyone relying on an older handset should check compatibility before planning around it. A user who cannot update the operating system may need to use another route for account management rather than discovering the limitation during an urgent situation.
The app is rated for Everyone, which makes its general audience broad, but an age label does not tell me whether every screen will be equally comfortable for every person. A young driver, an older customer, and someone with a disability may have very different needs even when they can all technically install the same app. I would judge it by the specific task I need to complete and by whether the phone’s own accessibility settings improve or complicate the experience.
How it compares with usual insurance alternatives
Compared with a mobile browser, a dedicated app can feel more direct because it is built around the insurer’s customer relationship rather than a general website. I do not have to begin by finding the correct page or remembering which part of the website contains account information. The trade-off is that an app takes storage, needs maintenance, and may be less comfortable than a browser on a large screen.
Compared with paper documents, the app is easier to search for when I am away from home and less likely to leave me carrying an outdated folder. Paper still has one clear advantage: it works without a battery, login, or network connection. For that reason, I would not throw away every useful record simply because the app exists. Digital access is convenient, but redundancy is sensible for travel and emergencies.
Compared with calling an insurance representative, the app can be faster for routine account checks and less intimidating for someone who prefers reading rather than speaking. A representative is usually the better choice when the issue is complicated, emotionally difficult, or dependent on details that a screen cannot interpret. I see the two options as complementary. The app helps me prepare a focused question, while a person can explain the answer when the wording or circumstances are not straightforward.
Compared with an insurer’s broader digital service, this app’s usefulness depends on whether I already have business with The General. It is not a general comparison tool for shopping across providers, and it should not be treated as independent advice about which policy is best for every driver. If my priority is comparing multiple insurers, I would use a separate comparison process. If my priority is managing an existing relationship with The General from a phone, this is the more relevant tool.
Who should use it, and who should choose another route?
I would recommend trying it to an existing The General customer who prefers mobile administration, wants quicker access to policy-related information, or does not regularly use a computer. It is also a sensible option for someone who wants to prepare before a trip and reduce dependence on paper records. The free price removes a financial obstacle to testing it, although using the app does not itself answer whether the underlying insurance is affordable or appropriate for a particular driver.
I would be more cautious recommending it as the only support route for a person who needs extensive assistance with insurance language, has unreliable phone access, or cannot comfortably read and operate a small touchscreen. That person may be better served by combining the app with a trusted helper, a larger device, or direct support. I would also steer away from app-only management if a household has complicated shared-driver arrangements and no clear plan for who handles the account.
The developer, The General Automobile Insurance Services, Inc, has maintained a mobile presence since the app’s release on April 11, 2012. That long-running availability is reassuring in the narrow sense that this is an established product rather than a newly launched utility. Still, longevity does not guarantee that every update will suit every device or that every workflow will feel effortless. I would install it, sign in when I have time, and test the exact features I expect to use before depending on it.
My inclusive verdict
After looking at the app through the lens of different abilities and contexts, I see The General® Auto Insurance as a useful access point rather than a complete replacement for human help, documents, or careful reading. Its main benefit is practical: it brings insurance administration closer to the customer’s everyday device. That can make a meaningful difference when I need information away from home or want to prepare before a stressful event.
The best accessibility feature is a workflow I can understand before I need it. I would set up access in advance, adjust my phone’s text and display settings, check whether the important screens remain comfortable, and keep an alternative way to find essential information. Those small preparations matter more than rushing to install an app after something has gone wrong.
With a 4.7 average and more than a million installs, it is clearly a widely used free business app rather than a niche experiment. The Everyone rating makes its intended audience broad, and the current 5.1.2 version supports a modern enough mobile experience for many Android users. My recommendation is positive for customers who want straightforward mobile access to their existing insurance relationship, but conditional for anyone who needs large-screen reading, extensive personal assistance, or a fully offline solution.
In everyday terms, I would keep it on my phone if I were insured through The General and comfortable managing routine details digitally. I would not let it replace judgment, careful policy reading, or direct help when a situation is complicated. Used that way, The General® Auto Insurance can reduce avoidable friction while still leaving room for the human support that insurance sometimes requires.
Pros
- User-friendly interface
- Affordable premiums
- Quick quote process
- Flexible payment options
- Available nationwide
Cons
- Limited coverage options
- No local agents
- Basic app features only
- Limited customer support
- High fees for late payments
Frequently Asked Questions
What types of auto insurance coverage does The General® Auto Insurance offer?
The General® Auto Insurance provides a variety of coverage options to meet different needs, including liability coverage, collision coverage, comprehensive coverage, and uninsured/underinsured motorist coverage. Additionally, they offer personal injury protection and roadside assistance. It's essential to evaluate your specific requirements and budget to choose the right coverage that fits your needs.
How can I get a quote from The General® Auto Insurance?
Getting a quote from The General® Auto Insurance is straightforward. You can visit their website or use their mobile app to enter your personal and vehicle information. The platform provides an instant quote based on the details you provide. Alternatively, you can also call their customer service for assistance in obtaining a quote.
Is The General® Auto Insurance suitable for high-risk drivers?
Yes, The General® Auto Insurance is known for offering policies to high-risk drivers, including those with a history of accidents, traffic violations, or poor credit scores. They specialize in providing coverage options for individuals who may have trouble getting insured by other companies, offering flexible policies to accommodate various risk levels.
What discounts are available with The General® Auto Insurance?
The General® Auto Insurance offers several discounts that can help lower your premium costs. These may include multi-car discounts, safe driver discounts, and discounts for paying your premium in full. It's a good idea to inquire about all available discounts when obtaining a quote to ensure you receive the best possible rate for your situation.
How can I file a claim with The General® Auto Insurance?
Filing a claim with The General® Auto Insurance is simple. You can file a claim online through their website or mobile app, or you can call their claims department directly. You'll need to provide details about the incident, including the date, time, location, and any involved parties. The General® will guide you through the process and help you with any necessary documentation.