Zip - Buy Now, Pay Later
- Rating
- 4.8
- Downloads
- 5,000,000+
- Age
- Everyone
Additional Info
- App Name
- Zip - Buy Now, Pay Later
- Category
- Shopping
- Package Name
- com.quadpay.quadpay
- Developer
- Zip, Co.
- Rating
- 4.8
- Version
- 1.238.4
 Analysis by Appcrazy
Shopping from a phone is easy; keeping track of how and when the money leaves your account is the part that deserves more attention. I spent time looking at Zip - Buy Now, Pay Later as a shopping app, and my impression is that its real value appears when you want to divide a purchase into scheduled payments rather than pay the entire amount immediately. The experience is built around that decision, so it feels more like a payment companion than a traditional store catalogue.
The app comes from Zip, Co. and is free to install for Everyone. It has reached over five million installs, with an average rating of 4.8 from around 95 thousand ratings. Those figures suggest that the idea is resonating with a large audience, but they do not remove the need to use it carefully. Splitting a payment can make a planned purchase easier to manage, yet it can also make spending feel less expensive than it really is.
What stood out to me most was how much the experience depends on a reliable connection at the exact moment you need it. That matters when you are standing at a checkout, switching between a retailer and Zip, or trying to confirm whether a payment has gone through. The app is convenient when the network behaves, but connectivity is not a minor background detail here; it is part of the payment experience.
How Zip feels when shopping depends on a live connection
When I use Zip at checkout, a live connection is part of the payment flow, not just a convenience for loading shopping pages. I find it helps to treat a slow screen as a reason to pause and verify the transaction, rather than tapping again; that small habit can prevent confusion about what has actually gone through.
Online checkout is where the idea makes the most sense
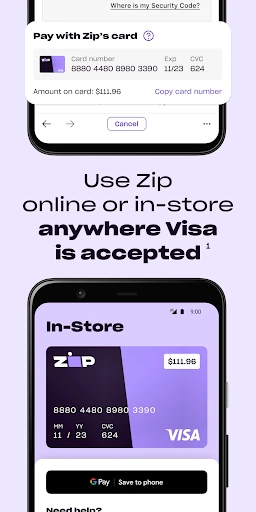
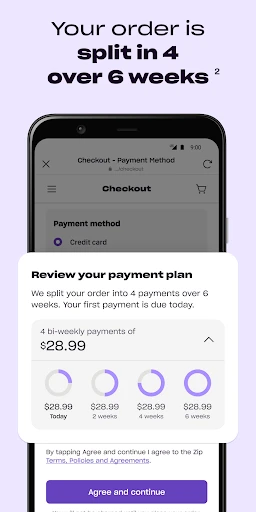
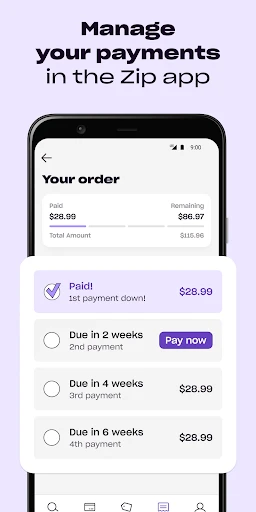
Zip is designed to help split payments online and in stores, so the first useful question is not simply whether you shop from your phone. It is whether you want a separate way to organize a purchase into installments. For an online order, that can mean moving through the retailer’s checkout and selecting or opening the Zip payment flow when the time comes to pay.
In my experience, this kind of process is easiest when I prepare before reaching the final checkout screen. I check the total, confirm that the retailer is the one I intended to use, and make sure my phone has a stable connection. That small pause avoids the most frustrating version of a payment problem: being unsure whether the order was submitted, whether the first payment was accepted, or whether trying again might create a duplicate attempt.
The app is not a replacement for comparing products, delivery terms, or return rules. It focuses on the payment arrangement. I would still begin with the retailer’s order details and only then decide whether splitting the cost is sensible. This is an important distinction because the convenience of a payment option can draw attention away from the total price, shipping, or the consequences of returning part of an order.
Catch Up on the Latest Stories
Microsoft Teams on Mobile Keeps Work Moving, If You Keep It Tidy
Groupon Turns Local Discounts Into a Marketplace, With a Catch
App of the Week: Yandex Go Makes City Errands Easier
Make Xiaomi Weather Work Harder with Smarter Settings and Daily Routines
Boomplay Turns Music Streaming Into a Daily Discovery Habit
Google Docs on Mobile Keeps the Page in Focus, Until Formatting Gets in the Way
A realistic in-store situation
Imagine I am in a shop and find a necessary household item that costs more than I planned for that day. With a strong mobile connection, I can use Zip as part of the payment process instead of immediately placing the whole purchase on a traditional card. The benefit is not that the item becomes cheaper; it is that the timing of the payments changes.
That difference is easy to overlook at a busy checkout. I would want to stop long enough to review the payment schedule before confirming anything. If I am rushing, dealing with a weak signal, or unable to remember other scheduled payments, I would rather postpone the purchase than make a decision based only on the first amount shown.
This is one of the app’s strongest practical use cases: a planned purchase where I already know the total, understand the future payment commitment, and have enough room in my budget for every installment. It is a much weaker fit for impulse shopping, especially when the split-payment format makes an unnecessary item feel harmless.
Why connectivity changes the experience
A shopping app can tolerate a delayed page or a slow image. A payment app cannot be judged by the same standard. When Zip needs to load account information, present a payment choice, or confirm a transaction, the phone needs to communicate with the relevant service. A poor signal can turn a simple checkout into a sequence of uncertain taps.
I would avoid relying on a crowded public network for an important purchase whenever possible. If I had to use one, I would pay close attention to the confirmation screen and keep the retailer’s order page open until I knew what happened. The practical rule is simple: never repeat a payment action just because the first screen took too long.
If the app appears frozen, I would first check whether the retailer has already created an order or whether my bank shows a pending authorization. Then I would reopen the app or checkout flow rather than immediately tapping the payment button again. This is not a Zip-specific guarantee about how every transaction behaves; it is a sensible recovery habit for any connected payment service.
Using it while moving around
Zip is naturally suited to mobile moments because the purchase may happen away from a desk. I can imagine using it while comparing prices in a store, checking a cart from public transport, or handling an unexpected but necessary purchase while traveling locally. The phone makes the payment option available at the moment of decision, which is useful but also makes it easier to act too quickly.
My preferred mobile workflow is to do the thinking before the checkout. I decide the maximum amount I am willing to spend, check whether the item is genuinely needed, and then use Zip only if the payment plan fits that decision. This prevents the app from becoming a reason to increase the budget simply because the initial payment looks manageable.
Screen size also changes how carefully I read. On a phone, payment amounts and dates may be separated across screens or displayed in compact sections. I would expand every relevant detail and review the complete schedule rather than relying on a headline amount. If I cannot clearly understand what will be paid and when, that is a good reason to stop and use a more familiar payment method.
What happens when a connection fails
The most uncomfortable moment is a checkout that loses connection after I have submitted a payment. The app may not immediately tell me whether the action succeeded, while the retailer may still be processing the order. In that situation, patience is more useful than repeated tapping. I would wait briefly, check for a confirmation in the app or retailer account, and look for an order record before attempting anything again.
If the purchase does not appear complete, I would record the time, amount, and retailer while the details are fresh. That makes any later support conversation clearer. I would also keep screenshots of visible confirmation or error messages where appropriate, without sharing sensitive payment information publicly.
A failure can happen at several points: the retailer page may time out, the mobile connection may drop, or the app may need to refresh account information. Treating all of these as the same problem can lead to unnecessary retries. I find it more useful to identify the last screen I definitely saw and continue from there only after checking whether the transaction already exists.
Recovering without losing track of future payments
Recovery is not only about completing the purchase. It is also about making sure a failed or interrupted attempt has not left me confused about future installments. Once the connection returns, I would open the app and review the account activity instead of assuming that an abandoned checkout had no effect.
This is particularly important if I use Zip for more than one purchase. A payment plan that seemed affordable on its own can become difficult to remember when several plans overlap. I would keep a simple personal note of the retailer, total, and expected payment dates. That is not glamorous, but it gives me a second reference point if the app is temporarily unavailable or if I am reviewing my monthly budget away from the checkout screen.
If a payment looks unfamiliar, I would avoid guessing. I would compare it with recent purchases, check the retailer’s order history, and use Zip’s available account or support path to resolve the issue. The app can organize the payment process, but I still need to monitor my own spending and recognize when something does not match my records.
Being careful with mobile data
Zip is not the kind of app I would open repeatedly just to browse for entertainment. Its useful moments are usually short: checking a payment option, reviewing an existing plan, or handling a purchase. That makes it relatively easy to use in a data-conscious way without trying to keep every screen loaded.
When I am on mobile data, I would open the app only when I am ready to complete a specific task. I would avoid switching back and forth unnecessarily between the retailer, payment screen, and account history, especially in an area with an unstable signal. A stable Wi-Fi connection is preferable for a larger purchase, but I would still verify that I am using a network I trust before entering sensitive information.
The bigger data-conscious habit is financial rather than technical: use the app to review commitments, not just to authorize them. A quick account check after shopping can reveal whether the purchase was recorded as expected. It also helps me notice overlapping plans before I make another decision. In that sense, the best use of connectivity is not constant access; it is timely access at the moments when accurate information matters.
How it compares with paying normally
The usual alternatives are straightforward: pay with a debit card, use a credit card, or wait until the full amount is available. Those methods can be easier to understand because the timing of the charge is familiar. Zip’s advantage is flexibility for a purchase that I can afford overall but would prefer to divide across scheduled payments.
That flexibility comes with extra responsibility. A normal card transaction may be visible in one account statement, while split payments require me to remember a series of future commitments. For someone who already tracks a budget carefully, that structure can be useful. For someone who tends to forget subscriptions, bills, or pending transactions, adding another payment schedule may create more stress than convenience.
I would also choose a traditional payment method when the network is unreliable or when the checkout needs to be completed immediately. The best option is the one that leaves me certain about the transaction, not necessarily the one with the most modern payment flow. Zip is most appealing when I have time to review the terms and a clear reason to spread the cost.
Who should use it, and who should skip it
I see Zip as a good match for shoppers who want a mobile way to divide a known purchase, are comfortable reviewing scheduled payments, and can maintain a reliable connection during checkout. It may be especially practical for planned online orders or in-store purchases where paying the full amount today would be inconvenient but the total remains within a realistic budget.
I would be cautious if I am using it to make an unaffordable purchase appear affordable. I would also skip it if I dislike managing multiple payment dates, frequently lose track of account activity, or cannot reliably connect when shopping. In those cases, paying in full or waiting may be simpler and safer.
The app is free, which removes an installation cost, but “free” should not be confused with free shopping. The important commitment is the purchase itself and the schedule attached to it. Before confirming, I would consider the complete amount, not merely the first payment presented on the phone.
Version and everyday usability
The current version is 1.238.4, and the app supports devices running Android 8.1 or later. That makes the Android requirement worth checking before installation, especially if I am using an older phone. The Everyone content rating also makes the app broadly accessible from a store-rating perspective, though the financial decisions involved still call for adult judgment and careful supervision where appropriate.
Because payment apps can change their screens over time, I would not rely on an old memory of where a button appeared. After an update, I would take a moment to locate account activity, payment details, and help options before starting a purchase. This is a small habit, but it reduces mistakes when I am already standing at a checkout and the network is busy.
My overall view is positive but conditional. Zip makes sense when I treat it as a budgeting and payment tool rather than extra spending power. Its mobile design is useful precisely because it travels with me, yet that same convenience can shorten the time between wanting something and committing to it. A reliable connection improves the experience, but careful reading and personal budgeting matter more.
After using it as a shopping-focused payment option, I would recommend it to a friend who has a specific purchase in mind, understands the future schedule, and is willing to verify every transaction. I would not recommend opening it casually whenever a purchase feels slightly out of reach. My connectivity verdict is that Zip works best when the signal is stable, the checkout is deliberate, and the user remains in control of the full payment plan.
For that kind of shopper, Zip - Buy Now, Pay Later offers a convenient alternative to paying everything at once. For anyone hoping the app will make an expensive purchase genuinely cheaper, or anyone who finds scheduled payments hard to track, a conventional payment method is likely the better choice.
Pros
- Flexible payment options for purchases.
- No interest charges if paid on time.
- User-friendly interface for easy navigation.
- Quick approval process for new users.
- Can boost credit score with responsible use.
Cons
- Limited to partnered retailers only.
- Late fees can be steep if not careful.
- Requires a good credit score for approval.
- Not available in all countries.
- May encourage overspending for some users.
Frequently Asked Questions
What is Zip - Buy Now, Pay Later?
Zip - Buy Now, Pay Later is a financial app that allows users to purchase items immediately and pay for them over time in installments. It offers a flexible payment solution without the need for a credit card, making it easier for users to manage their expenses while shopping online or in-store.
How does Zip ensure the security of my financial information?
Zip employs advanced security measures to protect your financial information, including encryption technology and secure servers. Additionally, the app requires user authentication for every transaction, ensuring that your personal and financial data remains confidential and safe from unauthorized access.
What are the eligibility requirements to use Zip?
To use Zip, users typically need to be at least 18 years old, have a valid email address, and possess a verifiable mobile number. Additionally, users must have a source of income and a bank account or debit card to set up payment installments. Specific requirements may vary depending on the user's country of residence.
Are there any fees associated with using Zip?
While Zip does not charge interest on the installments, there may be fees for late payments or account maintenance, depending on the terms and conditions applicable in your region. It's important for users to review the fee structure and payment terms before using the service to avoid any unexpected charges.
Can I use Zip for both online and in-store purchases?
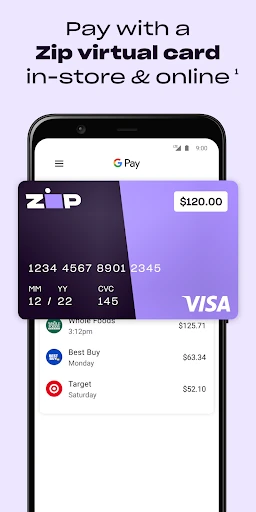
Yes, Zip can be used for both online and in-store purchases at participating retailers. For online shopping, users can select Zip as a payment method at checkout. For in-store purchases, the app provides a barcode or a virtual card that can be scanned at the point of sale, making it a versatile payment solution.