 Article about Google Wallet
Google Wallet Makes Paying Feel Effortless by Getting Out of the Way
The best thing about Google Wallet is not that it puts a bank card on a phone. It is that, at a busy checkout, the phone can become the least interesting part of the transaction. A quick unlock, a tap, and you are already putting the groceries away. That calm handoff is the feature worth examining: contactless payment is simple on the surface, but its value depends on trust, timing, and a design that gets out of the way.
That promise is strongest when you have the right card set up and your phone is ready. It is not magic, and it does not eliminate every delay. But in ordinary use, paying with a phone can replace the little search-and-fumble ritual of finding a wallet, choosing a card, and holding up the line. The improvement is measured in seconds, yet repeated several times a day those seconds make a convincing case for keeping the feature close.

Google LLC · Finance · Free
One tap, with the details handled beforehand
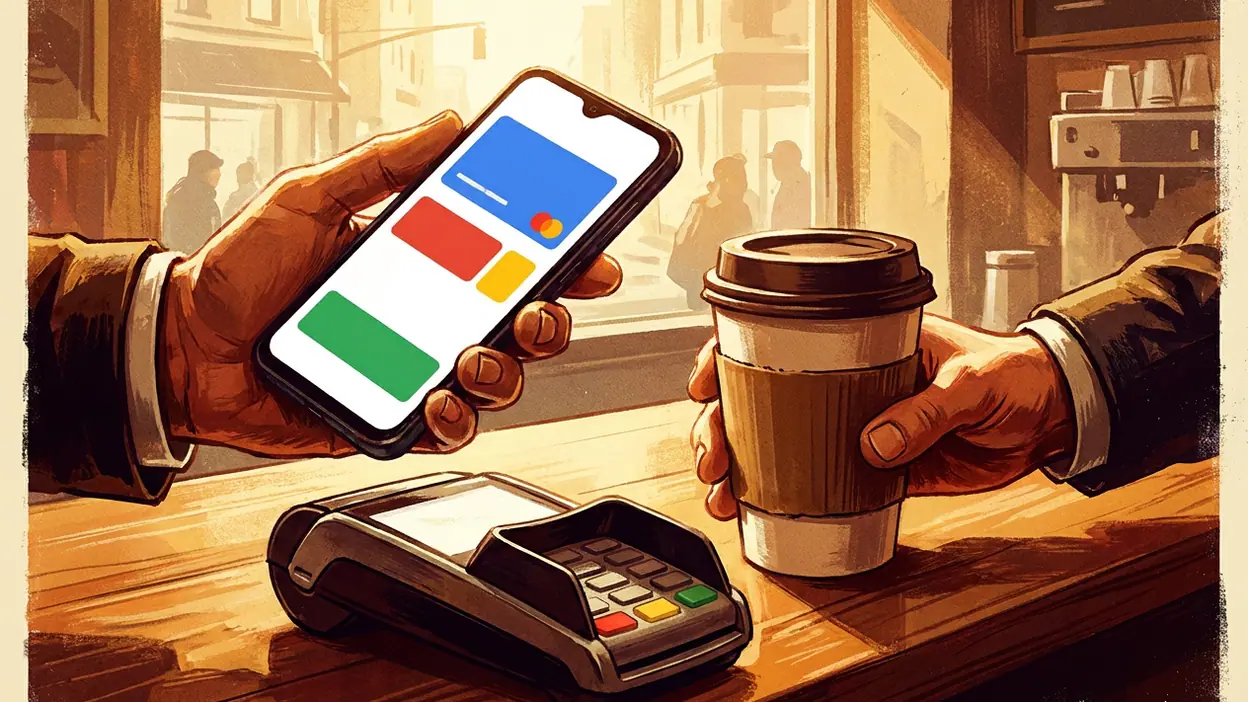
At its core, tap-to-pay lets a compatible Android phone make contactless payments at supported terminals. You add an eligible payment card, complete the bank’s verification steps, and choose which card should be used by default. At checkout, you unlock the phone as required by your device and payment settings, then hold it near the terminal’s contactless reader. The terminal handles the rest of the purchase.
The important distinction is that the payment card is not simply a picture stored on the screen. The transaction relies on the phone’s secure payment capabilities and the payment network’s tokenization, which substitutes a device-specific token for the card number in the transaction flow. That does not make every possible risk disappear, but it limits the exposure of the underlying card details compared with handing over the physical card. Banks may still apply their own verification rules, and some transactions can require additional checks.
The app also provides a place to manage payment methods and review activity, though what appears can vary by bank, card, region, and device. The setup takes longer than the eventual payment. That is the bargain: do the administrative work once, then use a much shorter gesture whenever a terminal accepts contactless payments.
Why a few seconds matter
Contactless payment is easy to dismiss as a minor convenience because the physical alternative is already fairly quick. But the real comparison is not one tap versus one card swipe. It is the whole sequence: noticing the total, finding the right pocket, opening a wallet, avoiding the loyalty card you do not need, presenting the payment card, and packing up while the next customer waits.
Paying by phone compresses that sequence. It also reduces the chance of leaving a payment card behind on a counter or discovering that the card you meant to use is in another bag. The benefit becomes more noticeable when your hands are occupied, when you are carrying a child’s things, or when you have ducked into a shop during a short break. None of those moments calls for a grand technology story. They call for one less thing to manage.
There is a subtler gain, too: the payment ritual becomes predictable. Once a default card is selected and the phone’s security settings are familiar, you do not have to rehearse the process every time. Predictability is a practical form of confidence. You know where the payment method is, how to authorize it, and what to do if the first tap does not register.
The strongest everyday test
The clearest use case is a routine errand with several small purchases: coffee, a transit fare where supported, then a quick stop at a pharmacy or grocery store. Each individual payment is too small to justify planning around, which is exactly why the feature earns its keep. You can leave the physical wallet in your bag and use the same device you already carry, provided the merchant’s terminal accepts contactless payments and your setup is working.
That last qualification matters. A phone is not a universal replacement for every card, ticket, or identification document. Acceptance varies by merchant and country, and some places still require a physical card or another form of payment. A dead battery can also turn a convenient default into a poor backup plan, depending on the device and its remaining power. I would treat phone payment as the easiest option, not the only option.
There is a good reason to keep a backup card nearby on travel days or during long outings. The app can reduce the number of times you need that backup; it cannot guarantee that every terminal, issuer, or local payment setup will cooperate. The realistic promise is fewer interruptions, not a cashless life without exceptions.
How the habit changes
Once tapping with a phone feels ordinary, the change is less about spending and more about preparation. You start checking that your default card is right before a trip, keeping the phone accessible at the checkout, and thinking of the physical wallet as a backup rather than the first thing you reach for. The behavior becomes almost automatic, but it still rests on deliberate choices made in settings.
This can make a wallet feel lighter, though it does not make the phone itself disappear from the transaction. You must still have it with you, keep it charged, and unlock it in the way your device requires. That is a trade, not a free upgrade. For someone already carrying a phone everywhere, it is usually a favorable one. For someone who prefers to leave the phone put away, the physical card may remain simpler.
The app’s usefulness also comes from reducing the need to think about payment technology. There is no elaborate routine to learn at the counter. If the terminal supports contactless, hold the phone close and wait for the confirmation. When it works, the interaction is brief enough that you can pay without turning the checkout into a phone task.
Good design is mostly restraint
The smart part of the design is how little it asks of you at the point of sale. Payment cards are arranged for selection before you need them; the actual checkout action is compact. The phone’s lock and authentication systems provide the security checkpoint, rather than asking you to navigate through menus while a cashier waits. That separation between setup and use is well judged.
It also helps that the action is familiar. Contactless readers are common, and using a phone near one resembles using a contactless card. There is no separate payment ritual that needs explaining to the person behind the till. When the terminal beeps and the purchase completes, the phone has done its job without demanding attention.
Still, clarity depends on the supporting details. Your bank must support the card, verification must complete, and your device must meet the relevant requirements. If any of those pieces are unclear, a feature designed to remove friction can create it during setup. Guidance can vary between issuers, and troubleshooting may send you between the wallet app, bank app, and device settings.
Where the friction remains
The main limitation is that the experience is not entirely controlled by the app. A card may be unsupported, a bank may impose extra verification, or a merchant’s reader may not work as expected. Those are frustrating precisely because the payment gesture itself is so simple: when the tap fails, the cause is not always obvious. You may need to try again, unlock the phone, switch cards, or use the physical one.
There is also a practical privacy distinction worth keeping in view. Tokenization helps protect card details during a payment, but using a digital wallet does not mean your financial life is invisible. Your bank records transactions, and the app may show payment activity and other information according to its features and settings. Anyone choosing a payment method should understand which company handles which part of the transaction, rather than treating a phone as a privacy shield.
Finally, phone payment is only as convenient as the phone’s availability. A forgotten device, low battery, damaged screen, or security setting that interrupts checkout can make the old card feel reassuringly dependable. The app does not make the physical wallet obsolete for everyone. Its value is that it makes carrying and reaching for that wallet less necessary.
Different wallets, different jobs
Apple Pay handles the same basic problem on Apple devices: it gives users a way to pay at compatible contactless terminals using a phone or watch. The choice between them is largely shaped by the device people already own, along with card and bank support. The useful comparison is not which service has the grander idea; both aim to make the payment gesture short and secure. The day-to-day experience depends on setup, issuer support, and how reliably the local shops accept contactless payments.
Google Wallet’s distinction is its place within the Android ecosystem and its broader role as a home for supported cards and passes, rather than just a digital bank card. That breadth can be handy, but it should not distract from the feature’s central test: can you pay quickly at the places you actually visit? If your bank and nearby merchants are supported, the answer is often yes. If not, a feature-rich app cannot compensate for the gap.
Other finance apps may help people compare prices, manage accounts, or find savings, but those are different jobs. A coupon tool can lower a prescription bill; it does not replace the fast, dependable act of presenting a payment method. Keeping the comparison narrow makes the strength here clearer: the most useful payment feature is the one that removes a step without adding a new decision.
Who gets the most from it
Frequent commuters, city shoppers, and anyone who already keeps an Android phone in hand will notice the benefit most. It is especially appealing if you carry several cards but tend to use one default card for everyday purchases. People who value a lighter pocket or want a more contained way to carry supported payment cards have a clear reason to set it up, as long as their bank and region are covered.
It is less compelling for someone who rarely uses contactless terminals, does not want payment credentials on a phone, or has a device that is often uncharged. It may also add little for people whose preferred card is unsupported. Those are not failures of personal preference; they are signs that convenience depends on fit. Before relying on the app, it is sensible to confirm card support and try a low-stakes purchase.
After using it for ordinary checkout, my judgment is straightforward: Google Wallet earns its place through a small, repeatable improvement, not spectacle. Tap-to-pay is at its best when it feels almost forgettable: the right card is ready, the terminal recognizes the phone, and the transaction is over before the moment becomes a hassle. Its limits are real, especially around availability and setup, so I would not abandon a backup card. But for compatible Android users who pay contactlessly often, this is a genuinely useful feature precisely because it asks for so little once it is working.